
A crypto-friendly bank either provides cryptocurrency services or permits payments to supported crypto exchanges. Some combine Bitcoin trading, custody, and fiat accounts. Others offer conventional banking while allowing customers to fund independent exchanges.
Xapo Bank ranks first in our 2026 comparison for its integrated Bitcoin and USD services. SoFi Bank is our U.S. retail choice, Revolut combines daily banking with cryptocurrency, and Monzo is useful for UK exchange transfers. Sygnum Bank specializes in institutional custody, while Bank Frick serves crypto businesses and professional intermediaries.
Editor's Note (Oct. 14, 2026): We fully updated this guide in October 2026 with a focused ranking of six crypto-friendly banks, adding Xapo and SoFi alongside refreshed reviews of Revolut, Monzo, Sygnum, and Bank Frick. We verified current crypto services, fees, eligibility, exchange transfer restrictions, and regulatory developments. We also expanded the comparisons of banking costs, crypto custody, deposit protection, and account requirements to help readers make more informed decisions.
Best Crypto-Friendly Banks in 2026: Quick Answer
Xapo Bank is our overall pick for crypto-friendly banking in 2026. It combines USD banking with Bitcoin trading, custody, stablecoin funding, and supported crypto withdrawals. SoFi is our top choice for U.S. retail investors, Revolut suits everyday banking and crypto access, and Monzo is best for UK payments to supported exchanges. Sygnum and Bank Frick cater to institutional investors and crypto businesses, respectively.
Best Crypto-Friendly Banks by Use Case
-
Xapo Bank: Best overall for Bitcoin banking Combines USD accounts, Bitcoin trading and custody, stablecoin funding, and international payment services. Best suited to larger Bitcoin portfolios, given its $1,000 annual membership and exclusion of U.S. residents.
-
SoFi Bank: Best for U.S. crypto investors Offers cryptocurrency trading alongside checking and savings, with no standard monthly account fee. Supports 29 cryptocurrencies for trading and external transfers for 12 assets, although trading fees start at 1.90%.
-
Revolut: Best for everyday banking and crypto Combines multi-currency accounts, cards, international payments, and cryptocurrency trading. Revolut X offers 0% maker and 0.09% taker fees, with features and protections varying by region.
-
Monzo: Best for UK crypto exchange transfers Provides a free UK current account with Faster Payments and documented Coinbase compatibility. Crypto payments are limited to £5,000 over a rolling 30 days, and Binance payments are blocked.
-
Sygnum Bank: Best for institutional crypto custody A FINMA-regulated Swiss bank offering custody for more than 70 digital assets, alongside institutional trading, staking, and lending. Designed for qualified investors, funds, family offices, and asset managers.
-
Bank Frick: Best for crypto businesses Offers business banking, digital asset custody, trading, staking, and specialized fiat settlement. Its MiCA authorization and xPULSE payment infrastructure suit exchanges, brokers, and professional intermediaries.
Disclaimer
Crypto-friendly banking does not guarantee approval of transfers to cryptocurrency exchanges. Supported services, fees, account eligibility, and payment restrictions vary by jurisdiction and legal entity. Eligible fiat deposits may receive government-backed deposit protection, but cryptocurrency holdings are generally not covered by deposit insurance. Confirm current terms and eligibility directly with each provider before opening an account or transferring funds.
Disclosure
Some links in this guide may be affiliate links. If you sign up for or use a platform through these links, we may earn a commission at no additional cost to you.
Best Crypto-Friendly Banks in 2026 at a Glance
Xapo Bank ranks first for Bitcoin and USD banking, followed by SoFi Bank for U.S. crypto investors, Revolut for everyday banking and crypto, Monzo for UK exchange transfers, Sygnum Bank for institutional custody, and Bank Frick for crypto businesses. Together, they represent integrated crypto banking, conventional banking with exchange access, and professional digital asset services.
| Bank | Best For | Main Region | Crypto Services | Fiat-to-Crypto Access | Crypto Withdrawals | Account Fees | Key Limitation |
|---|---|---|---|---|---|---|---|
| 1. Xapo Bank | Bitcoin and USD banking | Gibraltar; eligible international markets | BTC trading, custody, savings | Native BTC purchases; stablecoin funding | BTC supported | $1,000/year | No U.S. residents; expensive membership |
| 2. SoFi Bank | U.S. retail investors | United States | Trading, custody, SoFiUSD | SoFi account; eligible card and digital-wallet payments | 12 assets supported | No standard maintenance fee | U.S. eligibility and linked bank account |
| 3. Revolut | Everyday banking and crypto | UK, EEA; other supported countries | App trading, custody, Revolut X | Integrated purchases; selected external routes | Selected assets supported | Free Standard; paid upgrades | Regional entity and feature differences |
| 4. Monzo | UK exchange payments | United Kingdom | No native crypto services | Payments to approved exchanges | Not applicable | Free standard account | £5,000 rolling limit; Binance blocked |
| 5. Sygnum Bank | Institutional custody | Switzerland; eligible international markets | Custody, trading, staking, lending | Institutional trading | Approved withdrawals | Relationship-specific | Professional eligibility |
| 6. Bank Frick | Crypto business banking | Liechtenstein, EEA; selected markets | Custody, trading, staking, settlement | Trading and approved business payments | Approved withdrawals | CHF 50/quarter standard tariff | Business onboarding and service costs |
*Policies and published fees checked Oct. 14, 2026. Availability depends on the customer, legal entity, and jurisdiction.
Xapo, SoFi, and Revolut represent integrated crypto banking: eligible customers can access cryptocurrency through a banking platform or affiliated service.
Monzo represents crypto-compatible conventional banking: it permits certain exchange transfers but does not hold Bitcoin.
Sygnum and Bank Frick provide professional digital asset banking, with specialized custody, trading, and settlement for institutions and businesses.
Read our full Xapo Bank review.
What Makes a Bank Crypto-Friendly?
A crypto-friendly bank is a licensed bank that either offers eligible cryptocurrency services through its group or permits legitimate payments to selected cryptocurrency businesses. That label does not imply unrestricted exchange transfers, universal crypto custody, or government insurance on digital assets.
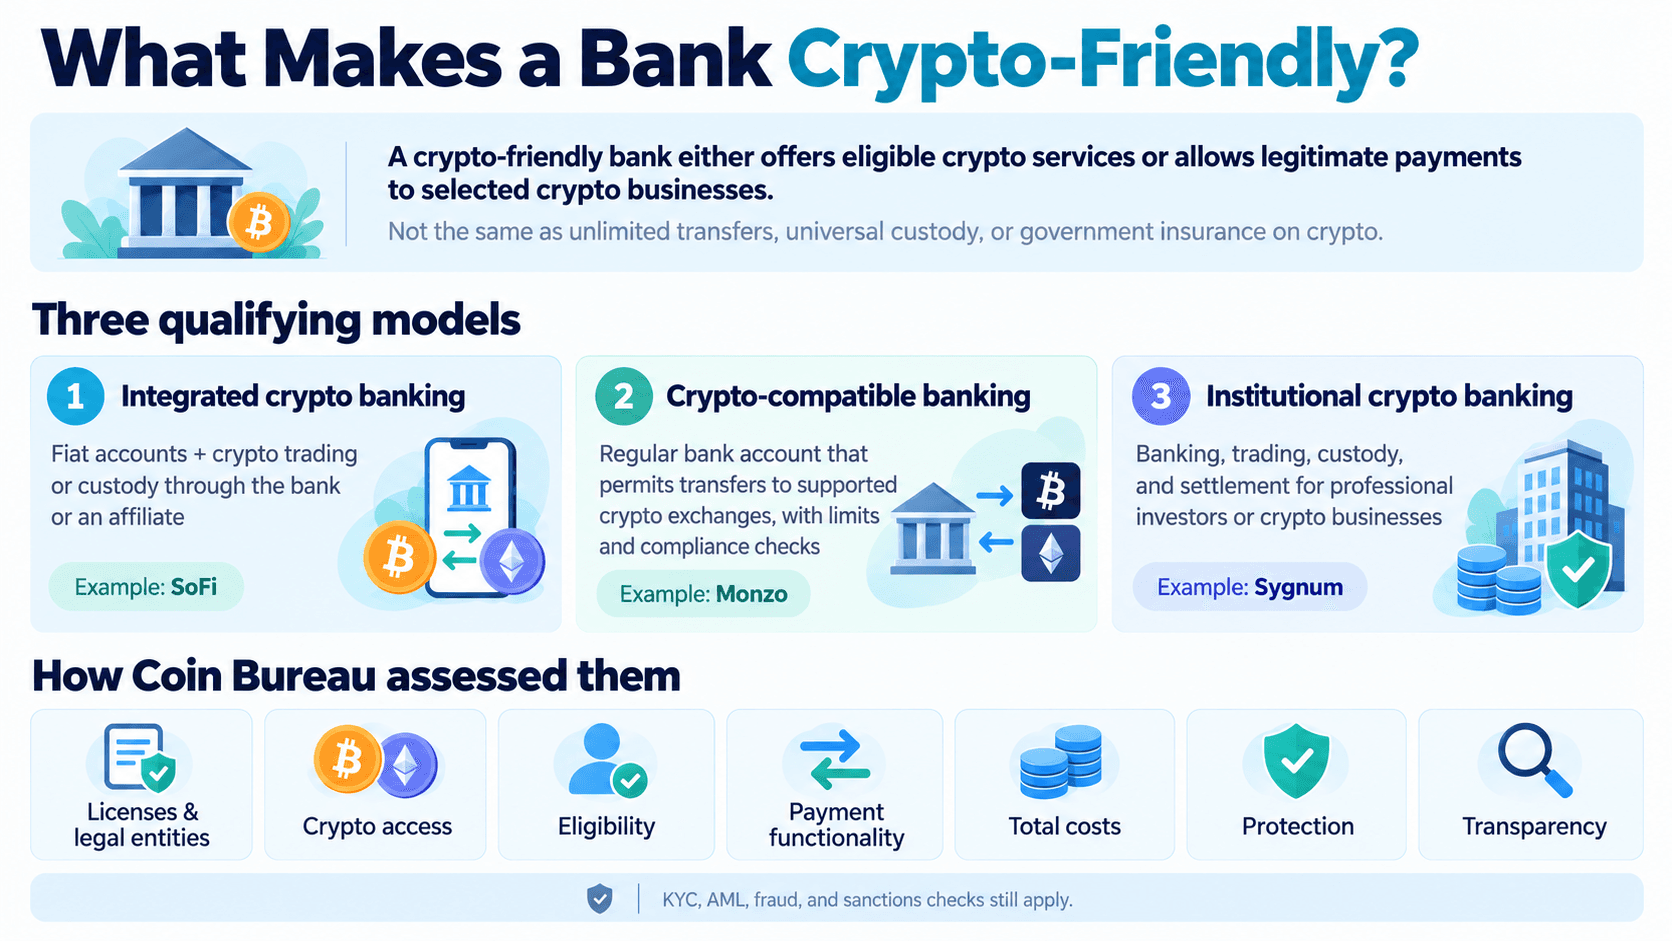 The Three Types of Crypto-Friendly Banking and the Key Criteria Coin Bureau Uses to Evaluate Them
What Qualifies a Bank as Crypto-Friendly?
Three models qualify:
- Integrated crypto banking: Fiat accounts plus cryptocurrency trading, custody, or related services through a bank or affiliated regulated company.
- Crypto-compatible banking: Conventional accounts that permit deposits to and withdrawals from supported crypto exchanges, subject to limits and compliance checks.
- Institutional crypto banking: Banking, trading, custody, and settlement for professional investors, funds, or crypto businesses.
SoFi offers native trading; Monzo supports selected exchange payments; Sygnum serves institutions needing regulated custody.
How We Selected the Best Crypto-Friendly Banks (Methodology)
Coin Bureau assessed the six providers against seven criteria:
- Licenses and legal entities: Verified banking authorization and the appropriate regulator, including the GFSC, OCC, FCA/PRA, FINMA, or Liechtenstein FMA.
- Crypto access: Current native products or documented external-exchange compatibility.
- Eligibility: Countries, residency requirements, and retail versus professional onboarding.
- Payment functionality: Fiat transfers, crypto withdrawals, transaction limits, and blocked destinations.
- Total costs: Memberships, trading fees, spreads, FX, withdrawal charges, and custody fees.
- Protection: Fiat deposit guarantees, crypto ownership, and custody arrangements.
- Transparency: Public account policies, regulatory records, and official fee schedules.
A supported transfer route is not a promise of approval: banks still apply know-your-customer (KYC), anti-money laundering (AML), fraud, and sanctions screening. Read our guide on the importance of KYC and AML in detail.
Best Crypto-Friendly Banks Reviewed
The six reviews apply the same framework: products, fiat access, pricing, eligibility, customer protection, and practical suitability.
1. Xapo Bank: Best Overall for Bitcoin Banking
Xapo Bank is our top pick for customers who want Bitcoin and USD services together. It combines a dollar account with BTC trading, custody, savings, and transfers. Its $1,000 annual membership makes it unsuitable for occasional buyers.
Xapo Bank Limited provides Gibraltar-regulated fiat banking; Xapo VASP Limited separately provides crypto services under the Gibraltar Financial Services Commission (GFSC). Xapo Credit Limited handles eligible Bitcoin-backed lending.
Customers can buy and sell BTC, use MPC-based Bitcoin custody, fund dollar balances using supported stablecoins, and send Bitcoin on supported networks, including Lightning. Xapo's card and banking account support eligible everyday payments.
Its savings services have different risks. USD Savings currently advertises a 4.1% variable APY, paid in Bitcoin, while liquid BTC Savings has its own variable BTC reward. The separate BTC Credit Fund lends pooled Bitcoin to institutional counterparties; it requires the BTC equivalent of $120,000 and normally has monthly redemptions with 30 days' notice. Credit-fund returns introduce lending and liquidity risk rather than ordinary deposit interest. Xapo's Bitcoin-backed loans have jurisdictional restrictions, including no availability for UK or Australian residents.
Xapo offers supported SWIFT, ACH, SEPA, and Faster Payments routes. Eligible USDC deposits on Ethereum and Solana, and USDT deposits on Ethereum and Tron, are converted to USD. Xapo advertises 1:1 USDC-to-USD conversion on Ethereum without an extra Xapo conversion fee; USDC deposits on Solana carry a published 0.10% spread, and other routes can involve spreads or network charges. BTC can be withdrawn to eligible external wallets. Individual external-exchange transfers remain subject to counterparty and compliance checks.
The annual membership is $1,000. Published payment charges include £0.15 per UK Faster Payments transfer; SEPA deposits at €0.10, standard outbound transfers at €0.15, and instant transfers at €0.20; FedACH deposits at $0.50 plus 0.10%; FedWire deposits at $20 plus 0.10%; and FedACH withdrawals at $30 plus 0.15%. Its published BTC exchange spread is 0.29%, variable rather than guaranteed. Membership requires accepted-country residency, identity checks, and proof of address; U.S. residents are excluded.
Eligible dollar deposits at Xapo Bank Limited fall under the Gibraltar Deposit Guarantee Scheme, up to the USD equivalent of £120,000. BTC held through Xapo VASP Limited is not covered. Xapo describes segregated customer crypto holdings and MPC controls, but those do not insure Bitcoin against market or operational losses.
- Larger Bitcoin portfolios seeking integrated USD banking.
- Eligible customers regularly using BTC and international payments.
- U.S. residents or occasional small buyers.
- Users seeking extensive altcoin deposit and withdrawal support.
- Integrated BTC custody, USD banking, and stablecoin funding.
- Regulated entities and international payment rails.
- $1,000 membership and residency restrictions.
- Limited altcoin transfers; uninsured BTC and variable yields.
Xapo offers the deepest Bitcoin banking proposition here. The annual fee is defensible for customers using several of its services, not for someone making a few small purchases per year.
2. SoFi Bank: Best for U.S. Crypto Investors
SoFi is our preferred U.S. retail option because eligible customers can buy cryptocurrency alongside checking and savings. Its main drawback is higher trading fees than many specialist exchanges.
SoFi Bank, N.A. is a nationally chartered bank regulated by the Office of the Comptroller of the Currency (OCC) and a member of the Federal Deposit Insurance Corporation (FDIC). It introduced consumer crypto trading in late 2025. SoFi Crypto currently lists 29 cryptocurrencies for trading, including Bitcoin, Ethereum, Solana, and XRP, with recurring purchases and custodial holdings.
Customers can also transfer 12 supported cryptocurrencies to external wallets, subject to asset and network limits. In May 2026 SoFi introduced consumer access to SoFiUSD (SOFID), a bank-issued payment stablecoin intended to maintain a dollar value. It is a distinct crypto product, not an insured checking deposit.
Purchases can draw from a connected SoFi checking or savings account or available SoFi Crypto balance. Eligible customers can also buy with Apple Pay, Google Pay, or a debit card, subject to a $5 minimum and a combined $2,800 weekly limit; those payment options are unavailable to New York residents. Supported crypto can be sent to eligible wallet or exchange addresses, but blockchain networks must match. Payments and withdrawals face recipient screening.
SoFi has no standard account maintenance fee for its checking, savings, or crypto products. Its crypto trading fees depend on monthly completed trading volume:
| Monthly Crypto Buy/Sell Volume | Fee |
|---|---|
| Below $1,000 | 1.90% |
| $1,000 to $4,999.99 | 1.50% |
| $5,000 to $9,999.99 | 1.25% |
| $10,000 or more | 0.90% |
Trading fees are included in the quoted price; certain orders may incur an additional spread, and withdrawals can involve network charges. Apple Pay, Google Pay, and debit card purchases also incur a 2% payment-processing fee on top of the applicable trading fee. Eligible U.S. customers need a linked SoFi banking account for account opening, although eligible purchases may use the additional funding methods.
Ordinary eligible bank deposits receive FDIC protection, generally $250,000 per depositor, per insured bank, per ownership category. Cryptocurrency and SoFiUSD are not FDIC-insured.
- U.S. banking customers wanting integrated crypto purchases.
- Recurring investors who value convenience over the lowest fee.
- Non-U.S. customers or fee-sensitive active traders.
- Users requiring all assets to be withdrawable on every network.
- National banking charter and connected crypto trading.
- No standard account maintenance fee; external wallet transfers.
- Trading fees start at 1.90%.
- Geographic and network restrictions; crypto not insured.
SoFi is compelling for eligible U.S. customers consolidating routine banking and crypto purchases. Frequent traders should calculate execution costs before choosing convenience over a dedicated exchange.
3. Revolut: Best for Everyday Banking and Crypto
Revolut suits customers who want daily payments, foreign exchange, and cryptocurrency access in one financial app. Revolut X adds cheaper order-book trading, but available products and legal protections differ between regions.
Revolut combines multi-currency balances, domestic and international transfers, cards, in-app cryptocurrency trading, and selected external-wallet withdrawals. Revolut X targets more active traders with market and limit orders rather than the standard app's convenience-oriented conversion flow. Supported tokens and withdrawal networks depend on jurisdiction.
Eligible customers can buy cryptocurrency from fiat balances and sell back to supported currencies. Certain crypto assets can be withdrawn externally, with service and blockchain network charges.
Revolut's UK personal plans cost £0 Standard, £3.99 Plus, £7.99 Premium, £14.99 Metal, and £55 Ultra monthly. The standard UK app's published crypto fees are 1.49% for Standard/Plus and 0.99% for Premium/Metal, subject to minimum fees. Ultra uses volume-based pricing, starting at 0.49% for rolling 30-day trading volumes below £10,000 and falling to 0% for volumes of £250,000 or more. Exchange-rate costs may also apply. Revolut X publishes 0% maker and 0.09% taker for eligible order-book trades.
Standard customers have a £1,000 monthly exchange allowance, with a 1% fair-use fee above it; Plus has £3,000 and 0.5%. Higher plans have no fair-use surcharge. The weekend FX markup is an additional 1% for Standard and 0.5% for Plus, from Friday 5 p.m. to Sunday 6 p.m. Eastern Time. Premium, Metal, and Ultra avoid that markup under current UK terms.
Revolut Bank UK Ltd began launching full banking operations in March 2026. UK customers transitioned to its bank deposits can qualify for FSCS protection up to £120,000; those still under Revolut Ltd's e-money arrangements instead have safeguarding protection. In the EEA, Revolut Bank UAB provides eligible deposits under Lithuanian coverage generally up to €100,000. EEA cryptocurrency services are provided through MiCA-authorized Revolut Digital Assets Europe Ltd, supervised by CySEC; UK crypto uses separate arrangements. Crypto is outside ordinary bank deposit insurance.
- Everyday banking, international transfers, and occasional crypto purchases.
- Eligible Revolut X users wanting lower trading commissions.
- Customers needing identical products across countries.
- Users trading frequently through the higher-fee standard app.
- Banking, FX, cards, and crypto in one app.
- Free entry plan and low Revolut X maker-taker fees.
- Complex regional legal entities.
- Standard-app fees, FX surcharges, and limited withdrawals.
Revolut offers the broadest everyday financial toolkit here. Revolut X strengthens its trading proposition, but regional product terms deserve more attention than the app's convenience suggests.
4. Monzo: Best for UK Crypto Exchange Transfers
Monzo is our UK choice for occasional payments to supported exchanges, not for native crypto trading. The bank publishes a clear £5,000 crypto allowance and explicitly distinguishes Coinbase from Binance.
Monzo Bank Ltd is a UK bank supervised by the Prudential Regulation Authority (PRA) and Financial Conduct Authority (FCA). Its conventional current account supports GBP Faster Payments, debit cards, and app-based spending controls. It does not offer Bitcoin trading, crypto custody, or a custodial wallet.
Monzo confirms Coinbase compatibility, subject to normal fraud checks. Its £5,000 crypto payment allowance runs over a rolling 30-day period, not a calendar month; customers cannot request a higher limit. Monzo also blocks Binance payments, a specific restriction distinct from case-by-case screening. Incoming exchange proceeds can trigger separate source-of-funds checks.
For the exchange side of these transactions, Coin Bureau compares funding routes and trading costs in its UK crypto exchanges guide.
The standard Monzo current account has no monthly fee. Trading and custody costs come from the customer's external exchange, not Monzo. Eligible UK residents must complete identity checks to open an account. Fiat deposits are covered by FSCS up to £120,000 per eligible depositor, while cryptocurrency held on Coinbase or elsewhere is outside Monzo's deposit protection.
- UK residents making modest, occasional exchange transfers.
- Coinbase users seeking an ordinary current account.
- Binance users or customers transferring over £5,000 within 30 days.
- Anyone requiring native crypto trading or custody.
- Free current account and Faster Payments.
- Explicit Coinbase and crypto payment policies.
- Fixed rolling allowance and Binance block.
- No native crypto service; individual payments may be declined.
Monzo is a sensible banking companion to selected UK exchanges. The published restrictions make it easy to assess, but frequent high-value traders will find its allowance restrictive.
5. Sygnum Bank: Best for Institutional Crypto Custody
Sygnum Bank is the institutional custody pick, combining Swiss-regulated banking with digital asset storage, trading, staking, and lending. It is not a free retail checking account and has substantial qualification requirements.
Sygnum Bank AG is licensed by FINMA. It advertises custody for more than 70 digital assets, including Bitcoin and Ethereum, and integrates its holdings with institutional trading, staking, and lending. Approved clients can access custody reporting and trading integrations suited to funds, family offices, and asset managers.
Sygnum describes customer holdings as off-balance-sheet and ring-fenced. Its controls include MPC, FIPS 140-2 Level 3 hardware, Swiss data centers, transaction screening, and assurance processes under ISAE 3000 and ISAE 3402. Staking introduces validator and slashing risks; lending adds collateral and counterparty exposure.
Eligible clients can use fiat accounts, professional trading, and approved crypto wallet transfers. Custody, trading access, and authorization controls can be integrated, reducing the need to move collateral repeatedly between third parties. External exchange and withdrawal arrangements are assessed by relationship and receiving counterparty.
Institutional pricing is generally tailored to holdings and service volume. Its March 25, 2025 private-client tariff lists 0.8% for digital-asset trading (minimum CHF 80), annual crypto custody charges of 0.6% on the first CHF 500,000, 0.5% from CHF 500,000 to CHF 5 million, and 0.4% above CHF 5 million, applied cumulatively per token and custody account. It also lists outgoing crypto transfers starting at 0.2% (minimum CHF 100) and staking fees of 20% of rewards, excluding VAT. These are published private-client charges, not universal institutional rates. Sygnum's onboarding criteria target qualified private and institutional clients, excluding ordinary retail customers and U.S. individuals or entities. Published criteria for private qualified investors include CHF 500,000 in assets alongside applicable experience requirements, while the stated initial deposit or trading-volume expectation is CHF 50,000.
Eligible fiat deposits generally receive Swiss esisuisse coverage up to CHF 100,000 per depositor. Crypto assets instead rely on their segregated custody rights and any narrowly applicable insurance arrangements.
- Funds, asset managers, and family offices.
- Professional portfolios needing integrated custody and trading.
- Small retail investors or U.S. applicants.
- Customers seeking simple published retail pricing.
- FINMA-regulated bank and custody for 70+ assets.
- Segregated assets, MPC controls, institutional integrations.
- Professional qualification and relationship minimums.
- Customized costs; crypto lacks ordinary deposit insurance.
Sygnum's custody infrastructure and professional services justify its institutional recommendation. Everyday investors generally do not need, or qualify for, this service model.
6. Bank Frick: Best for Crypto Businesses
Bank Frick is our choice for crypto companies needing conventional banking alongside regulated digital asset services. Its fee structure and compliance-led onboarding primarily suit exchanges, brokers, and professional intermediaries.
Bank Frick AG is a Liechtenstein bank supervised by the FMA. Its blockchain banking services cover business accounts, cryptocurrency custody and trading, staking, and fiat payments. Supported assets include BTC, ETH, SOL, ADA, DOT, XRP, and USDC, with staking on selected Proof-of-Stake networks.
The bank works with crypto exchanges, payments businesses, and professional investors who need both fiat operations and digital asset settlement. Its MiCA authorization, granted in January 2026, establishes it as a regulated crypto-asset service provider (CASP). Services were passported into France with an intended start date in February 2026.
Its xPULSE service enables same-currency fiat transfers within the Bank Frick network, including participating exchanges. Bank Frick's current page advertises 24/7 availability, while noting a daily processing window of up to 30 minutes. The service adds no separate xPULSE charge for existing clients. Bank Frick also launched Named VBAN on October 6, 2026, enabling participating financial intermediaries to assign named virtual IBANs to end customers and automatically allocate incoming payments. Spot FX through xPULSE runs Monday to Friday, and payments to outside banks follow their normal rails. Approved crypto deposits and withdrawals require applicable compliance evidence.
Bank Frick's published standard tariff is effective September 1, 2024, and remains linked on its current legal information page. It specifies CHF 50 per quarter for account maintenance, plus an additional CHF 500 minimum annual fee for legal entities; crypto custody 0.40% annually, minimum CHF 200; staking 15% of rewards; fiat/crypto conversion 1%, minimum CHF 250; and crypto delivery CHF 250 per position. Crypto deposits have no bank charge. Taxes, third-party fees, and negotiated terms may change actual costs.
Applicants face identity, beneficial-ownership, and source-of-funds screening. Eligible regions mainly include the EEA, Switzerland, the UK, Hong Kong, and Singapore, with other cases assessed individually. Eligible fiat deposits generally receive Liechtenstein protection up to CHF 100,000, but certain financial-services businesses and other institutional depositors are excluded; crypto custody has separate legal protections.
- Exchanges, brokers, and regulated crypto businesses.
- Companies needing multi-currency settlement and digital asset services.
- Casual retail buyers or businesses outside accepted jurisdictions.
- Customers wanting inexpensive, standardized transactions.
- MiCA-authorized CASP and crypto-focused business accounts.
- Seven-day settlement, custody, and staking.
- Higher professional fees and extensive onboarding.
- Limited suitability for everyday retail banking.
Bank Frick brings conventional banking and crypto infrastructure together for professional companies. It is a specialist service, not a low-cost alternative to an ordinary personal account.
Which Crypto-Friendly Banks Allow Transfers to Crypto Exchanges?
Native cryptocurrency support and permission to transfer money to external exchanges are different services. A bank can offer the first without guaranteeing the second, or permit exchange payments without ever taking custody of Bitcoin.
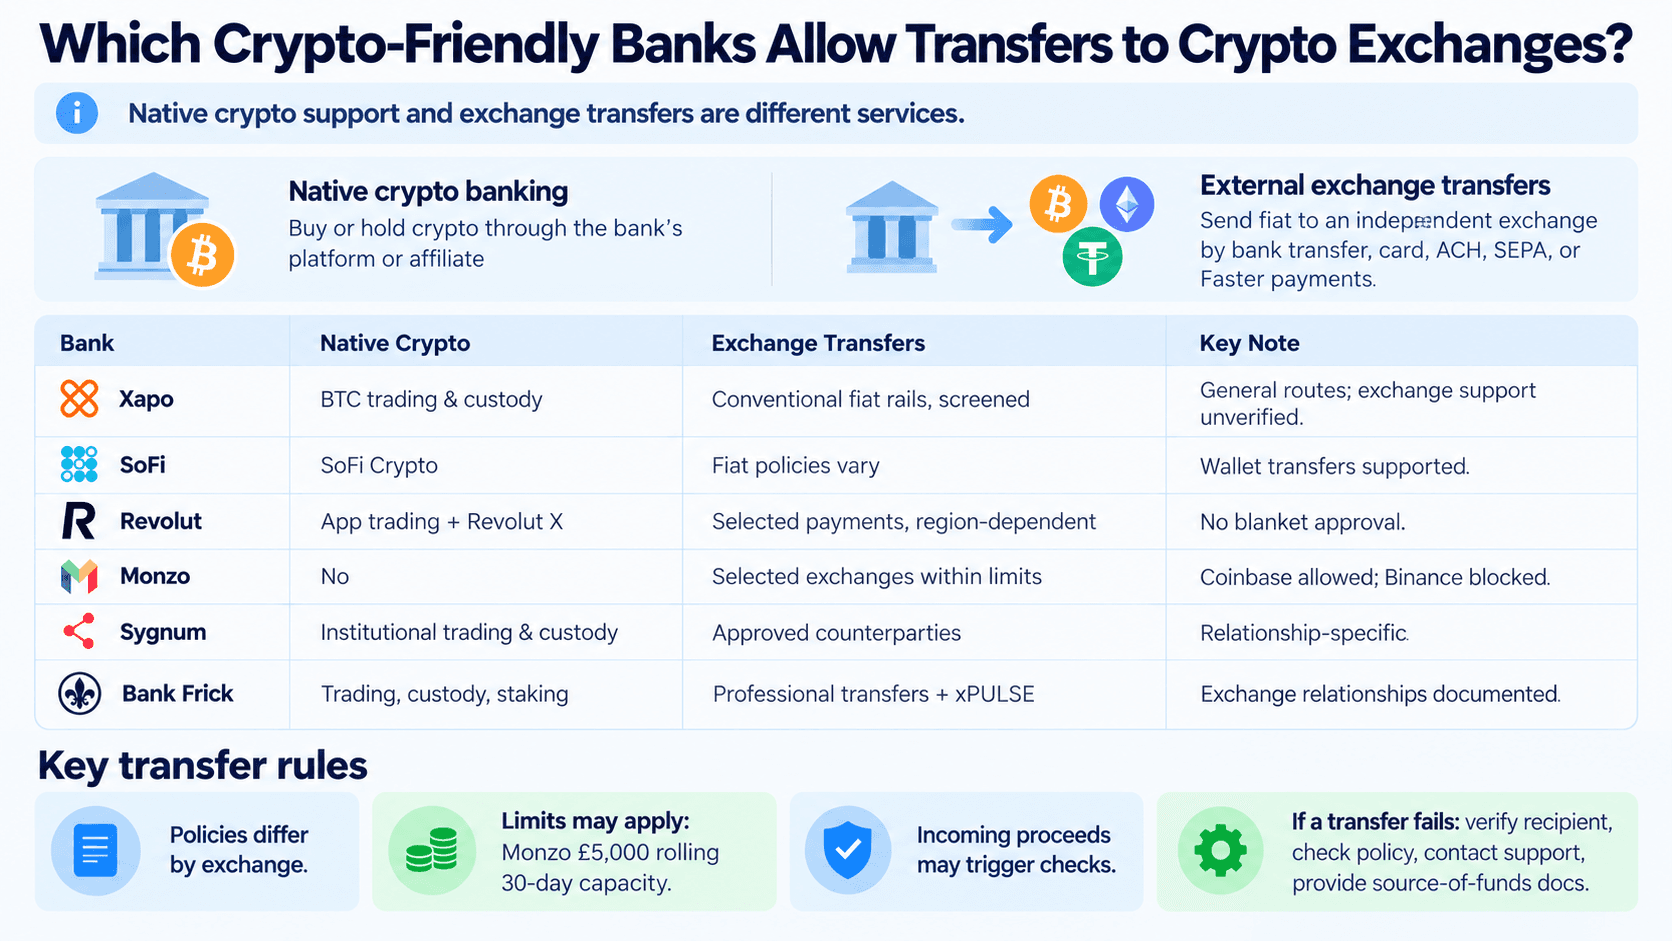 Comparing Six Crypto-Friendly Banks by Native Crypto Services, Exchange Transfer Support, and Payment Restrictions
Native Crypto Banking vs. External Exchange Transfers
An integrated model lets customers purchase or hold crypto through the bank's platform or affiliated service. An external exchange model sends fiat using bank transfer, debit card, ACH, SEPA, or Faster Payments to an independent trading venue. Whether a bank permits transfers to exchanges such as Coinbase, Kraken, or Binance depends on its payment policies, supported transfer methods, and compliance checks.
| Bank | Native Crypto | External Exchange Transfers | Public Compatibility Evidence |
|---|---|---|---|
| Xapo | BTC trading and custody | Conventional fiat rails, screened | General payment routes; individual exchange support unverified |
| SoFi | SoFi Crypto | Supported crypto transfers to outside wallets; fiat policies vary | External crypto wallets documented |
| Revolut | App trading and Revolut X | Selected payments, region-dependent | Routes documented, universal approval unverified |
| Monzo | No | Selected exchanges within limits | Coinbase allowed; Binance blocked |
| Sygnum | Institutional trading and custody | Approved counterparties | Relationship-specific |
| Bank Frick | Trading, custody, staking | Professional transfers and xPULSE | Participating exchange relationships documented |
Monzo customers buying on Coinbase move GBP to the exchange first. SoFi customers can instead purchase BTC inside SoFi Crypto and withdraw supported holdings. Revolut users may buy in-app or trade via Revolut X. None of these examples establishes blanket compatibility with every external exchange.
Crypto Payment Limits, Blocked Transfers, and Withdrawals
Banks may limit one exchange while permitting another because of fraud history, local regulation, or their own risk assessments. Transaction limits are also separate from account balances: a Monzo customer can hold £20,000 but still have only £5,000 of qualifying crypto payment capacity over a rolling 30 days.
Incoming proceeds from exchanges may undergo different checks from outgoing purchases. A large withdrawal can prompt a source-of-funds review, even if the original exchange deposit went through. Bank accounts can be temporarily restricted during compliance investigations.
If a transfer fails, confirm the beneficiary and payment reference, check the bank's published exchange policy, contact support, and provide requested exchange statements or source-of-funds documents. Where necessary, use the bank's formal complaint procedure and applicable financial ombudsman. Do not disguise crypto payments to bypass a restriction. A technically supported payment is still subject to transaction approval.
Crypto-Friendly Bank Fees, Limits, and Eligibility Compared
Crypto-friendly banks have different cost structures. Some charge annual membership fees, while others offer free accounts but apply trading commissions, spreads, or custody charges.
The cheapest option depends on whether you primarily buy cryptocurrency, transfer funds to exchanges, or hold digital assets with a bank.
Account Fees vs. Crypto Transaction Costs
The comparison below uses published pricing where available. Fees may vary by jurisdiction, account type, transaction size, and negotiated client terms.
| Bank | Recurring Account Charge | Crypto Trading Charge | Other Costs |
|---|---|---|---|
| Xapo | $1,000/year | 0.29% published BTC spread, subject to change | Faster Payments £0.15; SEPA €0.10-€0.20; FedACH deposits $0.50 + 0.10%, withdrawals $30 + 0.15%; FedWire deposits $20 + 0.10%; SWIFT and network charges |
| SoFi | No setup or monthly maintenance fee | 1.90% to 0.90%, based on monthly trading volume | Extra 2% on Apple Pay, Google Pay, and debit card purchases; variable crypto transfer fees; possible execution spreads |
| Revolut | Free Standard; UK paid plans £3.99 to £55/month | App: 1.49% Standard/Plus, 0.99% Premium/Metal, Ultra 0.49%-0% based on 30-day volume; Revolut X: 0% maker, 0.09% taker | Weekend FX charges where applicable; crypto withdrawal service fee of £1 or £3 plus network fees |
| Monzo | Free standard account | No native crypto trading | Third-party exchange trading and withdrawal fees |
| Sygnum | Relationship-specific; no fixed private-client subscription published | Private-client tariff: 0.8% digital-asset trading, minimum CHF 80 | Private-client tariff: 0.4%-0.6% tiered annual crypto custody; outgoing transfers from 0.2% (minimum CHF 100); staking 20% of rewards (excluding VAT). Institutional terms may differ |
| Bank Frick | CHF 50/quarter; additional CHF 500/year minimum for legal entities | 1% fiat/crypto conversion, minimum CHF 250 | 0.40% annual crypto custody, minimum CHF 200; 15% of staking rewards and CHF 250 crypto delivery fee |
*The figures above are published tariffs, not guaranteed transaction quotes. Revolut may apply minimum fees and exchange-rate costs. Sygnum and Bank Frick may offer negotiated pricing.
Pricing example: A $1,000 Bitcoin purchase at SoFi's entry trading tier incurs $19 in trading fees before other applicable costs; eligible Apple Pay, Google Pay, or debit card funding adds a 2% processing fee. A £1,000 taker order on Revolut X incurs £0.90 in trading fees. These examples exclude differences in execution prices and additional charges.
Minimum transaction fees can also change the economics of smaller trades, particularly at institutional banks. Xapo's membership cost is a separate fixed expense that should be considered alongside expected account usage.
Who Can Open an Account With These Banks?
Eligibility depends on residency, customer classification, and the specific crypto services offered. An approved bank account does not automatically guarantee access to every cryptocurrency product.
| Bank | Who Is Eligible? | Main Onboarding Requirements or Restrictions |
|---|---|---|
| Xapo | Individuals aged 18+ in supported jurisdictions; U.S. residents excluded | Government-issued ID, proof of address, identity verification, and compliance approval |
| SoFi | Eligible U.S. residents aged 18+ with an SSN or ITIN | Linked SoFi Checking or Savings account, identity verification, and supported residency status |
| Revolut | Adults in supported markets | Verified identity, personal details, and additional Revolut X onboarding where required |
| Monzo | UK residents, with standard personal accounts available from age 16 | Photo ID and identity verification; £5,000 rolling 30-day crypto payment allowance |
| Sygnum | Professional and institutional investors; qualified private clients | Qualified private investors generally need CHF 500,000 in assets, relevant financial knowledge, and at least CHF 50,000 in initial deposit or trading volume |
| Bank Frick | Financial intermediaries, businesses, professional clients, and selected private clients | Client due diligence, ownership documentation, beneficial-owner identification, and source-of-funds verification |
For individuals, residency and identity checks are usually the first hurdles. Businesses face additional scrutiny over corporate structure, beneficial ownership, expected transaction activity, and the origin of funds.
Institutional eligibility is more restrictive. Sygnum does not onboard ordinary retail clients, while Bank Frick primarily serves professional and intermediary relationships. Applicants should confirm their eligibility and permitted crypto activities before committing funds.
Are Crypto-Friendly Banks Safe?
Eligible fiat deposits and cryptocurrency receive different protections. A bank's license can support deposit insurance on cash while its crypto affiliate uses separate custody contracts and security controls.
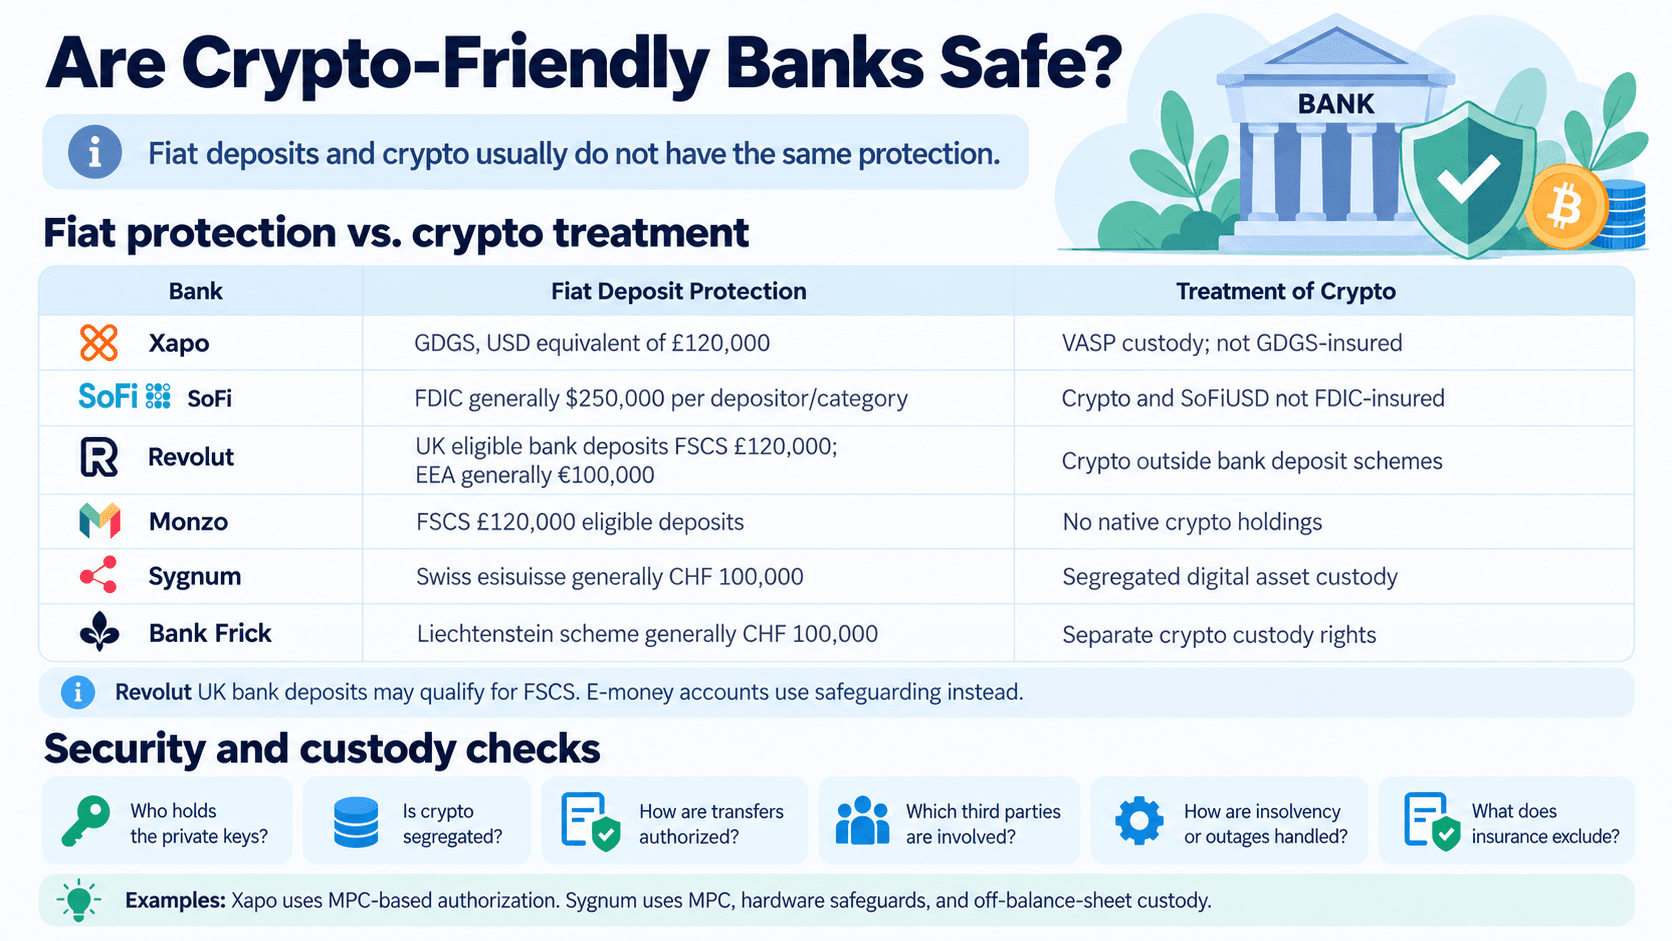 Comparing Fiat Deposit Protection, Crypto Custody Arrangements, and Security Considerations Across Six Crypto-Friendly Banks
Are Fiat Deposits and Cryptocurrency Protected Differently?
| Bank | Fiat Deposit Protection | Treatment of Crypto |
|---|---|---|
| Xapo | GDGS, USD equivalent of £120,000 | VASP custody; not GDGS-insured |
| SoFi | FDIC generally $250,000 per depositor/category | Crypto and SoFiUSD not FDIC-insured |
| Revolut | UK eligible bank deposits FSCS £120,000; EEA generally €100,000 | Crypto outside bank deposit schemes |
| Monzo | FSCS £120,000 eligible deposits | No native crypto holdings |
| Sygnum | Swiss esisuisse generally CHF 100,000 | Segregated digital asset custody |
| Bank Frick | Liechtenstein scheme generally CHF 100,000 for eligible depositors; certain financial-services businesses excluded | Separate crypto custody rights |
Deposit protection depends on the account type, legal entity, and assets held.
Revolut UK customers with e-money accounts are covered by safeguarding arrangements, not the deposit protection available to eligible UK bank accounts under the Financial Services Compensation Scheme (FSCS). Similarly, eligible SoFi checking deposits qualify for FDIC insurance within applicable limits, but Bitcoin and other cryptocurrencies held through SoFi Crypto are not insured.
What Security and Custody Risks Should You Check?
Ask who controls the private keys, whether crypto is segregated, how transfers are authorized, which third parties participate in custody, and how assets would be treated during insolvency or a service outage. Insurance can exclude theft, unauthorized transfers, market loss, and failures outside defined coverage.
Xapo uses MPC-based authorization; Sygnum combines MPC, hardware safeguards, and off-balance-sheet custody. Cold storage can reduce exposure to internet-connected systems. Those controls reduce specific risks but do not eliminate operational failure, mistaken transfers, or price volatility. Investors who prefer to hold their own keys can compare approaches in Coin Bureau's best crypto wallets guide.
How to Choose the Right Crypto-Friendly Bank
Start with the activity you need to perform and the country from which you will use the account. Do not pay for custody and settlement capabilities if occasional exchange deposits are your only requirement.
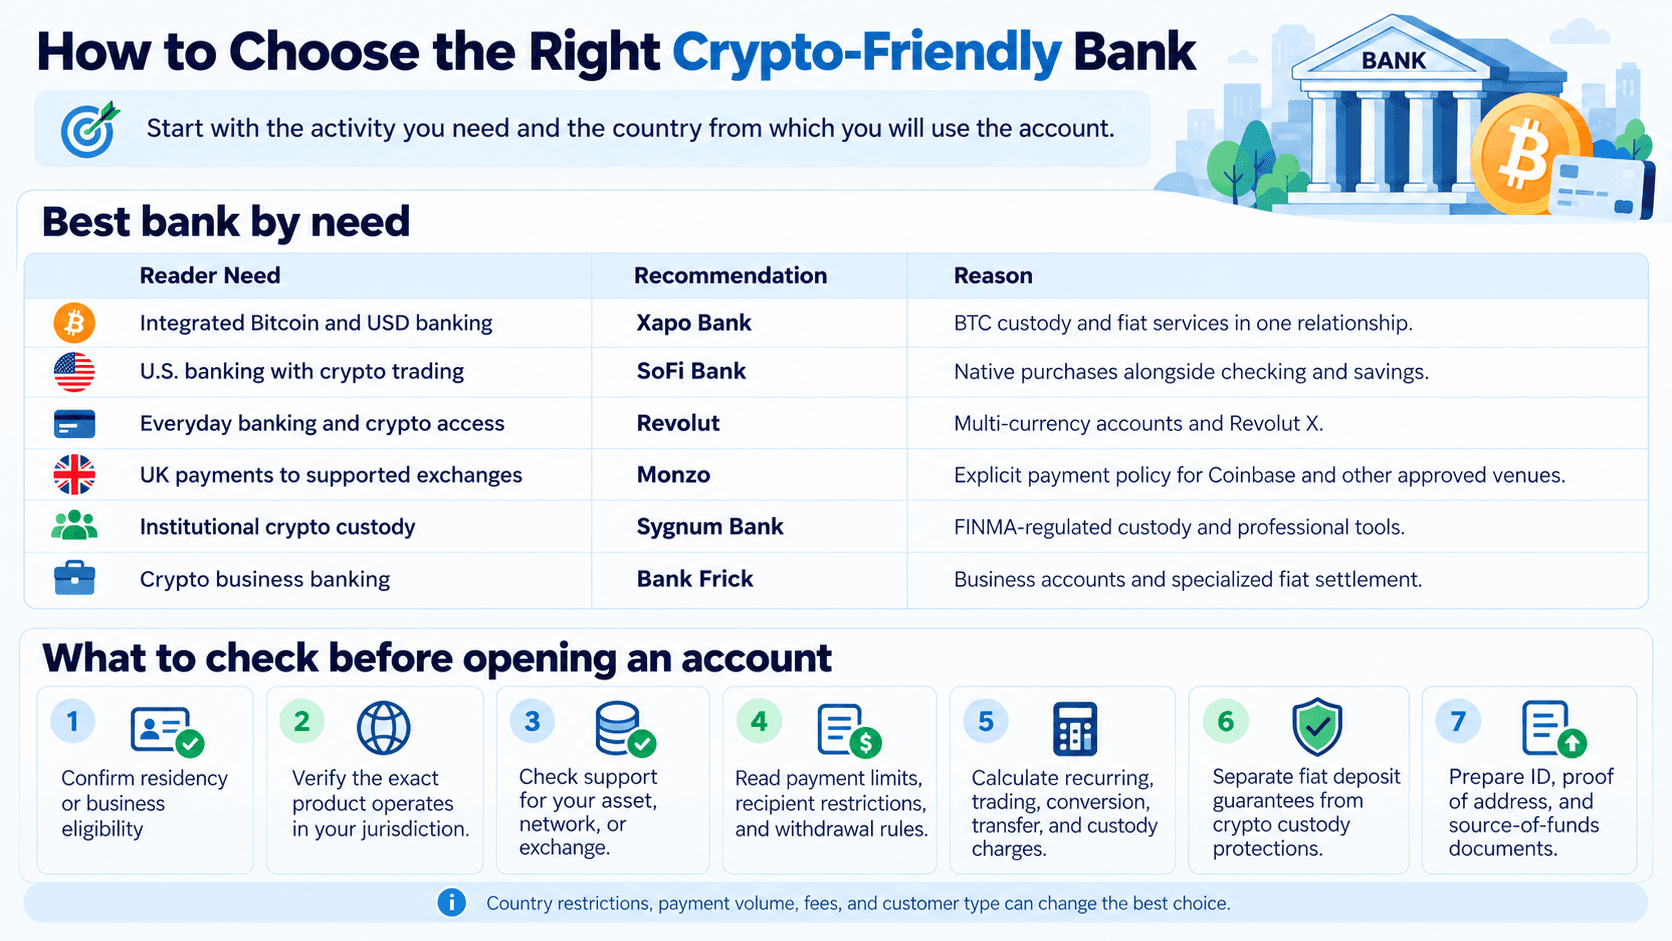 Find the Right Crypto-Friendly Bank for Your Needs and Review Key Checks Before Opening an Account
Which Bank Is Best for Your Needs?
| Reader Need | Recommendation | Reason |
|---|---|---|
| Integrated Bitcoin and USD banking | Xapo Bank | BTC custody and fiat services in one relationship |
| U.S. banking with crypto trading | SoFi Bank | Native purchases alongside checking and savings |
| Everyday banking and crypto access | Revolut | Multi-currency accounts and Revolut X |
| UK payments to supported exchanges | Monzo | Explicit payment policy for Coinbase and other approved venues |
| Institutional crypto custody | Sygnum Bank | FINMA-regulated custody and professional tools |
| Crypto business banking | Bank Frick | Business accounts and specialized fiat settlement |
Country restrictions, payment volume, fees, and customer classification can overturn an otherwise attractive ranking. The best bank for frequent exchange deposits may not be the best for holding Bitcoin or running a regulated crypto business.
What to Check Before Opening a Crypto-Friendly Bank Account
Before applying:
- Confirm residency and, if relevant, business eligibility.
- Verify that the exact banking and crypto product operates in your jurisdiction.
- Check support for your intended asset, blockchain network, or exchange.
- Read payment limits, recipient restrictions, and withdrawal rules.
- Calculate total recurring, trading, conversion, transfer, and custody charges.
- Identify fiat deposit guarantees and crypto custody protections separately.
- Prepare ID, proof of address, and requested source-of-funds documents.
Final Verdict: Which Crypto-Friendly Bank Is Best in 2026?
Xapo Bank is our overall choice because its USD account, Bitcoin custody, stablecoin funding, and trading services go beyond simply allowing exchange transfers. The $1,000 annual fee and exclusion of U.S. residents limit its appeal.
SoFi is the U.S. retail alternative; Revolut serves everyday banking and crypto needs; Monzo works for smaller UK payments to approved exchanges. Sygnum targets institutional custody, while Bank Frick serves professional crypto businesses.
Choose using verified product availability, total cost, intended crypto activity, and asset protection rather than the crypto-friendly label alone.