

Dollar-cost averaging means investing a fixed amount at predetermined intervals, regardless of price. It reduces dependence on one purchase date and makes investing more consistent, but it does not automatically improve returns or reduce a cryptocurrency's underlying risk.
Investing from each paycheck and gradually deploying money already available are different decisions. Only the second deliberately postpones investment of existing cash. A useful plan defines the amount, schedule, asset-selection rule, review process and stopping condition before purchases begin.
DCA primarily manages entry-timing risk and behavioral risk. It offers discipline and gradual exposure, with no guarantee of higher returns or protection against permanent losses.
Editor’s Note (Oct. 2, 2026): We have substantially updated and expanded this guide to provide a more rigorous look at dollar-cost averaging in crypto. The update adds original Bitcoin and Ethereum backtests, a clearer DCA vs lump-sum comparison, detailed fee and frequency analysis, and new guidance on position limits, stopping rules and self-custody. We have also updated recurring-buy information for platforms including Kraken, Coinbase, Binance and River, while adding coverage of Smart DCA and value averaging.
Dollar-Cost Averaging in Crypto: Quick Answer
Dollar-cost averaging means investing a fixed amount at predetermined intervals regardless of price. It spreads purchases across multiple entry points and can make investing more consistent, but it does not automatically improve returns or reduce the underlying risk of the cryptocurrency being purchased.
How DCA Works in Practice
-
DCA is mainly a timing and behavioral strategy It reduces dependence on a single purchase date and removes the need to make a new timing decision before every investment.
-
Paycheck DCA and spreading out existing cash are different Investing money as income becomes available does not delay capital that already exists. Gradually deploying an existing lump sum does, which introduces cash drag and opportunity cost.
-
DCA can lag lump-sum investing when prices rise Capital left uninvested misses part of the increase, while gradual deployment can soften the initial impact of a sharp decline soon after investing begins.
-
There is no universally best DCA frequency Daily, weekly, biweekly and monthly schedules can all work. The practical choice depends on cash flow, fees, spreads, minimum charges and how often the account needs to be funded.
-
DCA does not rescue a weak investment thesis Repeatedly buying at lower prices does not create value if adoption deteriorates, token supply becomes unfavorable, development stalls or the asset suffers permanent impairment.
-
Execution costs need to be measured before automating purchases Trading fees, spreads, payment charges, currency conversion and withdrawal costs can reduce the amount of crypto accumulated, particularly when purchases are small and frequent.
-
A complete DCA plan needs a stopping rule The strategy should define the contribution amount, frequency, target or duration, maximum crypto allocation, review schedule and conditions that would pause or end further purchases.
Disclaimer
This guide is for educational purposes only and is not financial advice. Cryptocurrency prices can be highly volatile, and dollar-cost averaging does not guarantee profits or protect against losses. Any investment approach should be considered alongside personal finances, investment horizon, portfolio exposure and risk tolerance.
Disclosure
Some links in this guide may be affiliate links. If you choose to use a service through these links, we may earn a commission at no additional cost to you.
DCA at a Glance
| Question | Short Answer |
|---|---|
| What is DCA? | Investing a fixed amount on a recurring schedule |
| Main advantage | Reduces dependence on one purchase date |
| Main drawback | Can lag lump sum when prices rise |
| Common frequency | Weekly or monthly |
| Best suited to | Long-term investors making regular contributions |
| Biggest mistake | Continuing after the investment thesis breaks |
| Can it guarantee profit? | No |
What Is Dollar-Cost Averaging in Crypto?
Dollar-cost averaging is a recurring investment of equal amounts at fixed intervals. Investing $100 monthly buys more cryptocurrency when its price falls and fewer units when it rises.
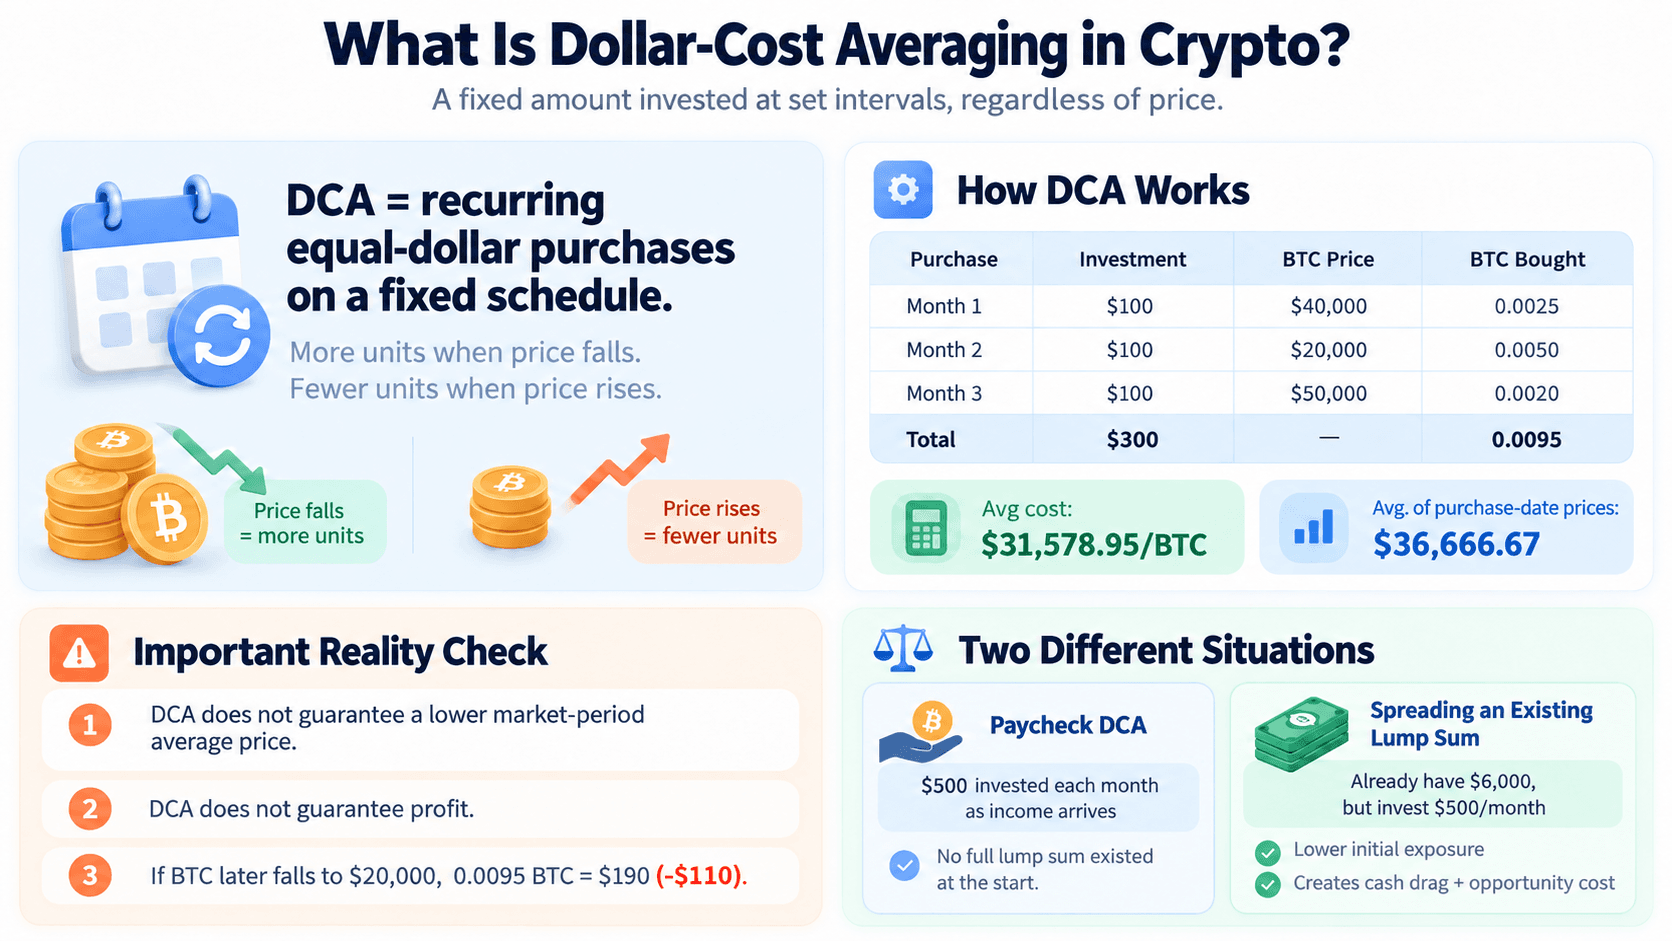 How Dca Spreads Purchases Across Prices While Reducing Dependence on a Single Entry Point
How DCA Works
Consider three hypothetical monthly Bitcoin purchases, excluding fees. Each purchase uses the same investment amount, while the market price determines how much BTC enters the account.
| Purchase | Investment | BTC Price | BTC Purchased |
|---|---|---|---|
| Month 1 | $100 | $40,000 | 0.0025 |
| Month 2 | $100 | $20,000 | 0.0050 |
| Month 3 | $100 | $50,000 | 0.0020 |
| Total | $300 | 0.0095 |
Units purchased equal the investment amount divided by the execution price. The average purchase price is total invested divided by accumulated units: $300 ÷ 0.0095 = $31,578.95 per BTC. The same calculation applies to Ethereum or another asset.
For equal-dollar purchases without fees, this average is mathematically no higher than the arithmetic average of those particular purchase-date prices, which is $36,666.67 here. That does not guarantee a price below the average across the entire market period, a lower price than an immediate purchase, or a profit.
If Bitcoin subsequently falls to $20,000, those 0.0095 BTC are worth $190, leaving a $110 loss. Volatility changes the number of units accumulated, but it does not create a recovery guarantee. Fees also increase the effective acquisition cost, while tax cost basis follows the applicable local accounting rules.
Paycheck DCA vs Spreading Out an Existing Lump Sum
Someone with $500 available from each month's income can invest it immediately. Over twelve months, they contribute $6,000, but they never had the full amount available at the beginning.
Someone already holding $6,000 who invests $500 monthly deliberately keeps part of that capital outside crypto. With the first purchase made immediately, $5,500 remains uninvested after that purchase and is deployed over the following eleven months.
This second approach reduces initial exposure to a sudden decline, but introduces the opportunity cost of delayed investment. If crypto outperforms the cash holding, the uninvested balance creates cash drag. Interest earned on cash can offset some of that difference.
Paycheck investing has no equivalent delay before income exists. Its relevant timing choice begins when the money becomes available, not months before it is earned.
DCA vs Lump Sum Investing: Which Risk Are You Trying to Reduce?
Lump-sum investing deploys available capital immediately, while DCA spreads deployment across several dates. The choice changes initial market exposure and the pressure attached to one entry price.
What DCA Gives Up in Exchange for Lower Entry-Timing Risk
Gradual deployment can soften the effect of a crash immediately after the first purchase because some capital remains in cash. Once deployment finishes, the accumulated holding remains exposed to the asset's full price fluctuations.
| Factor | DCA | Lump Sum |
|---|---|---|
| Exposure timing | Gradual | Immediate |
| Entry-point concentration | Distributed across purchases | Concentrated on one purchase |
| Cash drag | Possible during deployment | Minimal after purchase |
| Behavioral pressure | Smaller initial commitment | Larger immediate commitment |
| Steadily rising prices | Later purchases buy fewer units | Earlier full exposure is advantaged |
| Crash immediately after entry | Cash reserve softens initial loss | Full allocation absorbs the decline |
A positive expected return above cash favors earlier exposure, although expected return is uncertain and never a promise. Behavioral finance adds another consideration: an investor who would panic-sell a lump sum may find a gradual schedule easier to maintain. DCA can support discipline without making the asset itself safer.
What Historical Bitcoin Backtests Can and Cannot Tell Us
Our calculation used Coin Metrics' daily Bitcoin PriceUSD data and 97 monthly starting dates from January 2015 through January 2023. Each test began with $3,600, either invested immediately or divided into twelve $300 purchases on consecutive monthly anniversaries, beginning on the start date.
Both portfolios were valued 36 months after their start. Uninvested cash earned zero interest, while fees, spreads and taxes were excluded. Maximum drawdown measures the largest daily peak-to-trough decline in the whole portfolio, including uninvested cash.
| Result Across 97 Starting Dates | Monthly DCA | Lump Sum |
|---|---|---|
| Higher ending value | 32 periods, 32.99% | 65 periods, 67.01% |
| Median maximum drawdown | 70.17% | 76.67% |
| Worst maximum drawdown | 83.78% | 83.78% |
| Highest ending value | $185,962.78 | $153,991.03 |
| Start producing highest ending value | January 2015 | January 2015 |
| Lowest ending value | $3,388.92 | $3,617.31 |
| Start producing lowest ending value | February 2021 | May 2021 |
The historical gains reflect Bitcoin's unusually strong early growth, while the drawdowns show that DCA did not remove severe market risk. The starting periods overlap and are not 97 independent experiments. Different deployment lengths, cash yields, holding periods and prices would change the results.
Break-even timing also varied. For the May 2021 start, DCA was above its $3,600 principal when its final installment was invested on April 1, 2022. The lump-sum portfolio first regained that principal after the deployment period on February 28, 2024. Crossing break-even did not prevent later losses.
These calculations compare two ways of deploying existing money. They do not test investing future paychecks, and historical Bitcoin performance does not establish future returns or results for altcoins.
When a Hybrid Approach Can Make Sense
A hybrid plan invests part immediately and schedules the remainder over a defined period. For example, a hypothetical $6,000 allocation could place $3,000 immediately and deploy the other $3,000 in six monthly installments of $500.
That produces more initial exposure than full DCA and less than a lump sum. Its purpose is a manageable commitment with a deadline, rather than repeatedly extending deployment while waiting for a more comfortable price.
How to Build a Crypto DCA Strategy
A complete plan follows amount → frequency → duration or target → automation → review. Its budget and exposure limits remain connected to the investor's wider finances.
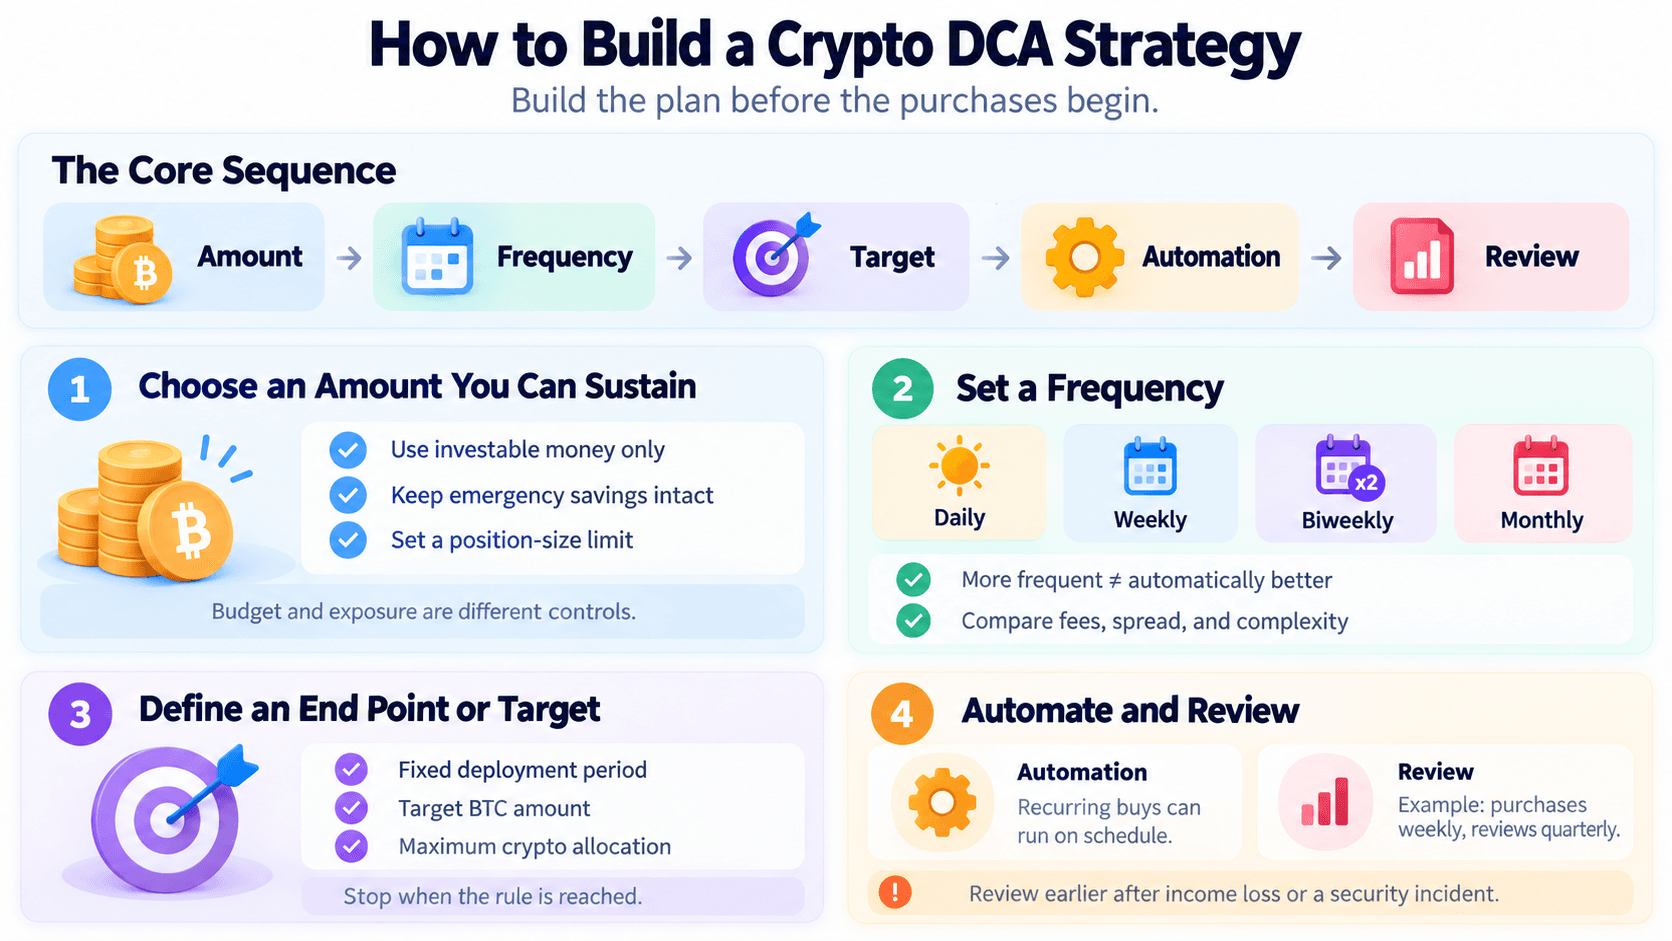 A Practical Dca Framework Built Around Budget, Frequency, Targets, Automation, and Regular Portfolio Reviews
Choose an Amount You Can Sustain
The contribution comes from investable money after essential expenses, near-term commitments and emergency savings. Cash flow and income frequency determine whether a recurring contribution remains affordable when markets are uncomfortable.
A position-size limit prevents a modest recurring buy from becoming an oversized allocation. The limit applies to the market value of all crypto exposure, including holdings elsewhere, rather than only the amount deposited into one exchange.
A monthly budget and a maximum portfolio allocation serve different purposes: one controls spending, while the other controls concentration. Our guide to building a crypto portfolio explains how allocation, diversification and entry rules work together.
Set a Frequency
Daily, weekly, biweekly and monthly purchases are common options. More frequent DCA does not automatically produce better returns. It changes execution dates, transaction counts and the time cash remains uninvested.
The schedule needs to match available funding and the platform's pricing. Small daily orders can be impractical where minimum charges apply, while a monthly payday contribution may support a simple monthly purchase without extra transfers.
Spread, payment costs and operational complexity belong in this choice. A recurring instruction also needs an adequately funded account, especially when a weekly schedule creates five purchases in some months.
Define an End Point or Target Allocation
Income-funded accumulation can continue while the investment horizon, budget and allocation remain appropriate. A fixed lump sum instead has a finite deployment amount and completion date.
Other stopping rules include a six-month purchase period, a specified BTC balance or a maximum crypto allocation. A hypothetical 10% allocation limit refers to current portfolio value, so price gains can trigger the limit before the planned contributions finish.
A quantity target alone does not control financial exposure because the value of that quantity changes. A plan can therefore combine an accumulation goal with a portfolio ceiling and stop new purchases when either is reached.
Decide How Often the Strategy Will Be Reviewed
The purchase schedule and strategy review are separate processes. Weekly purchases can run automatically while quarterly reviews assess affordability, allocation, asset fundamentals and execution costs.
A serious security incident or loss of income can justify an earlier review. Ordinary daily price movements do not require rewriting the policy, but automation also cannot determine whether the original investment thesis remains valid.
How Often Should You DCA Into Crypto?
There is no universally optimal DCA frequency. Once contributions are reasonably frequent, fees and cash-flow timing can outweigh small differences in historical entry prices.
Daily vs Weekly vs Monthly DCA
A separate calculation held the budget at $3,600 per asset for calendar year 2025, using the same Bitcoin series and Coin Metrics' Ethereum PriceUSD data. Daily purchases divided the budget across 365 dates, weekly purchases used 52 Tuesdays from January 7, and monthly purchases used the first of each month.
Each purchase was the budget divided by the transaction count, with units calculated at that date's reference price. Holdings were valued on December 31. The final column deducts a hypothetical 1% fee from every contribution, leaving 99% invested.
| Asset and Schedule | Buys | Units Accumulated | Average Cost | Ending Value, No Fees | Ending Value, 1% Fee |
|---|---|---|---|---|---|
| BTC daily | 365 | 0.03591226 BTC | $100,244.32 | $3,142.93 | $3,111.50 |
| BTC weekly | 52 | 0.03595830 BTC | $100,115.96 | $3,146.96 | $3,115.49 |
| BTC monthly | 12 | 0.03609279 BTC | $99,742.92 | $3,158.73 | $3,127.14 |
| ETH daily | 365 | 1.28162714 ETH | $2,808.93 | $3,804.03 | $3,765.99 |
| ETH weekly | 52 | 1.28718678 ETH | $2,796.80 | $3,820.54 | $3,782.33 |
| ETH monthly | 12 | 1.29452029 ETH | $2,780.95 | $3,842.30 | $3,803.88 |
Units and average costs shown are before fees. The reference prices on December 31 were $87,516.98 for BTC and $2,968.13 for ETH. Actual execution prices and minimum order sizes would differ.
Monthly purchases finished ahead in this sample, by $15.80 over daily purchases for BTC and $38.27 for ETH. One year does not establish a durable ranking, and changing the weekly weekday or monthly date changes the result. The comparison assumes the required cash is available at each purchase, without modeling payday constraints or interest.
Should You Try to Find the Best Day to Buy?
A weekday that performed well historically may lose its advantage in another market regime. Selecting the best day after inspecting the results also benefits from hindsight that a live investor would not have had.
Small entry-price differences rarely justify delaying available contributions indefinitely or introducing expensive transactions. A schedule that fits payday and executes consistently has a clearer practical basis than treating one weekday as a persistent bargain.
What Does Crypto DCA Really Cost?
All-in execution cost is the gap between cash committed and the market value of crypto received, including explicit charges and price markup. Withdrawal costs add a further expense when holdings leave the platform.
Trading Fees Are Only Part of the Cost
Maker fees apply to eligible orders adding order-book liquidity, while taker fees apply to orders removing it. A recurring-buy product can use a separate price and fee model, so its cost cannot be inferred from the exchange's advertised trading tier.
| Cost Component | How It Affects DCA |
|---|---|
| Trading fee | Deducted from the order or charged separately |
| Spread or execution markup | Reduces units received at the quoted price |
| Card or payment fee | Adds funding costs before or alongside the purchase |
| Currency conversion | Adds friction when funding and purchase currencies differ |
| Withdrawal or network charge | Reduces the amount arriving in self-custody |
As of Oct. 2, 2026, Kraken's Instant Buy and recurring trades carry a 1% trading fee, with a spread and possible payment charges. Eligible Kraken+ trades can receive a trading-fee waiver within the $10,000 monthly allowance, but spreads and card-processing charges still apply.
Coinbase calculates simple-buy fees when an order is placed, with the amount influenced by factors including payment method, order size, market conditions, jurisdiction and asset. Its official pricing disclosure also states that simple buy and sell orders include a spread in the quoted price. There is therefore no single universal recurring-buy percentage that can be inferred from its advanced-trading fee schedule.
For an independent illustration, suppose a $100 budget incurs a $1 fee and the execution price is 0.5% above a reference market price. The remaining $99 buys crypto worth $99 ÷ 1.005 = $98.51 at that reference price. The immediate shortfall is $1.49, or approximately 149 basis points. One basis point is 0.01 percentage point.
This excludes funding and withdrawal charges. A platform quoting zero trading fees can still have execution costs, and subscription fees need to be included when evaluating a paid fee-waiver plan.
When Buying More Often Becomes Less Efficient
Consider a hypothetical $3,600 annual budget with costs deducted from it. A pure 1% charge costs $36 regardless of frequency, assuming no minimums or rounding effects. Adding a fixed $0.50 charge per purchase changes the comparison substantially.
| Schedule | Purchases | Cost at 1% Only | Cost at 1% Plus $0.50 per Buy | Budget Remaining to Invest |
|---|---|---|---|---|
| Daily | 365 | $36.00 | $218.50 | $3,381.50 |
| Weekly | 52 | $36.00 | $62.00 | $3,538.00 |
| Monthly | 12 | $36.00 | $42.00 | $3,558.00 |
These are illustrative charges, not a named platform's tariff. More transactions become less efficient when fixed costs, minimum fees or repeated withdrawals outweigh any execution benefit. Percentage-only pricing does not create that penalty merely because the budget is split more often.
Which Cryptocurrencies Are Suitable for DCA?
An asset's suitability depends on its investment thesis, liquidity, supply structure and security. Bitcoin and Ethereum have different economic roles, and neither becomes suitable for every investor simply because recurring purchases are available.
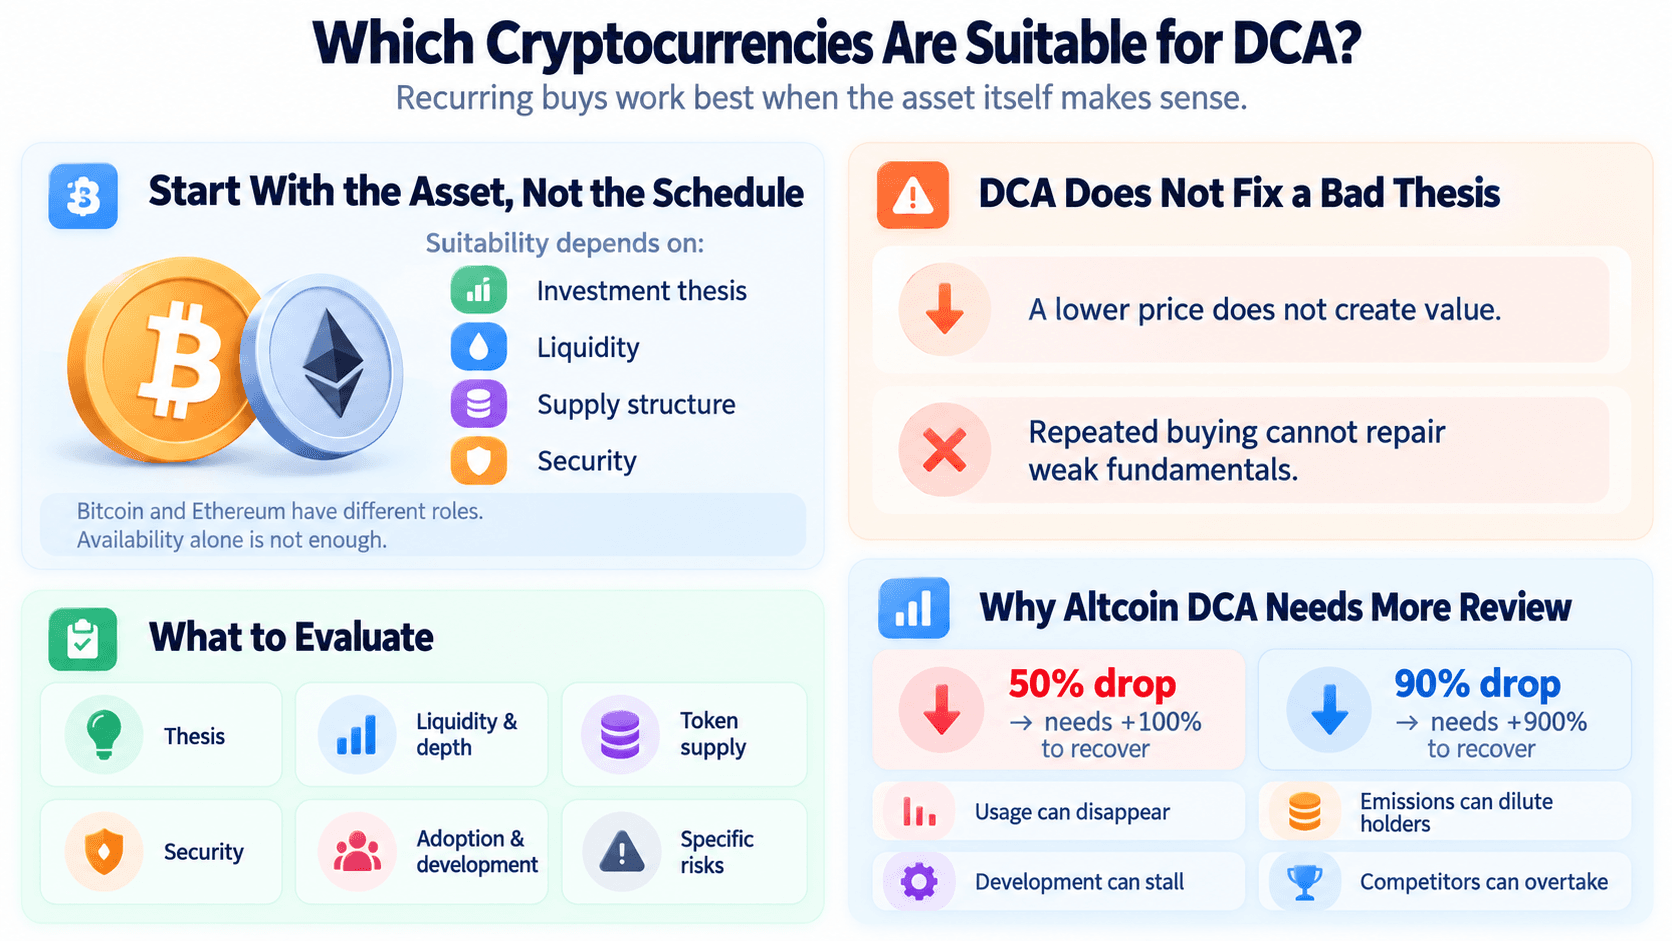 Dca Works Best When the Asset Has Strong Fundamentals, Liquidity, Security, and a Durable Investment Thesis
DCA Does Not Fix a Bad Investment Thesis
A falling price can reflect temporary selling pressure or lasting damage to an asset's prospects. Purchasing more units does not distinguish between those possibilities.
The investment thesis needs a reason for long-term demand and a credible relationship between network success and token ownership. A price below its previous peak, a large market capitalization or a lower average entry cost does not supply that reasoning.
What to Evaluate Before DCA-ing Into an Asset
A compact assessment covers the asset's economics alongside the ability to buy, hold and eventually sell it.
| Area | Evidence to Examine |
|---|---|
| Investment thesis | Why demand could persist and how the token participates |
| Liquidity and market depth | Executable orders near market price, not reported volume alone |
| Token supply | Circulating supply, inflation, emissions and scheduled unlocks |
| Security | Network resilience, contract controls and relevant custody or bridge dependencies |
| Adoption and development | Sustained usage, maintained software and delivery of useful features |
| Specific risks | Regulatory restrictions, governance changes and competitive threats |
Supply growth can dilute holders even when a network attracts users. Thin liquidity can also make small recurring orders expensive and larger exits difficult. The purchase mechanism cannot compensate for either weakness.
Why Altcoin DCA Requires More Review
Permanent impairment occurs when the original economic case deteriorates enough that a prior price may never return. Usage can disappear, emissions can overwhelm demand, development can stop, or competitors can replace the service.
A hypothetical 50% decline requires a 100% gain to recover, while a 90% decline requires a 900% gain. Those calculations apply to Bitcoin as well as altcoins, and neither asset category has a guaranteed recovery.
Smaller projects can change quickly because their products, funding and token economics are less established. Repeated accumulation therefore requires continued evidence that the original thesis survives, rather than confidence based solely on a lower price.
Fixed DCA, Smart DCA and Value Averaging
These approaches automate different decisions. Fixed DCA controls the contribution, dynamic DCA changes it using signals, and value averaging targets a portfolio-value path.
| Approach | What Stays Fixed | What Changes | Main Constraint |
|---|---|---|---|
| Fixed DCA | Contribution and schedule | Units purchased | No response to changing fundamentals |
| Smart or dynamic DCA | Predefined adjustment rules | Contribution size | Signal quality and extra cash requirements |
| Value averaging | Target portfolio-value path | Required contribution, potentially withdrawals | Large funding demands after losses |
Fixed DCA
The same amount is invested on the same schedule regardless of price. Falling prices increase the units bought, while rising prices reduce them, without requiring a forecast before each transaction.
This baseline is easy to budget and evaluate. Any variable-contribution strategy needs comparison against it using the same available capital, fees and time period. Investing more money is not itself evidence of superior returns.
Smart or Dynamic DCA
Smart DCA changes purchase amounts according to predefined conditions. The label has no universal definition, and the rules introduce a market-timing element even when execution is automatic.
Binance introduced sentiment-based Smart DCA on July 2, 2026. Eligible Binance Convert Recurring plans can adjust contributions when CoinMarketCap's Fear & Greed Index enters user-defined ranges. The sentiment reading is an input to the rule, not evidence that prices will subsequently recover.
River, which Coin Bureau also covers in its low-fee crypto exchange guide, offers Supercharged Recurring Buys. The feature can increase scheduled Bitcoin purchases by 25%, 50%, 100% or 200% when BTC is approximately 1% or more below the relevant moving average. Hourly, daily and weekly schedules use a seven-day moving average, biweekly schedules use fourteen days, and monthly schedules use thirty days.
Both designs require enough available cash for larger purchases and an overall allocation ceiling. Repeated decline-triggered buying can consume a reserve quickly during a prolonged bear market.
Value Averaging
Value averaging sets a desired portfolio value at each review date, then adjusts the contribution to close the gap. If a hypothetical portfolio should reach $2,000 but is worth $1,600, the required contribution is $400.
If it is worth only $1,000, the same target requires $1,000 of new money. Strong performance can reduce contributions or call for withdrawals under the chosen rule. Its funding needs are therefore less predictable than fixed DCA, especially during sustained losses.
When DCA Can Fail
A consistent purchase process can still produce a poor investment outcome. These failure modes concern the asset, deployment path, costs and oversight.
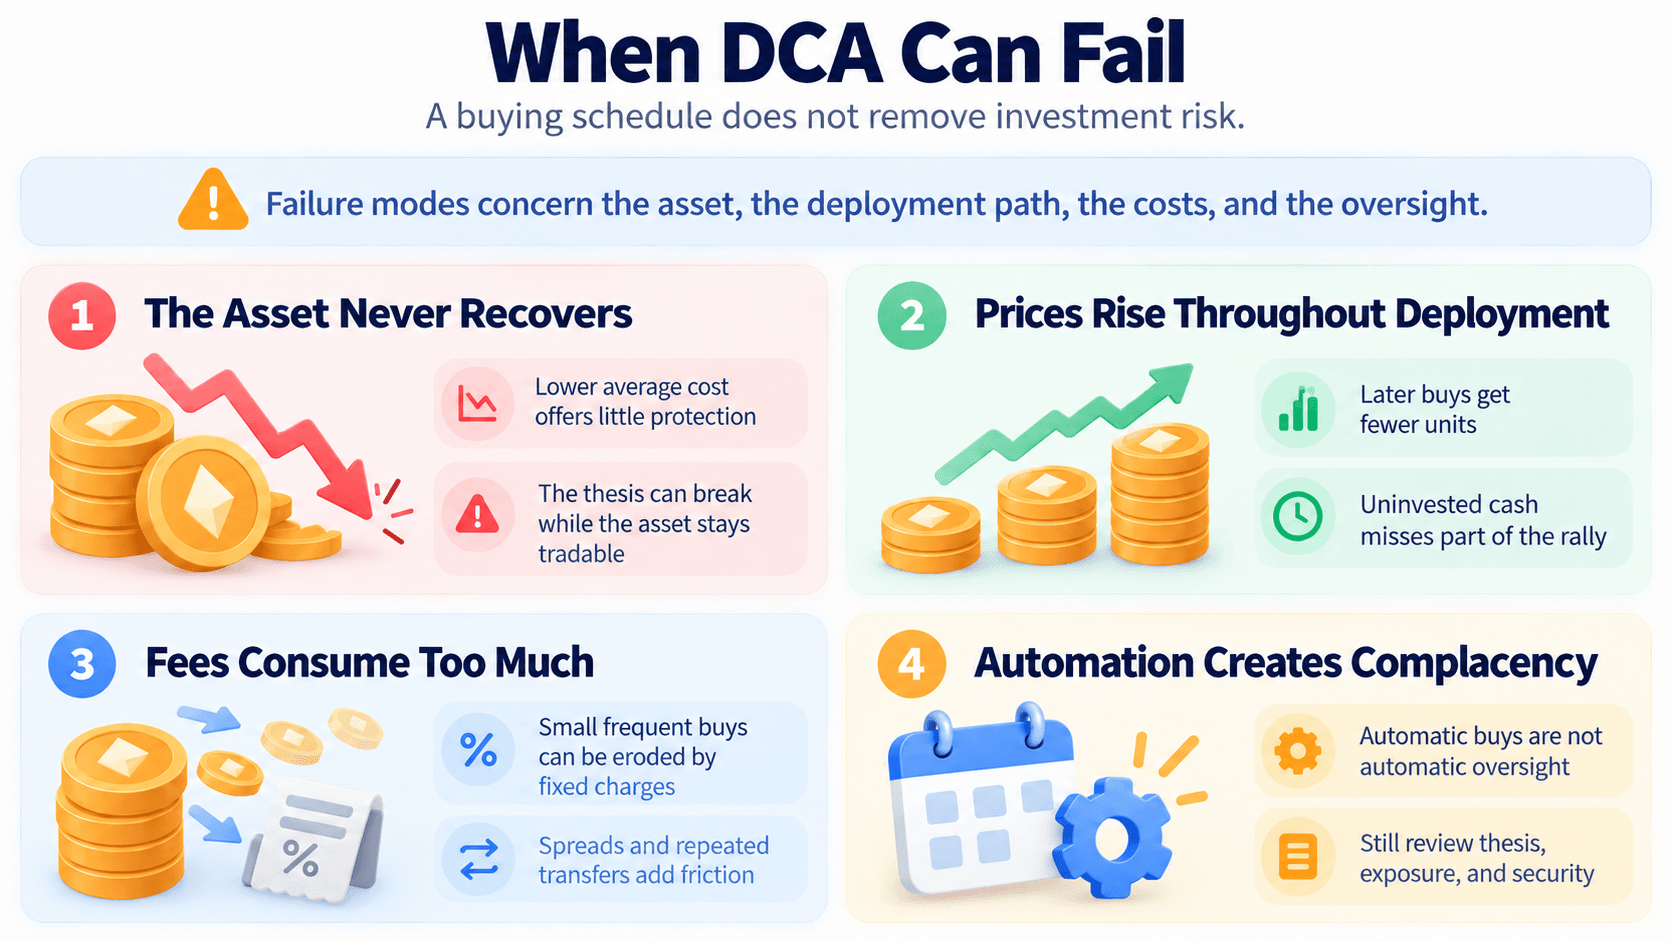 Lower Prices, Rising Fees, Broken Theses, and complacent automation can all undermine a Dca Strategy
The Asset Never Recovers
An asset can lose its users, security or economic purpose while remaining tradable. Automated purchases may continue accumulating units long after the reason for owning them has disappeared.
A lower average cost offers little protection against permanent loss. The relevant comparison is between the asset's current prospects and the original thesis, rather than its current price and a former high.
Prices Rise Throughout the Deployment Period
When an asset rises steadily, later installments buy fewer units than immediate deployment would have acquired. Uninvested capital misses part of the bull market, leaving DCA behind the lump-sum alternative.
This opportunity cost applies to money already available. Future income cannot participate in earlier gains before it is earned, so the same criticism does not apply to those unavailable funds.
Fees Consume Too Much of Small Purchases
A minimum transaction fee or costly funding method can take a disproportionate share of a small order. Repeated transfers can then add another layer of charges after the purchase.
The earlier cost calculation shows why a convenient daily schedule can deliver less crypto than a less frequent plan with the same cash budget. Affordability includes execution costs as well as the advertised contribution.
Automation Creates Complacency
Automated purchases can continue after a portfolio becomes overexposed, income falls or a platform changes its terms. A successful recurring debit only confirms that the instruction ran.
Portfolio reviews, thesis reassessment, exposure limits and account-security oversight remain separate responsibilities. Automation removes repetitive purchase decisions while leaving those judgments with the investor.
When Should You Pause or Stop DCA?
A pause can reflect changed finances, while a stop can reflect a completed goal or broken investment thesis. A market decline alone does not identify which condition applies.
Stop Because Your Target Has Been Reached
A specified BTC balance, maximum crypto allocation or completed deployment period provides a clear stopping condition. Continuing beyond it creates a different plan with greater exposure.
Reaching the target does not necessarily require selling. The accumulated holding can remain invested while new contributions move elsewhere, subject to the investor's horizon and risk tolerance.
Pause Because Your Financial Situation Changed
A depleted emergency fund, lower income, higher-priority debt or larger short-term cash needs can make the original contribution unaffordable. Pausing preserves flexibility without requiring a prediction about crypto prices.
The revised budget needs to support essential spending and liquidity first. Resuming purchases becomes a fresh affordability decision rather than an obligation to replace every missed installment.
Stop Because the Investment Thesis Changed
A thesis review looks for evidence beyond price movement. Potential reasons to stop further accumulation include:
- Protocol security deteriorates or critical vulnerabilities remain unresolved.
- Token economics change materially through dilution or weaker utility.
- Development stalls and essential maintenance stops.
- Expected adoption fails to emerge or existing usage declines persistently.
- Regulatory changes restrict access or alter the investment's legal structure.
- Competitors materially weaken the project's position.
These conditions are especially relevant to altcoins with evolving products and concentrated control. Suspending new purchases and deciding what to do with existing holdings are related but separate decisions.
Rebalance Instead of Automatically Selling
New contributions can be redirected toward underweight assets when crypto exceeds its target allocation. This can gradually restore diversification without immediately selling the overweight position.
That approach may be too slow after a large price move or when new contributions are small relative to the portfolio. Rebalancing decisions still depend on the size of the excess exposure, liquidity needs and financial goals.
How to Automate Crypto DCA Safely
Recurring-buy services automate purchases through an exchange or broker, using an account balance or supported funding method. Their schedules, minimums, prices and withdrawal rules differ.
Exchange Recurring Buys
The setup typically specifies an asset, amount, purchase interval and funding source. Bank-transfer timing, insufficient balances and payment failures can interrupt execution, so a schedule does not guarantee that every order completes.
Coinbase supports recurring buys and executes an initial purchase when a recurring plan is created. Kraken offers daily, weekly, biweekly and monthly recurring orders, with the feature separate from Kraken Pro. Binance Convert Recurring supports fixed plans and eligible Smart DCA configurations, while River focuses on Bitcoin.
River's standard recurring-buy fees fall to 0% after the initial fee period. Daily and hourly plans become fee-free from the eighth day, while weekly and other less frequent schedules become fee-free from the second order. River separately discloses that buy prices include a spread, which typically sits around 0.25% but can change with market conditions. These are product examples rather than platform rankings, and availability and funding options vary by jurisdiction.
A workable setup has an affordable minimum purchase, acceptable all-in pricing, a supported funding route and a clear cancellation process. Account authentication, purchase notifications and review of completed orders help detect failed instructions or unauthorized activity without requiring constant price monitoring.
What Happens After the Purchase?
Keeping assets on an exchange leaves private-key control with the custodian and retains exposure to withdrawal restrictions, account compromise and platform failure. Self-custody transfers control to the owner along with responsibility for recovery backups and transaction accuracy.
Some investors transfer after reaching a balance threshold rather than after every purchase. That limits repeated withdrawal charges, but leaves a larger balance with the exchange between transfers.
The threshold can combine a maximum custodial balance with an acceptable withdrawal-cost percentage. Our beginner crypto wallet guide explains the setup and recovery differences between software and hardware wallets.
Crypto DCA Example: Building a Complete Plan
Consider an investor with $400 a month available for long-term Bitcoin accumulation. The figures below illustrate a policy rather than a recommended contribution or allocation.
A $100 weekly purchase would require $5,200 over 52 weeks, exceeding the $4,800 annual budget. Four scheduled $100 purchases per month preserve the budget. That is not the same as purchasing every seven days.
| Variable | Example Rule |
|---|---|
| Asset | BTC, held without leverage |
| Investment horizon | Five years or longer, subject to thesis review |
| Monthly budget | $400, including purchase fees |
| Purchase schedule | $100 on the 1st, 8th, 15th and 22nd |
| Maximum crypto allocation | 10% of the investable portfolio's current value |
| Automation | Use supported scheduled orders or calendar reminders where necessary |
| Review | Quarterly, with earlier review after major financial or security changes |
| Custody | Transfer near $1,000 accumulated if withdrawal cost is no more than 0.5%; otherwise reassess |
| Fee rule | Review execution method or cadence if purchase costs exceed 1% |
| Stop rule | Target allocation reached, deployment policy changed or thesis invalidated |
A sharp Bitcoin rise can push the allocation to its ceiling before the next review. Further purchases then pause rather than increasing automatically because performance looks strong.
A sharp fall leaves the purchase amount unchanged while the thesis and budget remain intact. It does not authorize extra buying beyond the allocation policy, and deteriorating fundamentals trigger reassessment.
At the target allocation, new contributions can move to other portfolio assets. If income declines, the budget is reduced or paused before the next scheduled order. The policy coordinates buying, costs and custody without requiring a short-term price forecast.
Is Dollar-Cost Averaging a Good Crypto Strategy?
DCA can suit long-term cryptocurrency investors who want regular exposure without making every purchase depend on market timing. It provides a consistent process and spreads entry dates, while leaving asset risk, fees and portfolio concentration to be managed separately.
For income-funded investing, it offers a straightforward contribution schedule. For an existing lump sum, it exchanges immediate exposure for gradual deployment and possible cash drag. A shorter schedule or hybrid approach can provide a middle ground for investors who do not want either immediate full deployment or a long DCA period.
The strategy is poorly suited to money needed soon or an asset without a defensible investment thesis. A useful DCA plan has an affordable budget, a defined allocation and a stopping rule, including a condition for ending purchases when the original case for ownership no longer holds.