
Cashing out cryptocurrency means converting digital assets such as Bitcoin, Ethereum, or stablecoins into traditional money that you can withdraw to a bank account or spend. While the process is relatively straightforward, fees, withdrawal methods, processing times, and regional restrictions can make a significant difference.
This guide explains how to cash out crypto step by step, compares exchanges, wallet-integrated off-ramps, P2P platforms, and crypto cards, and covers transaction fees, withdrawal delays, security risks, and tax implications.
Editor's Note (Oct. 16, 2026): We fully updated this guide in October 2026 to reflect the latest methods for cashing out cryptocurrency. The revised article expands coverage of centralized exchanges, wallet-integrated off-ramps, P2P trading, and crypto cards, with new step-by-step instructions for withdrawing crypto to a bank account or converting assets held in self-custody wallets. We also added detailed comparisons of fees and processing times, troubleshooting guidance for failed or delayed withdrawals, enhanced security recommendations, and updated information on KYC requirements, stablecoin restrictions, and crypto tax reporting.
Quick Answer: How to Cash Out Crypto
To cash out cryptocurrency, sell your crypto for fiat through a supported exchange or off-ramp, then withdraw the proceeds to your bank account or another eligible payment method. The process involves five main steps.
How to Cash Out Crypto in 5 Steps
-
Choose an exchange or off-ramp Find a provider that supports your cryptocurrency, country, fiat currency, and preferred payout method.
-
Complete identity verification Fulfill the required Know Your Customer (KYC) checks and link an eligible bank account or another supported withdrawal destination.
-
Transfer your cryptocurrency If your assets are held in an external wallet, send them to the provider using the correct cryptocurrency deposit address and blockchain network.
-
Sell your crypto for fiat Convert your cryptocurrency into USD, EUR, GBP, or another supported currency after reviewing the quoted price and transaction fees.
-
Withdraw your money Transfer the available fiat balance to your bank account or supported payment service and confirm that the funds have arrived.
Using a wallet-integrated off-ramp? Some providers combine conversion and payout into one process. The provider receives your cryptocurrency, processes the sale, and arranges the fiat payment directly, without requiring a separate exchange trading balance.
Disclaimer
Cryptocurrency cash-outs involve transaction fees, price volatility, potential withdrawal delays, and provider-specific restrictions. Selling crypto may also create taxable gains or losses depending on your jurisdiction. Verify provider eligibility, transfer details, and final payout amounts before proceeding. This guide is for educational purposes only and is not financial, investment, tax, or legal advice.
Disclosure
Some links in this guide may be affiliate links. If you choose to use a service through these links, we may earn a commission at no additional cost to you.
What Does It Mean to Cash Out Crypto?
Cashing out crypto means converting cryptocurrency into fiat currency that can be withdrawn or spent through conventional payment systems. The process generally involves a cryptocurrency sale followed by a fiat withdrawal, although integrated off-ramp providers may handle both transactions together.
For example, an investor holding Bitcoin might sell BTC for U.S. dollars on an exchange and transfer the resulting cash balance to a bank account. Someone holding Ethereum could follow the same process using an ETH/USD or ETH/EUR market, provided the exchange supports the relevant currency and banking method.
The sale determines how much fiat the investor receives, while the subsequent withdrawal determines how that money reaches them.
Selling Crypto vs. Withdrawing Money
Selling cryptocurrency converts one asset into another, while withdrawing fiat transfers an available cash balance to an external payment destination.
A cryptocurrency sale can therefore be completed without any money having reached your bank. The proceeds may remain inside an exchange account until you initiate a supported fiat withdrawal.
The standard process follows this sequence:
Crypto Wallet or Exchange Balance → Sell Crypto → Fiat Balance → Bank Account or Supported Payout Method
Several balances may appear along the way, each representing something different.
| Balance Type | What It Represents | Bank Withdrawal Availability |
|---|---|---|
| Cryptocurrency balance | BTC, ETH, or another digital asset | Generally requires conversion into fiat |
| Stablecoin balance | Digital tokens such as USDT or USDC | Requires a compatible conversion or redemption route |
| Exchange fiat balance | Traditional currency credited after a sale | Subject to withdrawal eligibility and restrictions |
| Available fiat balance | Cash that has cleared applicable withdrawal restrictions | Can be sent through a supported payout method |
The difference becomes clearer when stablecoins enter the process.
Exchanging $1,000 worth of BTC for approximately 1,000 USDC may reduce exposure to Bitcoin's price movements, but the proceeds remain in cryptocurrency form. The user still needs a provider capable of converting or redeeming that USDC into traditional currency.
Likewise, a cash balance displayed on a cryptocurrency exchange may be subject to settlement holds or account restrictions before it becomes withdrawable.
Integrated off-ramps simplify these stages by collecting cryptocurrency and arranging a fiat payout within one service. The distinction between conversion and settlement still applies, even when the user completes everything through a single interface.
What Are the Best Ways to Cash Out Crypto?
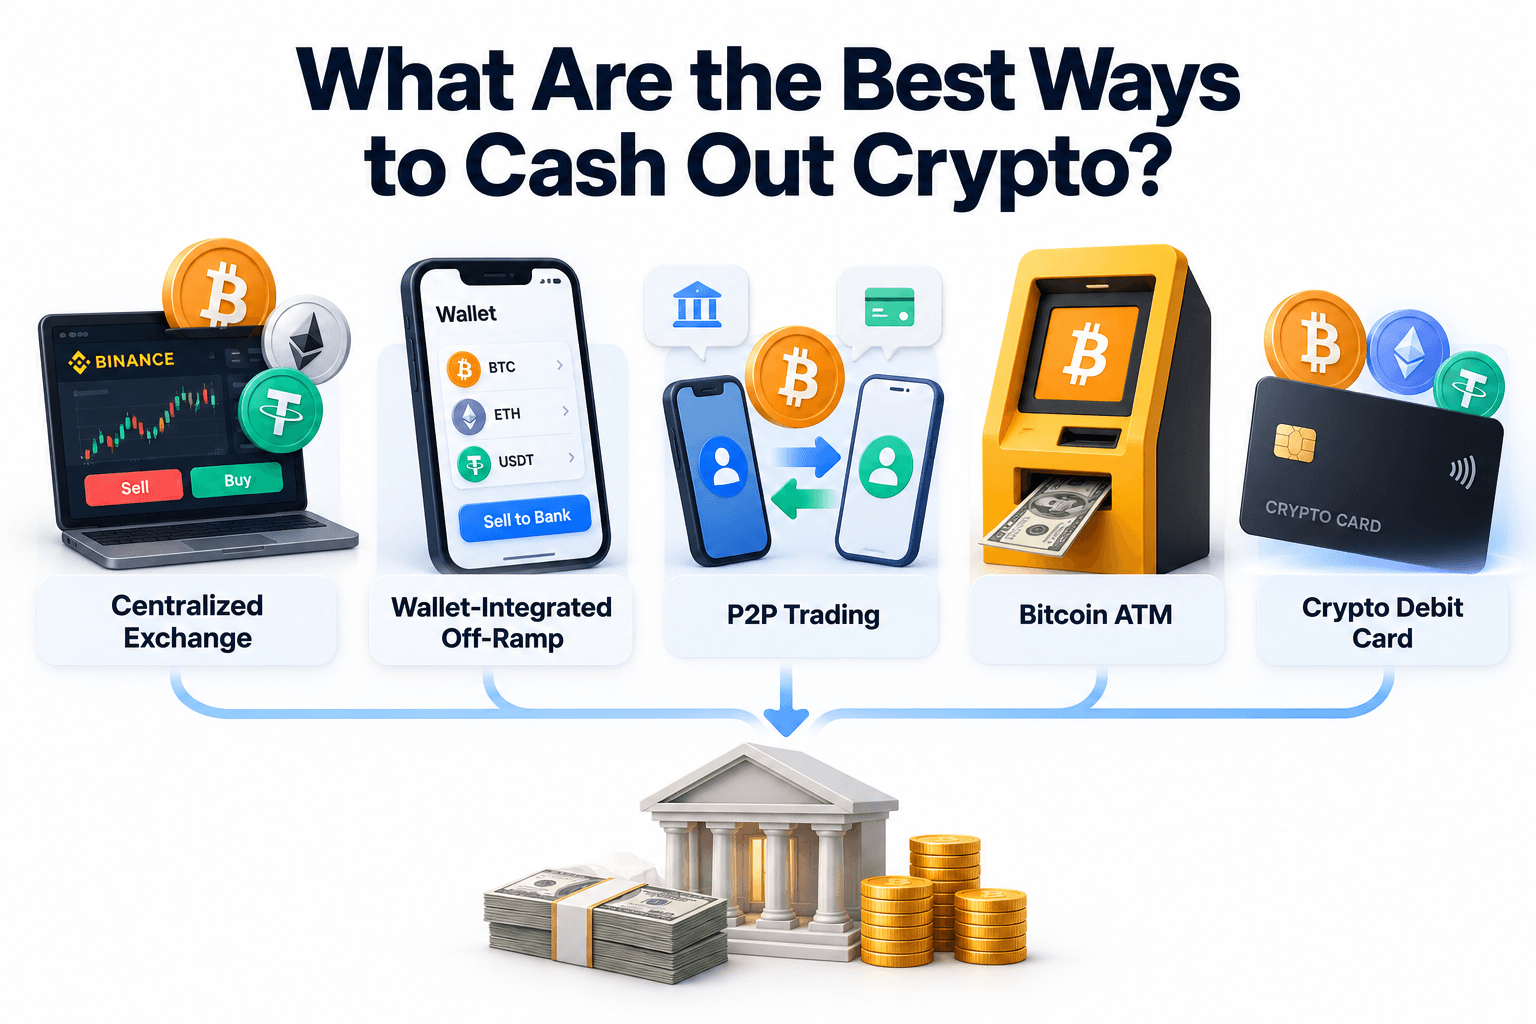 Comparing Exchanges, Wallets, And Alternative Crypto Cash-Out Methods
The best way to cash out cryptocurrency depends on the amount, preferred payment method, and whether the assets are held on an exchange or in a self-custody wallet.
Centralized exchanges generally suit conventional bank withdrawals and users who want control over trading prices. Wallet-integrated off-ramps offer a more direct route from self-custody, while P2P markets and cash-based services accommodate different local payment needs.
| Method | Best For | Payout Destination | Relative Cost | Typical Speed | KYC Requirements | Main Limitation |
|---|---|---|---|---|---|---|
| Centralized exchange | Bank withdrawals and liquid crypto sales | Bank account or supported payment service | Often competitive | Sale usually quick; bank settlement varies | Generally required | Withdrawal holds and regional restrictions |
| Wallet-integrated off-ramp | Selling directly from self-custody | Supported bank account or card | Provider-dependent | Minutes to several business days | Generally required by the provider | Asset and geographic restrictions |
| P2P trading | Alternative local payment methods | Agreed fiat payment method | Variable | Depends on counterparty and payment rail | Platform-dependent | Fraud and payment reversal risk |
| Bitcoin ATM | Receiving physical cash | Cash from a sell-enabled machine | Often higher | Operator-dependent | Depends on operator and local law | Limited sell support and high fees |
| Crypto debit card | Spending crypto or eligible ATM withdrawals | Merchant payments or ATM cash | Card-dependent | Usually processed during the transaction | Typically required | Conversion charges and ATM limits |
The cost and timing descriptions are starting points. A provider's actual quote, payment method, and jurisdiction determine the final terms.
Centralized Cryptocurrency Exchanges
Centralized exchanges allow users to sell cryptocurrency for fiat through an instant conversion interface or a spot trading market, then transfer the proceeds through supported banking networks.
Recognizable examples include Coinbase, Kraken, and Binance. Their trading interfaces may look similar, but the available fiat currencies, payment methods, and withdrawal permissions differ by jurisdiction and operating entity.
For example, Coinbase supports selling eligible cryptocurrency into a cash balance, which customers can subsequently withdraw through supported methods. Kraken publishes separate cash withdrawal options covering eligible currencies, payment networks, limits, fees, and processing times.
An exchange may support BTC trading globally while offering bank withdrawals only in selected countries. Some regional entities may also operate under different requirements or provide a narrower range of products.
For that reason, an exchange's popularity or total number of listed cryptocurrencies tells you relatively little about how conveniently you can withdraw money.
Three factors provide a better basis for comparison:
- Liquidity: Active trading markets generally support better execution, particularly when selling larger amounts or less frequently traded cryptocurrencies.
- Trading costs: The quoted selling price, trading commission, and withdrawal charges determine the net proceeds.
- Banking access: The exchange must support your desired fiat currency, recipient account, and payment network.
Centralized exchanges also take custody of deposited cryptocurrency. While that makes transactions convenient, users depend on the platform's security, compliance procedures, and withdrawal availability.
For someone making regular withdrawals into a conventional bank account, a reputable exchange offering liquid fiat markets and low-cost domestic transfers can be an efficient option.
Wallet-Integrated Crypto Off-Ramps
Wallet-integrated off-ramps allow users to initiate a cryptocurrency sale from a self-custody wallet and receive fiat through an external payment provider.
Services such as MoonPay and Ramp Network connect wallet transactions with supported bank accounts, cards, and other payout methods.
The process begins with a sell order. The provider quotes a fiat payout for the selected cryptocurrency, requests any necessary verification, and supplies instructions for transferring the asset. Once the cryptocurrency arrives and the transaction is processed, the provider arranges payment to the selected destination.
Comparing the final bank payout against an equivalent exchange transaction shows whether the convenience justifies the cost.
P2P Trading and Crypto Cards
P2P trading allows cryptocurrency holders to sell directly to another person using an agreed fiat payment method.
On supported platforms, escrow temporarily holds the cryptocurrency while the buyer sends payment. Once the seller confirms that the funds have arrived, the cryptocurrency can be released.
This arrangement can accommodate local bank transfers and other payment services that conventional exchanges may not support. However, escrow protects the crypto transfer process rather than guaranteeing the finality of every fiat payment.
A buyer may submit a forged payment screenshot, transfer money from an unrelated account, or use a payment method subject to chargebacks. Sellers should verify payment through their own banking application and understand whether the payment can be reversed before releasing cryptocurrency.
Availability, identity verification, and dispute protection also depend on the P2P platform and local regulations.
Crypto cards provide a different route. Eligible crypto debit cards can convert supported cryptocurrency into fiat when making merchant payments, and some programs allow physical cash withdrawals at ATMs.
Spending through a card differs from withdrawing a crypto sale's proceeds into a bank account. Cardholders may encounter conversion margins, foreign exchange charges, ATM fees, and daily cash limits.
A crypto-backed credit card or lending product may instead allow borrowing against existing cryptocurrency. In that arrangement, the holder retains the crypto exposure while taking on a repayment obligation and potentially collateral liquidation risk.
For users seeking traditional bank deposits, centralized exchanges and wallet off-ramps are generally more direct. P2P markets and crypto cards become useful when the preferred local payment method or intended use of the funds calls for a different route.
How to Cash Out Crypto to a Bank Account: Step by Step
Cashing out cryptocurrency to a bank account involves setting up an eligible withdrawal destination, selling the cryptocurrency for fiat, and transferring the available cash balance.
Most centralized exchanges support some variation of this workflow, but the exact account requirements and interface options differ. Checking banking access before transferring cryptocurrency is particularly useful because a supported trading pair does not guarantee a supported fiat withdrawal.
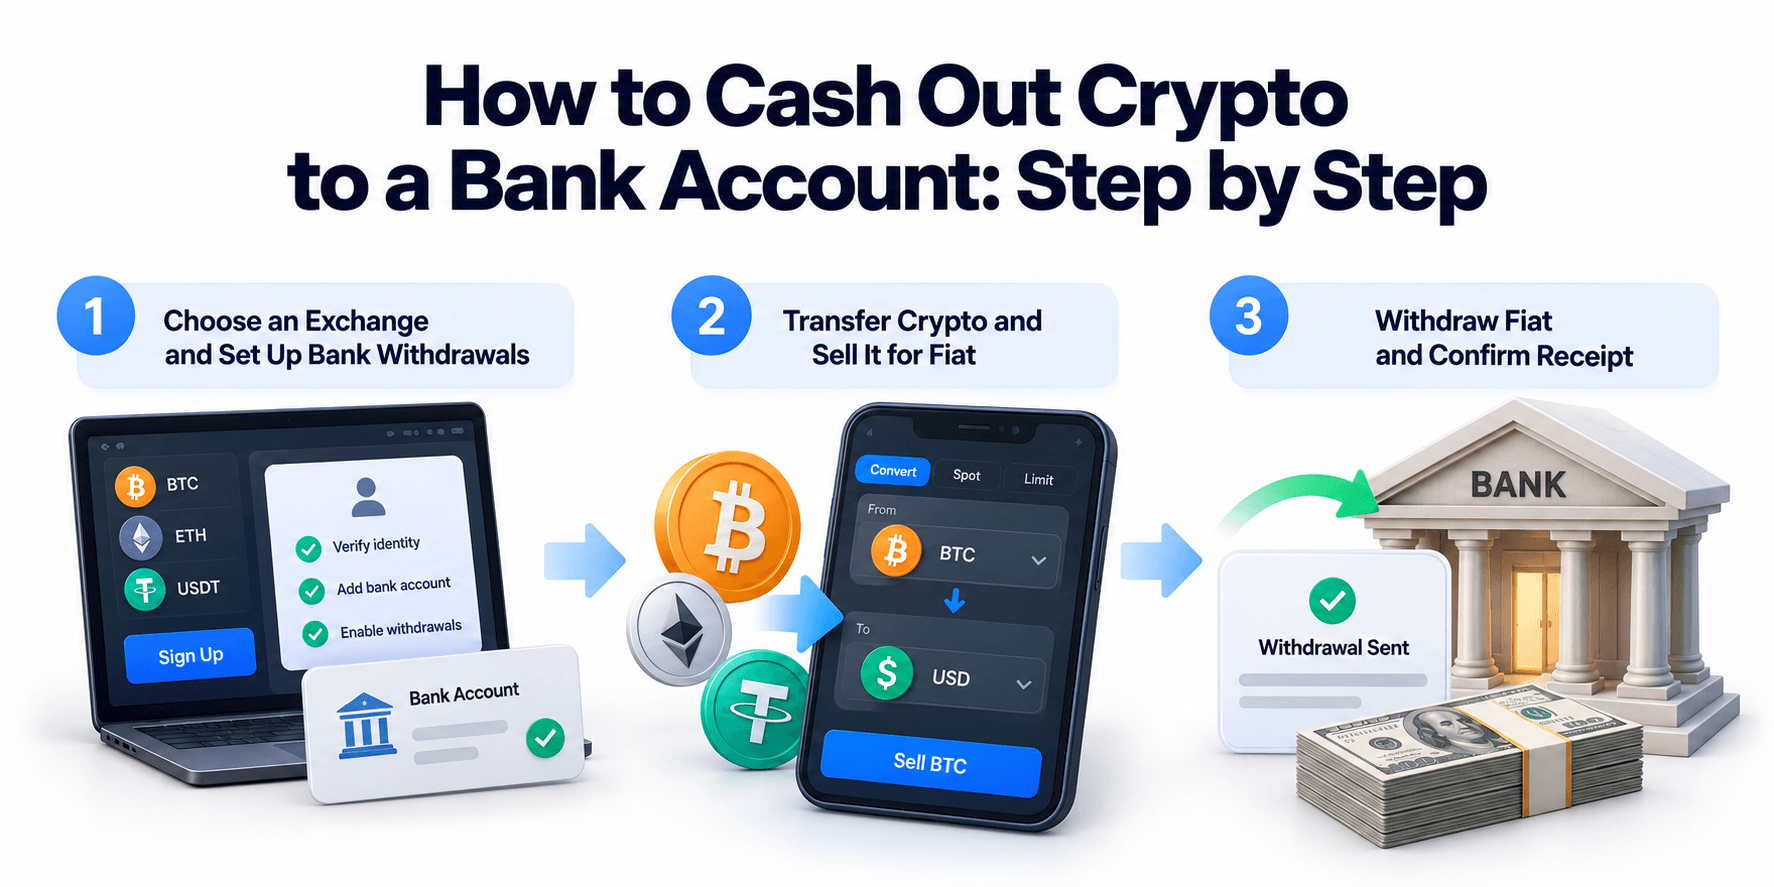 Moving Crypto Proceeds Through Exchange Sales And Bank Withdrawals
Step 1: Choose an Exchange and Set Up Bank Withdrawals
Start by selecting an exchange that supports your cryptocurrency, country of residence, desired fiat currency, and bank withdrawal method.
For example, an investor seeking a USD withdrawal needs an exchange that supports both the relevant crypto-to-USD sale and an eligible USD payment method for that investor's account.
Once you have selected a provider, complete the required identity verification and connect the payment destination.
Know Your Customer (KYC) procedures generally involve confirming personal details and submitting identification documents. Some providers also require proof of address or additional verification depending on the account and transaction.
After verification, add your bank account or another eligible payment method. Certain exchanges require the recipient account holder's name to match the verified customer name, while others may require a small initial deposit or separate bank verification.
Available banking networks vary by region:
- United States: ACH transfers and domestic wire transfers.
- United Kingdom: Faster Payments and other eligible bank transfer methods.
- Europe: SEPA and, where supported, SEPA Instant transfers.
Before depositing crypto, check the minimum fiat withdrawal, applicable fees, daily limits, and any security or recent-funding holds. Verification requirements and payment options may differ even between customers using the same exchange.
If you are still comparing providers, our best crypto exchanges guide evaluates the main platforms across trading costs, security, usability, and regional access.
Step 2: Transfer Crypto and Sell It for Fiat
If your cryptocurrency is already stored on the selected exchange, you can proceed directly to the sale.
Otherwise, open the exchange's crypto deposit section, select the exact cryptocurrency, and generate a receiving address for a supported blockchain network.
The transfer details must match the sending wallet. A correct token sent through an unsupported network may never appear in the exchange account.
Before transferring, verify:
- Cryptocurrency: Confirm that the exchange accepts deposits of the exact token.
- Blockchain network: Match the receiving network with the one selected in your sending wallet.
- Wallet address: Compare the entire receiving address against the exchange's instructions.
- Memo or tag: Include any additional destination identifier required by the exchange.
- Minimum deposit: Make sure the amount meets the provider's deposit threshold.
A cryptocurrency wallet address identifies where a blockchain transfer should be delivered. It must be copied accurately, and the sender must use a compatible network.
For larger transfers, consider sending a small test transaction first if the network fee and minimum deposit make that practical.
Once the exchange receives the cryptocurrency and completes its required confirmations, the deposit should appear in your trading balance.
You can then sell through an instant conversion service or a supported spot trading market.
An instant sell interface displays a quoted fiat amount for the cryptocurrency being sold. The quoted rate may already incorporate a spread, while additional service fees may appear separately.
In a spot market, the user can sell against available buy orders. A market order generally executes against available liquidity, although the final price may differ from the last displayed market price when order-book depth is limited.
For example, a seller holding BTC might use a BTC/USD market to receive dollars directly. If only a BTC/USDT market is available, an additional conversion from USDT into fiat may be required.
Before confirming the sale, compare the execution price, applicable fee, and expected fiat proceeds. After execution, the exchange credits the resulting cash balance according to its account rules.
Step 3: Withdraw Fiat and Confirm Receipt
Once the cryptocurrency has been sold, navigate to the exchange's fiat or cash withdrawal area.
Select the available cash balance, choose the linked bank account or another supported payout method, and enter the amount you want to withdraw.
The withdrawal preview should identify the destination, currency, fees, and estimated processing time. Check these details before confirming the request.
Coinbase's cash withdrawal workflow allows eligible customers to review the withdrawal amount and payment destination before authorizing the transaction.
After submitting, save the confirmation and any associated payment reference.
The status may pass through several stages:
| Withdrawal Status | What It Means |
|---|---|
| Initiated | The exchange has received the withdrawal request |
| Processing | The provider is conducting the necessary payment or account checks |
| Processed or sent | The provider has dispatched or completed its part of the payment |
| Received | The recipient bank or payment account has credited the funds |
A withdrawal marked as processed may still be awaiting bank settlement. Similarly, recently deposited funds or account reviews can restrict withdrawals even after the cryptocurrency sale is complete.
The cash-out process finishes when the money reaches your intended payment destination.
How Do You Cash Out Crypto From a Wallet?
Cashing out cryptocurrency held in a self-custody wallet requires a compatible off-ramp or an exchange that supports fiat withdrawals. Wallets manage the credentials used to authorize blockchain transactions, while third-party providers handle the conversion into traditional currency.
The appropriate route depends on whether the wallet offers an integrated selling service, whether the cryptocurrency and network are supported, and how the user wants to receive the money.
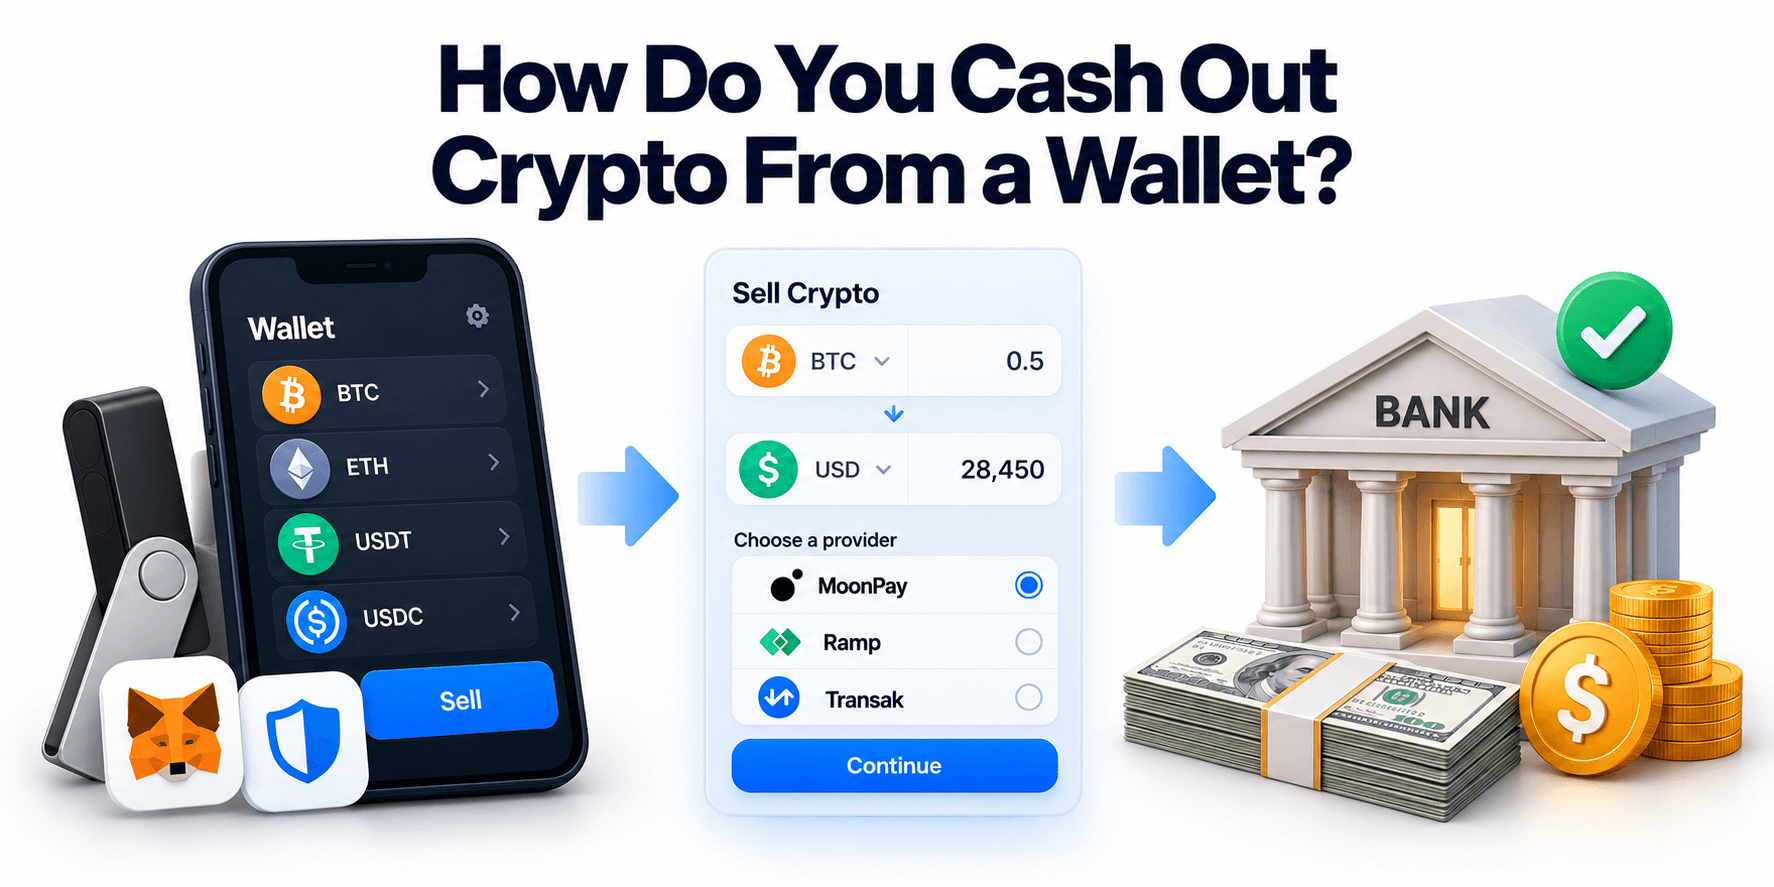 Wallet Cash-Outs Depend On Compatible Providers And Networks
Cashing Out Through a Wallet's Built-In Sell Feature
Many self-custody wallets integrate external providers that allow users to initiate cryptocurrency sales without first moving funds into a conventional exchange trading account.
For example, MetaMask and Trust Wallet offer access to third-party selling integrations, with eligible assets, countries, and payout methods varying by provider.
The process generally begins inside the wallet interface:
- Select the cryptocurrency you want to sell.
- Open the available Sell feature and enter the amount.
- Choose an eligible fiat currency and payout method.
- Compare the available provider quotes.
- Complete the required verification.
- Authorize the cryptocurrency transfer.
- Track the order until the fiat proceeds are paid out.
Cashing Out From a Hardware Wallet or Unsupported Wallet
Cryptocurrency stored through a hardware wallet can be sold in much the same way as assets held in a software wallet.
Devices such as Ledger and Trezor protect the private keys used to authorize blockchain transactions. They do not prevent users from transferring the assets to a compatible exchange or off-ramp.
If the wallet interface offers a supported sell integration, users may be able to initiate the process directly. Otherwise, they can generate an exchange deposit address and authorize a transfer from the hardware device.
The key checks remain the same: confirm that the exchange accepts the asset, select the correct blockchain network, verify the receiving address, and approve the transaction securely.
A hardware wallet provides an additional signing checkpoint because transaction authorization takes place through the physical device. Users should still inspect the receiving address and transaction details displayed before approving.
For unsupported wallets, the same transfer process applies using the wallet's normal send functionality.
Never provide private keys or recovery credentials to an exchange or off-ramp. Providers need a valid incoming cryptocurrency transfer, not control of the wallet itself.
Once the exchange credits the cryptocurrency, the user can sell it and initiate the fiat withdrawal described earlier.
How to Convert USDT or USDC Into Cash
Cashing out stablecoins involves exchanging the tokens for fiat currency through a supported provider, then receiving the proceeds through an eligible payout method.
Both USDT and USDC are designed to track the U.S. dollar, although they remain blockchain-based tokens with their own issuer, network, and redemption considerations.
The main operational complication is network compatibility.
For example:
- USDT may be held on Tron, Ethereum, or another supported blockchain.
- USDC may be held on Ethereum, Base, Solana, or another supported network.
USDC on Ethereum typically uses the ERC-20 token standard, while USDC on Solana operates through Solana's token infrastructure. These are different blockchain environments, even when the asset carries the same name.
An exchange listing USDC does not automatically accept deposits from every network where USDC exists.
Users should confirm the supported network and, where relevant, token contract before initiating the transfer. The transaction may also incur network fees, fiat conversion spreads, redemption restrictions, and banking charges.
Stablecoin availability introduces an additional consideration for European users.
On Oct. 8, 2026, the European Securities and Markets Authority (ESMA) published an opinion requiring MiCA-authorized crypto-asset service providers to cease services involving stablecoins that do not comply with the EU's Markets in Crypto-Assets Regulation.
The opinion covers services including exchange, trading, custody, transfers, and order execution. It also allows limited, time-bound activity necessary to resolve existing customer exposures, including liquidation, conversion, withdrawal, and transfer.
For users cashing out through an EU-authorized provider, this can restrict which stablecoins are accepted or available for conversion. The opinion does not establish a universal prohibition on individuals simply holding a particular stablecoin.
Checking the provider's current deposit and off-ramp support before transferring stablecoins can prevent funds from arriving at a service that cannot process the intended sale.
How Much Does It Cost to Cash Out Crypto?
The total cost of cashing out cryptocurrency depends on the blockchain transfer, selling price, trading commission, payout method, and any currency conversion required.
A provider with low advertised trading fees may still produce a less favorable final payout if its exchange rate incorporates a wide spread or its bank withdrawal charges are high.
The most useful comparison is the amount of fiat received after all applicable costs.
Fees That Affect Your Final Cash-Out Amount
Five costs can affect the amount received from a cryptocurrency cash-out.
| Fee Type | What It Covers | When It Applies |
|---|---|---|
| Network fee | Blockchain transaction processing | When transferring assets from a wallet |
| Trading fee | Executing the crypto-to-fiat sale | When charged by the exchange |
| Spread | Difference between the execution quote and a comparable reference price | Common in instant conversions and quoted off-ramps |
| Withdrawal fee | Sending fiat to a bank account, card, or payment service | When the payout provider charges for the transfer |
| Currency conversion fee | Exchanging one fiat currency for another | When payout and destination currencies differ |
The costs do not necessarily apply together.
For instance, selling cryptocurrency already held on an exchange avoids an additional blockchain transfer. A domestic bank withdrawal may carry no separate charge, while an international transfer could involve both exchange-rate conversion and intermediary banking fees.
Network fees vary by blockchain and transaction conditions. On Ethereum, these are commonly called gas fees, and the amount depends partly on the network's activity and the transaction being executed.
Trading commissions, meanwhile, are often calculated as a percentage of the order value. Instant sell services may combine explicit fees with a less favorable quoted price.
The net amount can be calculated as:
Net Fiat Received = Gross Sale Proceeds − Applicable Fees
Gross sale proceeds should already reflect the executed selling price, including any spread or slippage. Subtracting those costs again would double-count them.
Consider a hypothetical user cashing out $1,000 worth of Bitcoin from an external wallet.
| Cost Component | Centralized Exchange | Wallet-Integrated Off-Ramp |
|---|---|---|
| Starting BTC value | $1,000.00 | $1,000.00 |
| Network transfer cost | $3.00 | $3.00 |
| Value available for sale | $997.00 | $997.00 |
| Spread or price impact | $1.00 | $10.00 |
| Gross sale proceeds at executed price | $996.00 | $987.00 |
| Trading or service fee | $3.00 | $20.00 |
| Fiat payout fee | $0.00 | $2.00 |
| Final Fiat Received | $993.00 | $965.00 |
| Total Cash-Out Cost | $7.00 | $35.00 |
These figures are illustrative assumptions rather than live quotes.
In this example, the centralized exchange leaves the user with $28 more. The difference arises from the combined conversion and payout costs, rather than any single fee.
Users should compare the final amount shown in each provider's transaction preview rather than manually subtracting fees already included in the quote.
How to Minimize Crypto Cash-Out Fees
Reducing cash-out costs begins with choosing a route that avoids unnecessary transactions while still providing a suitable payout method.
A few practices can help:
- Compare net proceeds: Review how much fiat each provider will deliver for the same cryptocurrency amount.
- Use direct fiat markets: Selling BTC directly into USD or EUR can eliminate an additional stablecoin conversion when a sufficiently liquid trading pair exists.
- Avoid unnecessary swaps: Multiple conversions increase transaction costs and may create additional taxable disposals.
- Compare withdrawal speeds: Standard bank transfers may cost less than instant card or expedited payouts.
- Account for minimum fees: Fixed withdrawal charges consume a larger percentage of smaller cash-outs.
- Check market depth: Larger sales require sufficient buyers to execute without excessive price movement.
For larger transactions, slippage can reduce the effective selling price. A market order may execute across several prices if the available buy orders cannot absorb the full sale at the quoted level.
A smaller order or a more controlled execution approach may reduce this effect, although market prices can move before the order completes.
The cheapest route therefore depends on the transaction size, asset liquidity, available trading pairs, and banking method. Comparing the expected net payout provides a more reliable answer than choosing an exchange solely by its headline trading fee.
How Long Does It Take to Cash Out Crypto?
Cashing out cryptocurrency may take minutes or several business days, depending on the payment route and whether the funds must first move between wallets.
The sale itself may complete quickly, but blockchain confirmations, exchange crediting, account holds, and bank settlement can extend the overall process.
Crypto Cash-Out Processing Times by Method
The total withdrawal time depends on each stage required before the user receives fiat.
| Withdrawal Stage or Method | What Determines the Time | Potential Delay |
|---|---|---|
| Crypto transfer | Blockchain confirmations and exchange crediting requirements | Network congestion or unsupported deposits |
| Exchange sale | Order execution and available liquidity | Thin markets or trading restrictions |
| Standard bank withdrawal | Banking rail and provider processing schedule | Weekends, holidays, payment reviews |
| Instant payout | Provider, bank, and payment method eligibility | Transaction limits and service availability |
| P2P transaction | Counterparty payment and verification | Payment disputes or delayed bank transfers |
An external wallet transfer introduces blockchain confirmation time before the cryptocurrency can be sold. Some exchanges require multiple confirmations before crediting deposits, while others may use additional internal checks.
Once the crypto is credited, a liquid spot market can execute a sale quickly. The fiat withdrawal then follows the selected payment network's processing schedule.
For example, Kraken's published withdrawal options list eligible U.S. ACH withdrawals as taking approximately zero to two business days. Other wire and international transfer methods have different processing estimates and fees.
Wallet off-ramp timings also vary. MoonPay's selling instructions cover the transaction sequence from creating an order to receiving fiat, with settlement depending on the destination and payment provider.
Faster payment options may be available through eligible card transfers, domestic real-time payment systems, or SEPA Instant. These can reduce banking settlement time, although provider verification and crypto processing still apply.
Advertised instant payouts should therefore be understood as available payment capabilities rather than guaranteed end-to-end cash-out times.
Why Some Crypto Withdrawals Take Longer
Withdrawal delays generally arise from funding restrictions, verification requirements, transaction reviews, or banking settlement schedules.
Some exchanges allow customers to trade using recently deposited money while restricting withdrawals until the deposit clears.
For example, Kraken's withdrawal hold rules describe temporary restrictions associated with certain funding methods, including ACH and card purchases. These holds can affect both fiat and cryptocurrency withdrawals.
Account verification may create additional delays when personal information is incomplete or a transaction requires further review. Large or unusual withdrawals can also trigger checks related to account security or the origin of funds.
Banking schedules introduce another delay. A payment processed by an exchange on a weekend may still depend on the receiving bank's next available settlement cycle.
When an external wallet transfer is involved, network congestion and the exchange's confirmation threshold determine when the crypto becomes available for sale.
A completed blockchain transfer confirms that the on-chain transaction was recorded. It does not establish that the exchange has credited the balance or that a subsequent fiat withdrawal has reached the bank.
Why Can't I Withdraw My Crypto? Common Cash-Out Problems
Crypto cash-outs can fail at three main points: the cryptocurrency deposit, the exchange's fiat withdrawal stage, or the receiving bank.
Identifying which stage failed helps determine whether you should inspect a blockchain transaction, resolve an exchange account restriction, or trace a conventional bank transfer.
| Problem | Possible Cause | What to Check | Recommended Action |
|---|---|---|---|
| Crypto sold, but cash unavailable | Funding hold, incomplete verification, withdrawal limit | Available balance and account notices | Resolve restrictions or contact official support |
| Crypto deposit missing | Network mismatch, insufficient confirmations, missing memo | Transaction hash and deposit instructions | Supply transaction details to the receiving provider |
| Withdrawal pending | Payment processing or compliance review | Withdrawal status and expected timeframe | Follow the provider's official process |
| Bank payout rejected | Incorrect details, account mismatch, unsupported payment rail | Bank information and payment reference | Confirm the return before submitting another payout |
| Payout lower than expected | Spread, fees, foreign exchange charges | Trade receipt and banking statement | Reconcile all transaction costs |
Crypto Sold but Cash Not Available to Withdraw
An exchange may display the proceeds of a completed crypto sale while restricting how much of that balance can be withdrawn.
This can occur when the account has an outstanding funding hold, incomplete identity verification, or a security restriction. Daily withdrawal limits and payment-method eligibility may also reduce the immediately available amount.
The first check should be the difference between the total fiat balance and the available withdrawal balance.
If those amounts differ, review the exchange's recent funding history, verification notices, and withdrawal restrictions. A completed cryptocurrency sale does not necessarily clear an existing account hold.
When the reason remains unclear, contact official customer support with the account status and relevant transaction reference.
Crypto Transfer Completed but Funds Are Missing
A cryptocurrency transfer may appear successful on-chain while remaining absent from the receiving exchange account.
This happens because the blockchain and the exchange maintain separate records. A confirmed transaction establishes that funds were transferred to an address, while the exchange must still identify the deposit and credit the appropriate customer.
Insufficient confirmations can cause a temporary delay. More serious issues include sending funds over an unsupported network, omitting a required memo or destination tag, or depositing less than the provider's minimum amount.
Start by locating the transaction hash in the sending wallet.
Use the appropriate blockchain explorer to verify the destination, asset, amount, network, and confirmation status. Then compare the details against the exchange's deposit history.
If the transfer is confirmed but remains uncredited, supply the receiving provider with:
- Transaction hash.
- Cryptocurrency and blockchain network.
- Sending and receiving addresses.
- Transfer amount and approximate time.
- Memo or destination tag, where applicable.
- Screenshots of the exchange deposit instructions and wallet transaction.
Some exchanges offer recovery services for certain unsupported deposits, occasionally with additional fees. Recovery depends on whether the provider can access the funds and supports a recovery procedure.
A transaction sent to an incorrect destination or incompatible network may be impossible to recover.
Bank Withdrawal Rejected, Delayed or Returned
Bank withdrawals can be rejected because of incorrect recipient details, account-name mismatches, unsupported payment methods, or compliance restrictions.
Some banks also review incoming transfers from cryptocurrency service providers and may request additional information before crediting the funds.
When a bank returns a payment, the exchange or payment provider must receive and reconcile the returned funds before the balance can become available again.
Check the withdrawal status, bank details, payment reference, and any rejection message. If the provider reports that the payment was sent, ask for the relevant trace information.
Avoid submitting another withdrawal until you know whether the original payment remains pending or has been returned.
A bank rejection usually concerns the fiat payment stage. It does not automatically mean the cryptocurrency sale failed or that the original digital assets were lost.
How to Cash Out Crypto Safely
A safe crypto cash-out starts with verifying the receiving provider, checking the transaction details, and protecting access to the wallet or exchange account.
The risks depend on the method. Exchange users face custodial and account restrictions, self-custody users must authorize transfers correctly, and P2P sellers must verify that the buyer's payment is genuine and final.
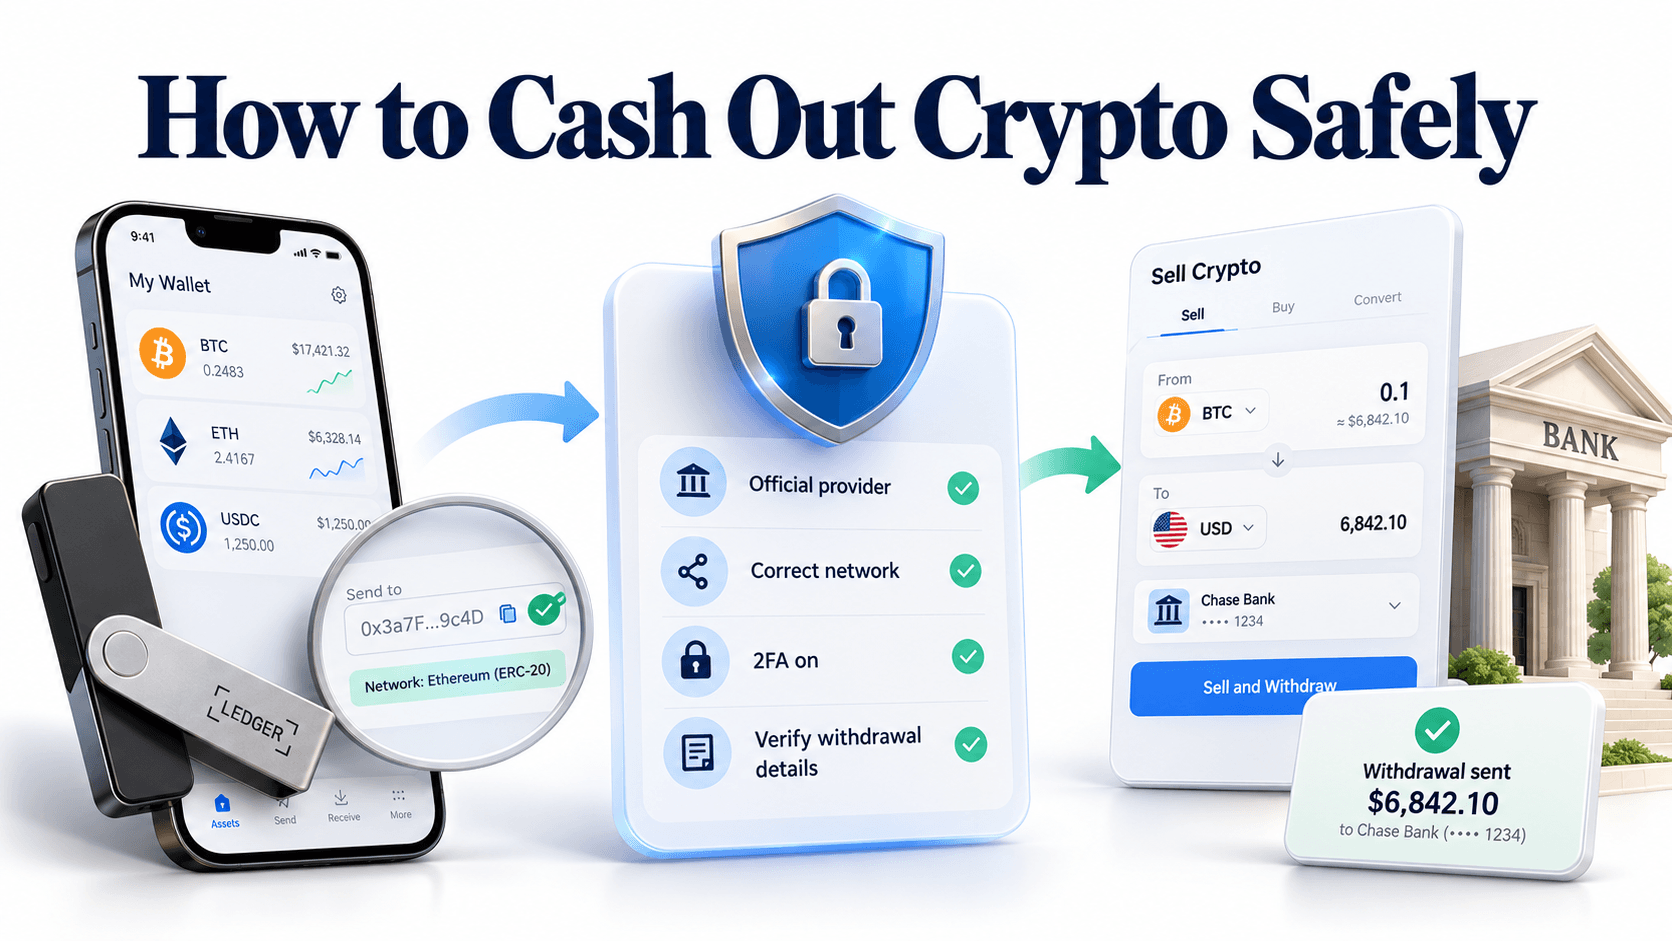 Secure Transfers And Verified Payouts Reduce Cash-Out Risks
Protecting Your Crypto During Transfers and Sales
Choose a provider that legitimately operates in your jurisdiction and supports the exact payment method you intend to use.
Before transferring cryptocurrency, confirm that the website or application belongs to the real provider. Fake exchange websites and impersonated support accounts may use familiar branding to collect deposits or steal account credentials.
Several precautions directly reduce cash-out risks:
- Verify provider domains: Use official websites, trusted bookmarks, and genuine applications rather than links supplied by unknown contacts.
- Confirm transaction details: Check the asset, network, address, and any required memo before initiating a transfer.
- Protect recovery credentials: Never share your seed phrase, private key, or authentication codes with anyone claiming to provide withdrawal assistance.
- Use strong account authentication: Enable passkeys, authenticator-based two-factor authentication, or hardware security keys where supported.
- Consider test transfers: Sending a small amount first can help confirm the receiving setup before a larger transaction.
- Understand custody and counterparty risks: An exchange controls deposited assets, while P2P sellers depend on payment from another person and the protections offered by the marketplace.
Coin Bureau's crypto security guide covers account protections, wallet signing, address verification, and common attack methods.
Cash-out scams also use a recognizable tactic: demanding an unexpected payment before existing funds can be released.
Fraudulent platforms may describe these demands as withdrawal taxes, unlocking charges, compliance deposits, or account activation fees.
Legitimate providers can charge disclosed transaction and withdrawal fees. However, an unexpected instruction to send additional cryptocurrency to an unrelated wallet to unlock existing funds is a major warning sign.
Our guide to crypto scams explains how fraudulent exchanges, fake support agents, and advance-fee schemes use withdrawal problems to extract further payments.
KYC, Bank Checks and Large Crypto Withdrawals
Fiat off-ramps commonly require identity verification because they connect cryptocurrency transactions with regulated payment and banking systems.
Applicable anti-money laundering (AML) requirements may oblige providers to verify customers, monitor transactions, and investigate unusual transfers.
Different services and transaction amounts can trigger different verification requirements, but users should not assume that smaller withdrawals or alternative payout routes automatically avoid KYC obligations.
Banks and exchanges may also request source-of-funds or source-of-wealth documentation, particularly for larger or unusual transactions.
Useful records include:
- Original cryptocurrency purchase receipts.
- Exchange deposit, trade, and withdrawal histories.
- Blockchain transaction records.
- Evidence of wallet ownership or control.
- Documents establishing how the original investment funds were obtained, where required.
Maintaining a clear transaction history helps explain how the funds moved from the original purchase through to the final withdrawal.
Large cryptocurrency sales also require attention to liquidity and withdrawal limits.
A substantial market order can move through multiple levels of available buy orders, reducing the effective selling price. Eligible investors may consider an over-the-counter (OTC) trading desk, which can arrange negotiated execution outside a conventional public order book.
OTC arrangements may have minimum trade sizes, additional verification requirements, and separate settlement procedures. Users should confirm the counterparty, fees, settlement method, and withdrawal terms before proceeding.
Splitting withdrawals specifically to evade reporting thresholds or compliance obligations is not an acceptable strategy and can itself raise regulatory concerns.
Physical cash withdrawals introduce different risks. P2P cash transactions involve direct counterparty exposure, while sell-enabled Bitcoin ATMs may impose higher fees, identification requirements, and transaction limits.
Conventional bank withdrawals generally produce a more traceable payment record, although the receiving institution may still delay, review, reject, or return a transfer.
Do You Pay Taxes When Cashing Out Crypto?
Cashing out cryptocurrency can create a taxable event, depending on your jurisdiction and how the assets were acquired, held, and sold.
In the United States, selling crypto for fiat generally creates a capital gain or loss when the asset is held as an investment. Moving the resulting fiat balance from an exchange to your own bank account is a separate payment transaction.
Selling Crypto vs. Transferring Funds: What's Taxable?
The U.S. Internal Revenue Service (IRS) treats digital assets as property for federal tax purposes.
Under its digital asset guidance, selling cryptocurrency can produce a taxable gain or loss based on the amount realized and the investor's adjusted cost basis.
The tax consequences arise from disposing of the cryptocurrency. That disposal can occur through a fiat sale, a crypto-to-crypto swap, or the purchase of goods and services using digital assets.
Converting BTC into USDC can therefore create a taxable event even though the user has not withdrawn traditional currency.
By contrast, transferring cryptocurrency between wallets or accounts owned by the same person generally does not itself constitute a taxable sale in the United States. Transaction fees paid in digital assets may have separate tax consequences.
| Transaction | General U.S. Tax Treatment |
|---|---|
| Selling BTC for USD | Potential capital gain or loss |
| Swapping ETH for USDC | Potential taxable disposal |
| Sending BTC between your own wallets | Generally not a taxable sale |
| Moving fiat proceeds to your bank | Generally not a separate crypto disposal |
| Spending crypto on goods or services | Potential taxable disposal |
Consider an investor who purchases Bitcoin for $700 and later sells it for net proceeds of $1,000 after eligible selling costs.
The simplified capital gain calculation is:
Capital Gain = $1,000 − $700 = $300
The $300 gain may be taxable according to the investor's holding period and applicable tax rules.
If the investor subsequently withdraws the $1,000 fiat balance from the exchange to a personal bank account, that withdrawal generally does not create an additional cryptocurrency capital gain.
The IRS separately addresses transfers between wallets owned by the same person.
Tax treatment can differ for business transactions, crypto received as income, mining rewards, and jurisdictions outside the United States.
Crypto Cash-Out Records and Tax Reporting
Accurate tax reporting requires records of both the cryptocurrency disposal and the related fiat proceeds.
At a minimum, retain the acquisition date, original cost basis, sale date, execution price, applicable fees, and net amount realized.
Exchange trade confirmations, wallet histories, and bank withdrawal records help reconcile the transaction when information is spread across multiple services.
For U.S. taxpayers, Form 1099-DA introduces broker reporting requirements for eligible digital asset transactions.
The IRS's reporting framework phases in the requirements as follows:
- From Jan. 1, 2025: Covered brokers generally began reporting gross proceeds from qualifying digital asset transactions.
- From Jan. 1, 2026: Basis reporting began applying to certain qualifying covered transactions and digital assets.
These requirements do not mean every cryptocurrency transaction will appear on Form 1099-DA. They also do not guarantee that the reported cost basis will be complete.
For example, an exchange receiving cryptocurrency from an external wallet may not possess the full purchase history required to determine the investor's original cost basis.
Taxpayers must therefore reconcile broker reports against their own records.
Applicable investment transactions are commonly reported using Form 8949, with capital gains and losses summarized on Schedule D.
Reporting rules differ across jurisdictions, including the treatment of gains, losses, transfers, and crypto received as income.
Our crypto taxes guide provides a broader explanation of taxable events, cost basis, reporting requirements, and tax calculations.
Closing Thoughts
Centralized exchanges and wallet-integrated off-ramps provide practical ways to convert cryptocurrency into fiat and transfer the proceeds through supported payment methods. P2P trading, crypto cards, and sell-enabled Bitcoin ATMs offer alternatives for users with different payment needs.
The most suitable route depends on the cryptocurrency, its blockchain network, the user's country, and the intended withdrawal destination. Trading fees, spreads, banking charges, verification requirements, and settlement times all affect the final result.
Before confirming a cash-out, verify the provider, receiving network, bank compatibility, withdrawal restrictions, and final fiat quote. These checks help ensure the cryptocurrency reaches a service capable of completing the sale and delivering the money to its intended destination.