

Ethereum pays validators for participating in consensus. Ordinary full nodes, light nodes and archive nodes earn no automatic staking rewards. A validator can earn ETH while self-hosting costs more than a provider. Compare avoided fees with equipment, electricity and maintenance expenses.
Solo validation suits long-term ETH holders with technical experience, reliable infrastructure and capital they can leave staked. It is less suitable for readers seeking maintenance-free income or immediate access to their funds.
Editor's Note (Oct. 31, 2026): We fully updated this guide in October 2026 to reflect current Ethereum staking rewards, ETH pricing and provider fees. The refresh adds clearer earnings and breakeven calculations, updated hardware guidance, and comparisons of solo, managed and liquid staking. We also explain Rocket Pool's 4 ETH operator model and Pectra compounding, while sharpening coverage of withdrawal delays, slashing risks and network upgrades.
Ethereum Node Profitability: Quick Answer
Yes, running an Ethereum validator can generate ETH rewards, but running an ordinary node does not automatically earn income. As of Oct. 31, 2026, the checked network benchmark was 2.75% annualized APR. At that rate, a 32 ETH validator could earn approximately 0.88 ETH ($1,963 at the article's assumed ETH price) annually before operating costs, taxes and penalties. However, solo staking is not necessarily more profitable than managed or liquid staking once equipment, electricity and maintenance are included.
Ethereum Node Profitability Key Points
-
Only validators receive Ethereum protocol staking rewards Full nodes, light nodes and archive nodes earn no automatic ETH rewards. Non-validating infrastructure can generate commercial income by selling RPC access, blockchain data or related services.
-
A 32 ETH validator could earn approximately 0.88 ETH annually At the checked 2.75% network APR, modeled gross rewards equal about $5.38 daily, $163.58 monthly or $1,962.97 annually using an assumed ETH price of $2,230.65. Actual rewards fluctuate.
-
Hardware and operating costs reduce solo staking profits The article models $1,200 in equipment, $180 in annual home operating expenses and $300 in yearly depreciation. That leaves approximately $1,482.97 in annual rewards after modeled expenses and depreciation, before taxes and labor.
-
Managed and liquid staking can outperform solo operation Under identical gross reward assumptions, the 8%-fee managed example produces $1,805.93 annually, while the 10%-fee liquid staking example produces $1,766.67. Both exceed the modeled solo result after depreciation.
-
Operating a validator with less than 32 ETH is possible Rocket Pool's Saturn 1 model allows an operator to supply a 4 ETH bond alongside 28 ETH of pooled backing. Operators can earn rewards on their bond and commission on matched ETH, but face additional protocol and operational risks.
-
Downtime, slashing and ETH volatility can erase profits Missed duties reduce rewards, conflicting validator signatures can trigger slashing, and ETH price declines can outweigh an entire year of staking income. Activation and withdrawal queues also limit immediate access to funds.
Disclaimer
Ethereum staking rewards, ETH prices, validator operating costs and protocol parameters can change. The earnings, yield comparisons and breakeven calculations in this guide use illustrative assumptions and do not guarantee future returns. This article is for educational purposes only and does not constitute financial, investment, tax or technical security advice. Conduct your own research before staking funds or operating validator infrastructure.
Disclosure
Some links in this guide may be affiliate links. If you choose to use a service through these links, we may earn a commission at no additional cost to you.
Can You Make Money by Running an Ethereum Node?
Ethereum rewards active validators for performing consensus duties. Other node operators need customers or a separate commercial service to generate revenue.
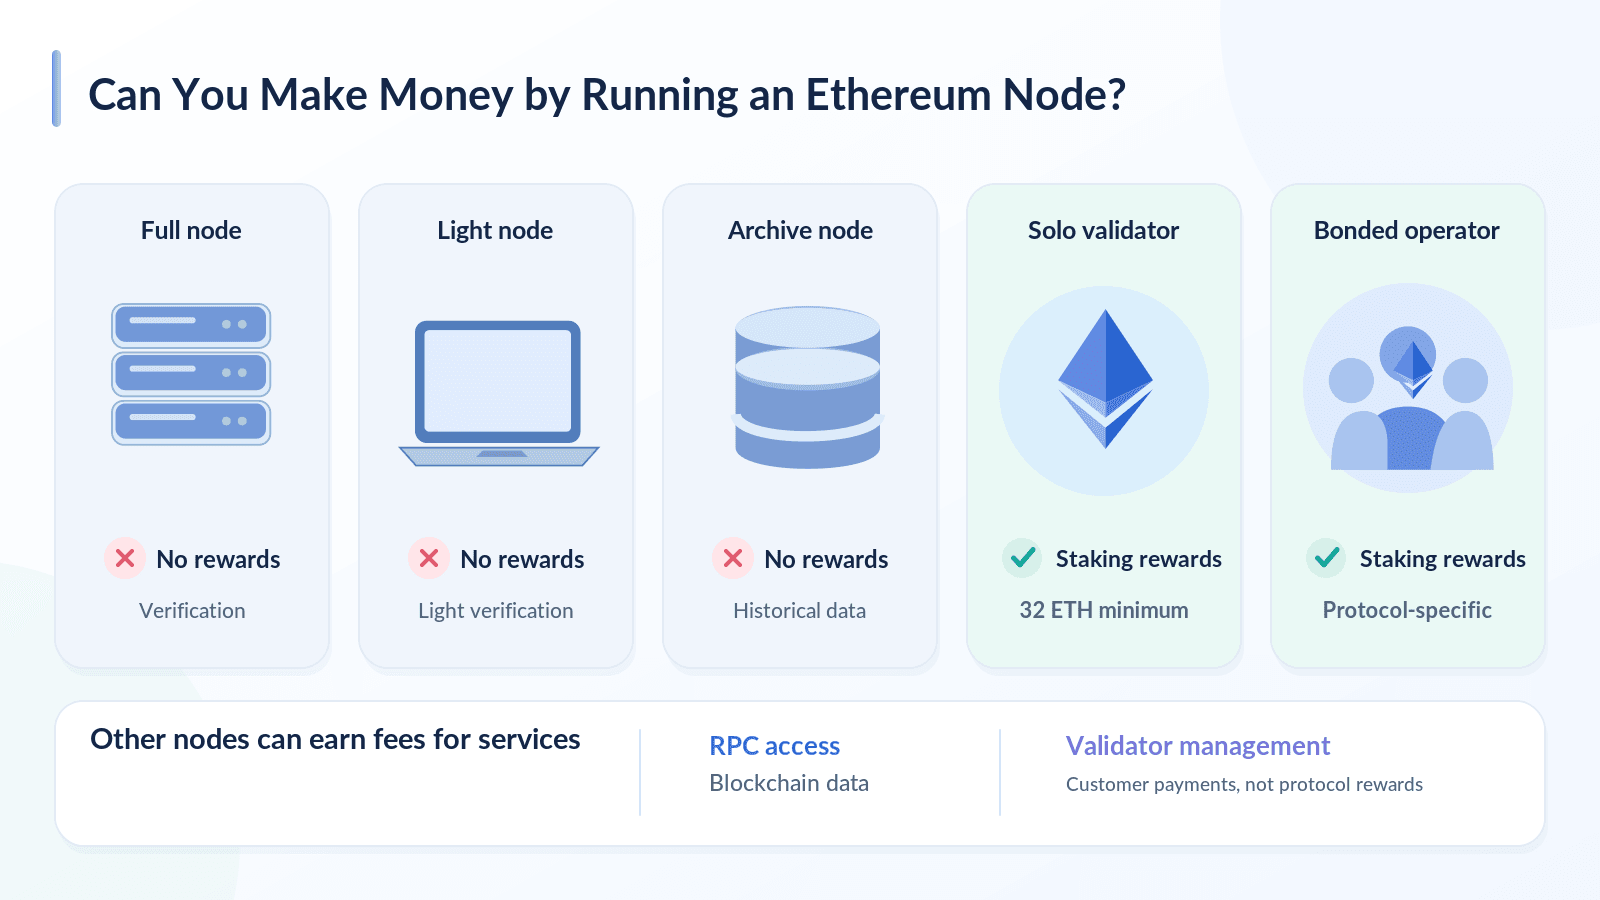 Comparing Ethereum Node Types, Validator Staking Rewards, and Alternative Income Opportunities Through Blockchain Infrastructure Services
Which Ethereum Nodes Actually Earn Rewards?
An Ethereum node verifies, stores or serves blockchain data according to its configuration.
| Node Type | Earns Protocol Staking Rewards? | ETH Required | Main Purpose |
|---|---|---|---|
| Full node | No | None | Independent verification |
| Light node | No | None | Lightweight verification |
| Archive node | No | None | Historical blockchain data |
| Solo validator | Yes | 32 ETH minimum | Network consensus and staking |
| Bonded validator operator | Yes, through the staking protocol's arrangements | Below 32 ETH | Operate validators using pooled backing |
Full nodes verify transactions and blocks. Archive nodes preserve historical state. Light nodes verify selected data using fewer resources.
The Ethereum node types serve different purposes. Without an active validator, none automatically generates ETH payments.
A validating setup combines three software roles:
- Execution client: Processes transactions and maintains Ethereum's execution state.
- Consensus client: Follows the chain and Ethereum's Proof of Stake consensus rules.
- Validator client: Uses signing keys to perform assigned validator duties.
Ethereum uses Proof of Stake (PoS): Validators commit ETH, earn rewards for correct duties and face penalties for failures.
Keeping node software online without validating earns no staking rewards.
Can Non-Validator Ethereum Nodes Generate Income?
Infrastructure operators can charge customers for remote procedure call access, usually shortened to RPC. Wallets and applications use RPC connections to request blockchain information or submit transactions.
Businesses also sell historical data, analytics or validator-management services. These are customer payments. Ethereum does not automatically compensate an archive node for storing extensive data or a full node for answering public requests.
Commercial income requires paying customers and enough revenue to cover infrastructure, bandwidth and support. A noncommercial node incurs costs while supporting independent verification.
How Much Can You Earn Running an Ethereum Validator in 2026?
Staking returns vary with network conditions, validator duties and transaction payments.
Current Ethereum Validator Rewards and APY
Rated's network benchmark showed 2.75% annualized APR in the 30-day view on Oct. 31, 2026.
| Reward Component | Annualized Rate |
|---|---|
| Consensus layer | 2.48% |
| Execution layer | 0.27% |
| Combined network APR | 2.75% |
Figment's Q3 2026 report found a 2.63% network-average rate for that quarter, a different reporting period.
Validator income includes:
- Consensus rewards: Payments for assigned duties, including attestations, which are votes about the chain's state.
- Priority fees: Transaction tips received when proposing blocks.
- MEV-related payments: Revenue associated with transaction inclusion and ordering. MEV means Maximal Extractable Value.
Builder payments can incorporate both transaction tips and MEV proceeds. Check the reporting method before adding dashboard categories together. Ethereum's base transaction fee is burned rather than paid to validators.
How Much Does a 32 ETH Validator Earn Per Day, Month and Year?
For this Oct. 31 example, assume an ETH price of $2,230.65, making 32 ETH worth $71,380.80 before purchase costs.
The following calculations assume a constant 32 ETH effective balance, simple annual rewards and no compounding. Daily and monthly figures divide annual earnings by 365 and 12.
| APR Scenario | Daily ETH | Monthly ETH | Annual ETH |
|---|---|---|---|
| 2.00% sensitivity case | 0.001753 | 0.053333 | 0.6400 |
| 2.63% historical benchmark | 0.002306 | 0.070133 | 0.8416 |
| 2.75% checked network benchmark | 0.002411 | 0.073333 | 0.8800 |
| 3.50% sensitivity case | 0.003068 | 0.093333 | 1.1200 |
Using the same $2,230.65 ETH price:
| APR Scenario | Daily USD | Monthly USD | Annual USD |
|---|---|---|---|
| 2.00% | $3.91 | $118.97 | $1,427.62 |
| 2.63% | $5.14 | $156.44 | $1,877.32 |
| 2.75% | $5.38 | $163.58 | $1,962.97 |
| 3.50% | $6.84 | $208.19 | $2,498.33 |
These modeled averages exclude expenses, taxes, activation delays and penalties.
Annual ETH rewards = Staked ETH × Assumed APR
The 32 ETH deposit is principal, not income.
USD income changes with ETH/USD even when ETH rewards remain unchanged. Annual earnings of 0.88 ETH would be worth $1,320 at $1,500 per ETH or $3,520 at $4,000.
ETH prices, staking rates and provider charges change over time. The figures above use illustrative assumptions.
Why Actual Validator Earnings Differ From Estimated APY
One validator can earn less or more than the network average.
Block selection is random and weighted by effective balance. A validator may experience months of low proposal income, known as proposer luck.
Execution-layer payments also fluctuate with available transactions and builder bids. One exceptional block can produce an impressive annualized figure without establishing repeatable income.
Missed attestations, delayed responses and client problems reduce earnings. A computer can remain online while its validator performs poorly.
Consensus rewards may remain inside the validator balance, while execution-layer payments normally go to a separate fee-recipient address. A dashboard showing earned ETH does not necessarily show spendable funds.
How Much Does It Cost to Run an Ethereum Validator?
There are equipment, recurring expenses and staked capital costs to consider
Ethereum Validator Hardware Requirements and Costs
Current hardware guidance recommends the following planning specifications for validating:
| Component | Recommended Specification |
|---|---|
| CPU | Fast processor with eight or more cores |
| RAM | 64 GB |
| Storage | 4 TB NVMe SSD |
| Download bandwidth | Approximately 50 Mbps |
| Upload bandwidth | At least 25 Mbps |
Client choice and configuration affect resource use. A technically workable minimum can leave less room for synchronization, maintenance and future growth.
The validator checklist lists 32 GB RAM and a 2 TB SSD as minimum planning figures, while recommending 64 GB and 4 TB. These should be distinguished from minimum specifications for a broader non-validating node setup.
Besides capacity, SSD endurance and sustained read/write performance affect syncing and reliability.
The examples assume $1,200 for equipment Hardware, shipping and tax costs vary.
Reusing equipment saves cash upfront, but aging or power-hungry machines may cost more over time.
A reliable internet connection is essential. An optional uninterruptible power supply, or UPS, can handle brief outages, but adds equipment and battery-replacement costs.
Home Hosting vs Cloud Hosting: Which Costs Less?
Home hosting can reduce recurring expenses when reliable broadband already exists. Renting a complete cloud server exchanges much of the equipment purchase for ongoing charges.
The budgets below are illustrative.
| Expense Or Dependency | Home Hosting | Self-Managed Cloud |
|---|---|---|
| Initial equipment | $1,200 assumed | No personal server purchase assumed |
| Recurring infrastructure | $15 monthly assumed | $100 monthly assumed |
| Electricity | Paid directly | Included in rental |
| Internet | Existing broadband; upgrades extra | Check bandwidth allowances and overages |
| Storage | Purchased SSD; eventual replacement | Check capacity, performance and charges |
| Maintenance | Hardware and software | Software and provider configuration |
| Main dependency | Home power and connectivity | Provider infrastructure and account access |
At an assumed 40 watts average consumption and $0.15 per kWh, annual electricity spending is $52.56:
0.04 kW × 8,760 hours × $0.15 = $52.56
The $180 annual home budget includes electricity and small expenses, but excludes broadband upgrades, labor and major repairs.
A $100 monthly virtual private server (VPS) or cloud budget equals $1,200 annually. Confirm that the rental includes enough processing power, storage and bandwidth for both clients.
Managed hosting can cost less than renting a dedicated server because infrastructure is shared.
Home operators can also run multiple validators on shared execution and consensus infrastructure. Another validator key does not automatically require another complete computer, although additional load still needs monitoring.
Hidden Costs That Reduce Validator Profitability
Capital expenditure (CapEx) covers equipment; operating expenditure (OpEx) covers recurring costs.
Common omissions include:
- Maintenance: Fans, SSD replacements and unexpected repairs.
- Connectivity: Broadband upgrades, data overages and backup service.
- Power: Electricity, UPS batteries and backup equipment.
- Operator time: Updates, troubleshooting, monitoring and recovery.
- Transactions: Deposits and operations requiring execution-layer transactions.
Hardware failure can create repair costs and missed rewards while clients recover or resynchronize.
Spreading a $1,200 setup across four years, with no assumed resale value, produces $300 in annual depreciation. This accounting cost is not a recurring cash payment.
Subtracting the entire purchase price and depreciation in the same accounting period would double-count the hardware.
Is Solo Ethereum Staking More Profitable Than Using a Staking Service?
Solo staking avoids provider charges. Its financial advantage appears only when those savings exceed additional operating costs and equipment expenses.
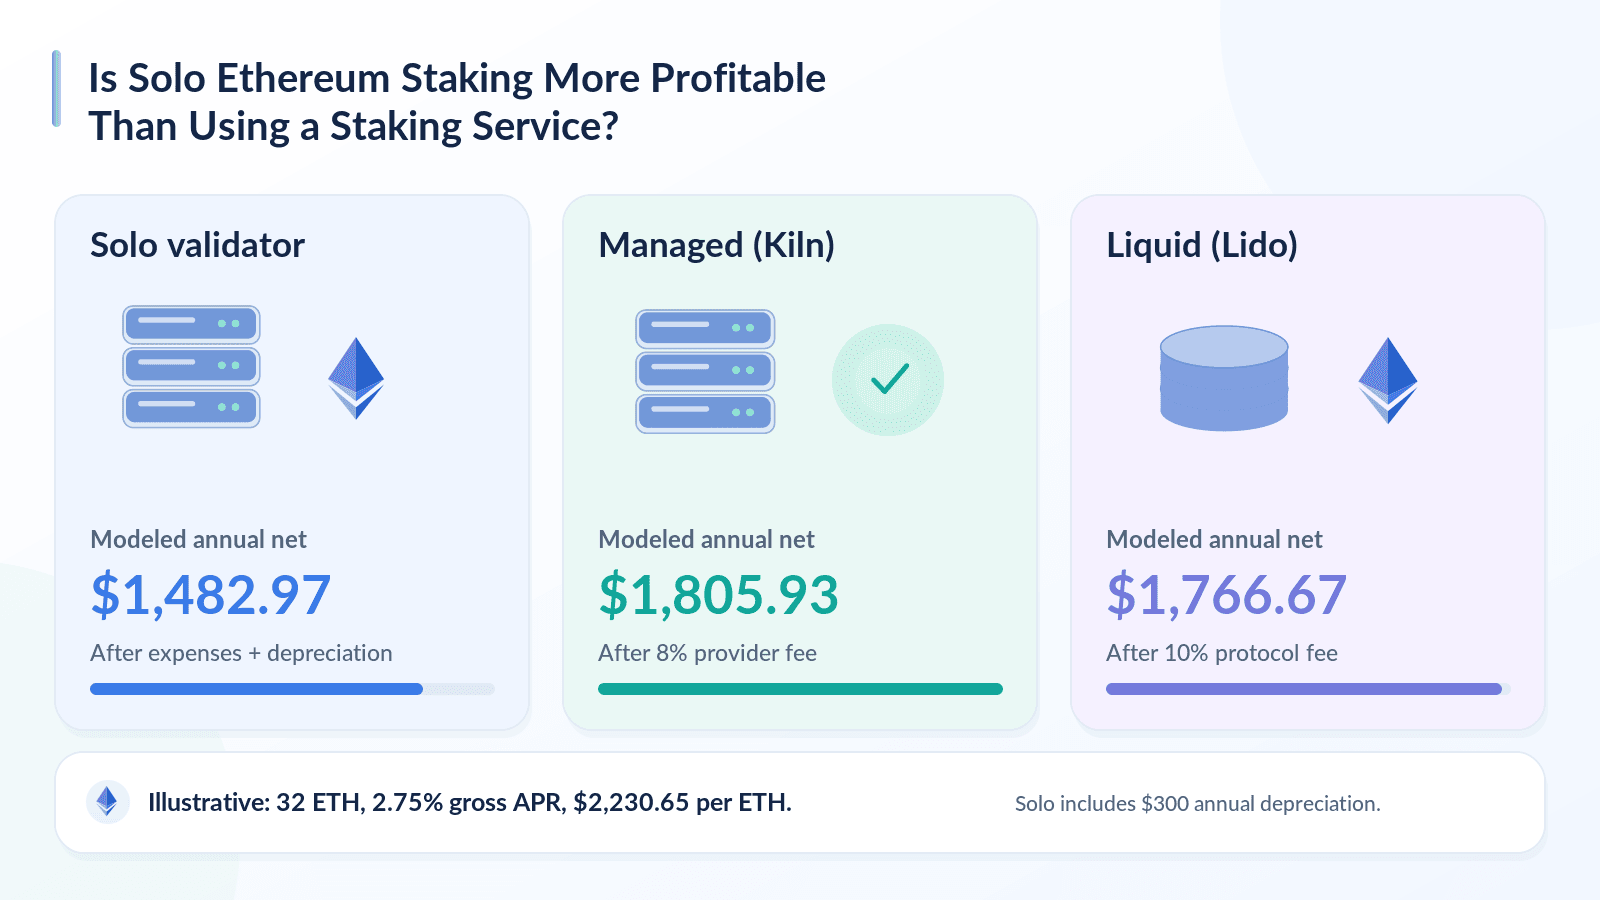 Comparing Solo, Managed, and Liquid Ethereum Staking Returns, Operating Costs, and Hardware Breakeven Periods
Solo Validator vs Managed Staking vs Liquid Staking
Solo operators maintain their own infrastructure and validator software. Managed staking delegates operations to a provider. Liquid staking pools deposits and provides a transferable token representing participation.
Published charges checked Oct. 31, 2026:
| Service Or Route | Published Charge Checked Oct. 31, 2026 |
|---|---|
| Kiln Earn's specified ETH staking route | 8% of total rewards |
| Lido liquid staking | 10% of staking rewards |
| Allnodes validator hosting | Advertised from $5 monthly |
Kiln Earn charges 8% on the specified service, while partner products may differ. Lido's protocol fee can change through governance.
The following model uses 32 ETH, 2.75% gross APR and $2,230.65 per ETH. Annual gross rewards equal 0.88 ETH, valued at $1,962.97.
| Factor | Solo Validator | Managed Example: Kiln Earn | Liquid Example: Lido |
|---|---|---|---|
| Minimum stake | 32 ETH | 32 ETH for the specified route | Below 32 ETH |
| Gross reward assumption | 2.75% | 2.75% | 2.75% |
| Provider commission | None | 8% of rewards | 10% of rewards |
| Personal infrastructure | $180 annually assumed | None assumed | None assumed |
| Annual net before depreciation | $1,782.97 | $1,805.93 | $1,766.67 |
| Annual net after solo hardware depreciation | $1,482.97 | $1,805.93 | $1,766.67 |
| Main exposure | Personal operations and keys | Provider performance and service structure | Contracts, operators and token liquidity |
The model assumes identical gross performance to isolate fees. It excludes taxes, labor, transaction charges and compounding; results are illustrative, not promised returns.
Under these assumptions, solo operation earns $22.96 less annual cash income than the 8%-fee managed route. After depreciation, its annual result is $322.96 lower.
Against the 10%-fee liquid route, solo operation retains $16.30 more annual cash income, but earns $283.70 less after depreciation. Differences use unrounded calculations.
Net staking yields on the $71,380.80 stake are:
| Route | Illustrative Net Yield Before Tax |
|---|---|
| Solo, after operating expenses | 2.4978% |
| Solo, after expenses and depreciation | 2.0776% |
| Managed, after 8% commission | 2.5300% |
| Liquid, after 10% commission | 2.4750% |
Yields use staked ETH as the denominator. They exclude ETH price changes and are not total returns on equipment plus stake.
Managed staking is not universally custodial. Some services operate signing infrastructure while users retain withdrawal control. Others use contracts or custody arrangements that require additional evaluation. Check delegated staking arrangements for signing-key control, exit rights and withdrawal permissions.
Fixed charges can change the outcome further. At the advertised $5 monthly starting price for Allnodes hosting, annual hosting charges would be $60. The same gross-reward model would leave $1,902.97 before other costs. Features, billing and final plan terms require separate evaluation.
How Long Does It Take to Break Even on Ethereum Validator Hardware?
Hardware cost recovery and the added value of self-hosting are different calculations.
Hardware recovery from total staking reward value
Under the main assumptions:
$1,200 ÷ ($1,962.97 − $180) = Approximately 8.1 months
The figure assumes rewards can be withdrawn and sold at the modeled price. It credits all staking income to the hardware, even though the same ETH could earn rewards through a provider.
Incremental self-hosting payback
This calculation measures provider charges avoided, less additional operating costs.
Against the 8% managed fee:
- Annual fee avoided: $157.04.
- Annual operating expenses: $180.
- Incremental cash result: Negative $22.96.
There is no incremental hardware payback under those assumptions.
Against a 10% fee on rewards:
- Annual fee avoided: $196.30.
- Annual operating expenses: $180.
- Incremental cash advantage: $16.30.
- Simple equipment payback: Approximately 73.6 years, using unrounded values.
The 73.6-year payback exceeds the assumed four-year equipment life, even before replacements and the time value of money.
Annual parity after depreciation requires avoided provider charges of $480, covering $180 operating costs and $300 depreciation. That equals approximately 24.45% of modeled gross rewards.
Existing equipment and multiple validators sharing infrastructure improve self-hosting economics. Paid operator time reduces them.
Ethereum Validator Profitability Under Different Market Conditions
These scenarios vary ETH price, APR, expenses and reward realization. They are not forecasts.
The realization factor is a simplified haircut, not an exact model of downtime penalties.
| Assumption Or Result | Lower Case | Illustrative Base Case | Higher Case |
|---|---|---|---|
| ETH price | $1,500 | $2,230.65 | $4,000 |
| Gross APR | 2.00% | 2.75% | 3.50% |
| Reward realization | 95% | 99% | 100% |
| Annual gross reward value | $912.00 | $1,943.34 | $4,480.00 |
| Annual operating expenses | $360 | $180 | $180 |
| Annual depreciation | $300 | $300 | $300 |
| Solo net after both costs | $252.00 | $1,463.34 | $4,000.00 |
| Managed net after 8% fee | $839.04 | $1,787.87 | $4,121.60 |
| Liquid net after 10% fee | $820.80 | $1,749.01 | $4,032.00 |
The same realization factor applies to each route. Real performance, missed duties and penalties vary by operator.
In the illustrative base case, replacing home infrastructure with $1,200 annual cloud hosting leaves $743.34 before taxes and labor. No personal hardware depreciation applies to that rented-server example.
For cost modeling:
Solo net = Reward value − Operating expenses − Depreciation
Provider net = Reward value − Provider charges
Incremental advantage = Solo net − Provider net
Avoided commissions are already reflected in the comparison. Adding them to solo revenue would double-count the benefit.
Can You Run a Profitable Ethereum Node With Less Than 32 ETH?
Bonded protocols let operators contribute less than 32 ETH. Pooled staking requires no personal server.
Running a Bonded Validator Through Rocket Pool
Rocket Pool's Saturn 1 model combines a 4 ETH operator bond with 28 ETH from the staking pool to fund a 32 ETH validator.
A megapool is a smart contract managing one or more validators for an operator. The lower personal bond does not change Ethereum's underlying activation requirement.
Rocket Pool's megapool requirements confirm the structure. Pool matching and validator activation involve queues, so earnings may not begin immediately.
Operator income has two components:
- Bond rewards: Returns attributable to the operator's own ETH.
- Base commission: A share of rewards attributable to matched pool ETH.
Under Saturn 1, the base commission is 5% of rewards from matched ETH. No mandatory RPL collateral is required for megapool validation. Optional RPL staking adds separate rewards and token risk; governance can change these parameters.
Using the same simplified 2.75% annual rate:
| Income Component | Illustrative Annual ETH |
|---|---|
| Rewards on the operator's 4 ETH | 0.1100 |
| 5% commission on rewards from 28 pooled ETH | 0.0385 |
| Combined before operating costs | 0.1485 |
At the assumed $2,230.65 ETH price, combined income is approximately $331.25 annually. After $180 operating expenses, that leaves $151.25. Including $300 depreciation produces a $148.75 modeled loss.
Optional RPL rewards, transaction charges and delays are excluded.
The additional commission compensates the operator for managing pooled funds. Smart-contract, governance and bond-loss risks remain.
Multiple validators sharing infrastructure can improve costs, but require additional capital and operational responsibility.
Is Pooled Ethereum Staking a Better Alternative?
Pooled staking requires no personally operated validator.
Lido's stETH reflects participation through a token balance adjusted by protocol accounting. Rocket Pool's rETH generally accumulates rewards through its protocol exchange rate against ETH. Both tokens carry smart-contract, governance, validator and secondary-market pricing risks.
Exchange staking adds a custodial arrangement. The exchange generally controls assets and operations, with eligibility, fees and withdrawals governed by its terms and regional restrictions.
Holding a liquid staking token is not operating a validator. Our best Ethereum staking pools comparison covers additional routes for readers seeking participation without personal infrastructure.
Compare net rewards, redemption, liquidity and custody before choosing a pool.
What Factors Affect Ethereum Validator Profitability Over Time?
Participation, network activity and protocol upgrades change future rewards and costs.
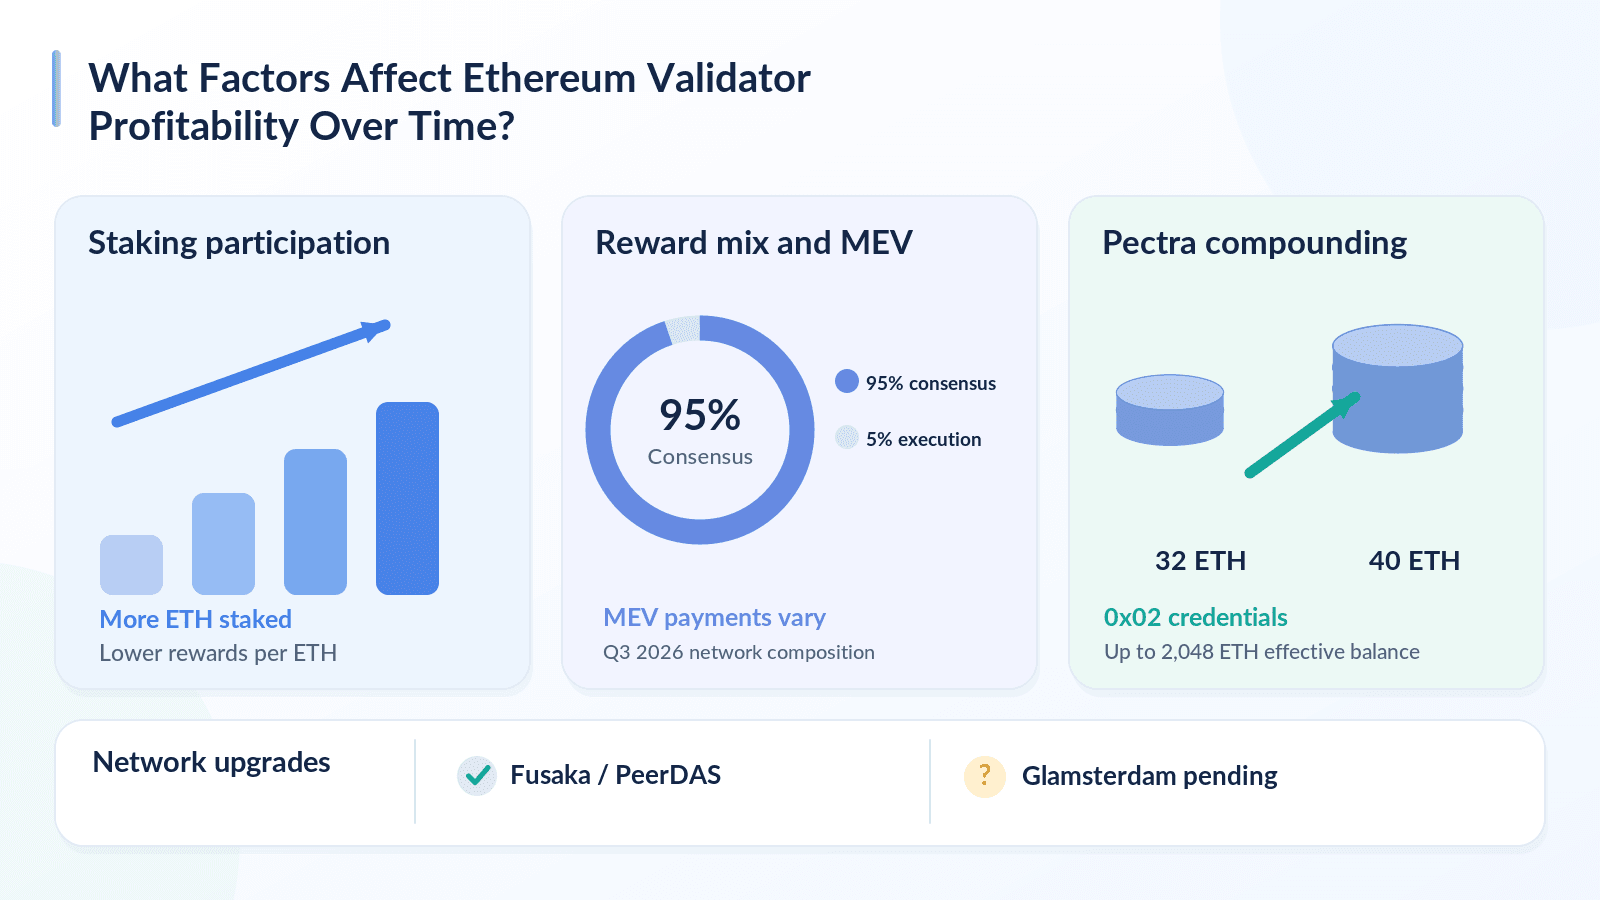 How Network Participation, MEV Rewards, Validator Compounding, and Ethereum Upgrades Influence Long-Term Staking Profitability
Total ETH Staked, Network Activity and MEV Rewards
As network staking participation rises, validator issuance can increase while consensus rewards per ETH generally fall, all else equal. Priority fees and MEV-related payments follow different drivers. Busy periods can lift proposer revenue, while quieter conditions reduce available payments.
Approximately 95% of Q3 2026 rewards came from the consensus layer, with 5% from the execution layer, in Figment's report.
MEV-Boost connects validators with external block builders through relays. Builders compete to supply blocks, and proposers can receive payments reflecting their bids.
Relay infrastructure introduces availability, timing and trust dependencies. Operators also need to consider transaction-filtering policies and the behavior of their selected services.
A single validator still needs a proposal opportunity. Large payments from exceptional blocks are unsuitable as baseline income, even when MEV-Boost improves access to competitive bids.
How Pectra Changed Validator Compounding
Pectra introduced EIP-7251, raising the maximum effective validator balance to 2,048 ETH while retaining the 32 ETH activation minimum.
Effective balance is the stake weight used to determine validator duties and rewards.
| Withdrawal Credentials | Effective-Balance Ceiling | Reward Handling |
|---|---|---|
| Regular 0x01 | 32 ETH | Eligible excess balances are automatically withdrawn |
| Compounding 0x02 | 2,048 ETH | Consensus rewards can increase participating balance |
With compounding credentials, effective balance rises in eligible whole-ETH increments; smaller accrued rewards do not immediately increase the stake used to calculate duties.
An operator with 40 ETH can use a properly funded compounding validator to support a 40 ETH effective balance. A regular validator remains capped at 32 ETH effective balance.
At an unchanged illustrative 2.75% gross rate, 40 participating ETH corresponds to 1.10 ETH annually, compared with 0.88 ETH for 32 ETH.
The additional income comes from additional participating capital. The higher ceiling does not guarantee a higher APR.
Execution-layer payments to a fee-recipient address do not automatically enter the validator balance. Compounding also reduces routine wallet receipts, and manually requested partial withdrawals below the ceiling require an execution-layer transaction and gas.
How Ethereum Network Upgrades Could Affect Future Costs and Rewards
Fusaka went live on Dec. 3, 2025. Its PeerDAS changes introduced data-availability sampling for blobs, the temporary data used by Layer 2 networks.
Sampling reduces the need for every node to download every blob as capacity expands. It does not remove bandwidth requirements or the need to follow current client specifications.
Glamsterdam includes planned proposer-builder separation within Ethereum's consensus protocol. Its design could change builder interfaces and reliance on external middleware.
On Oct. 22, Ethereum postponed Hoodi activation from Oct. 26 without a replacement date. A mainnet date remains unannounced.
Without mainnet implementation and performance data, no reliable estimate of Glamsterdam's reward impact is possible.
What Risks Can Reduce or Eliminate Ethereum Validator Profits?
A modest staking yield can be overwhelmed by operational losses or ETH price declines. Income, capital exposure and withdrawal access need separate assessment.
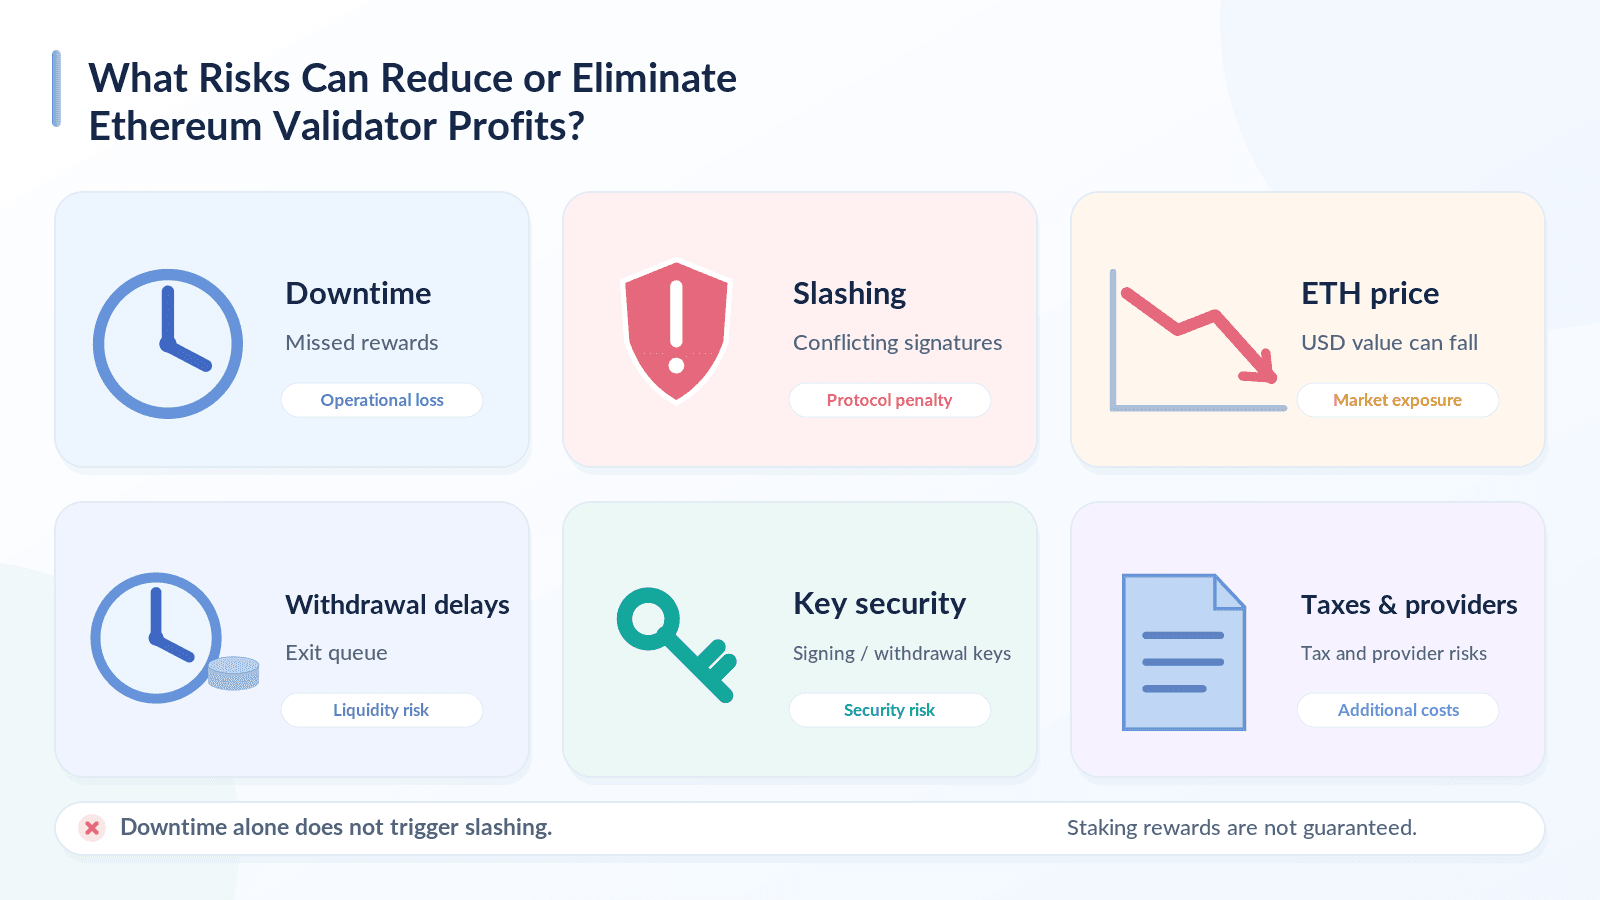 Key Risks to Ethereum Validator Profits, Including Slashing, Downtime, ETH Price Volatility, Withdrawal Delays, and Operational Failures
Downtime Penalties vs Validator Slashing
Temporary downtime causes missed rewards and ordinary penalties for certain missed duties. It does not automatically cause slashing.
Validator slashing applies to conflicting signatures, including signing different blocks for the same slot or making incompatible attestations. It forces a validator toward exit and creates financial losses.
Slashing losses depend partly on the amount of stake slashed at the same time; there is no universal fixed loss.
Running identical validator keys on two active systems can produce conflicting signatures. A backup server therefore requires controlled migration rather than simultaneous signing.
Risk controls include:
- Monitoring: Detect missed duties, disk pressure and client failures.
- Slashing protection: Preserve signing history during migrations.
- Key security: Prevent unauthorized access and duplicate signing.
- Client diversity: Reduce exposure to failures concentrated in one implementation.
During prolonged failure to finalize, network inactivity-leak penalties can be more severe than ordinary outage penalties.
Liquidity, ETH Price and Withdrawal Risks
A validator can earn ETH while losing money in USD terms.
A 10% decline in the assumed value of the original 32 ETH represents $7,138.08, exceeding the modeled $1,962.97 annual gross staking income.
Staking withdrawals access involves processing time and potentially queues. Activation delays postpone initial earnings. Exit requests do not immediately end duties or release funds.
Regular validators receive eligible excess-balance sweeps. Compounding validators retain rewards below their ceiling unless a partial withdrawal is requested. Liquid staking tokens offer a possible market sale before underlying redemption completes. That convenience introduces pricing risk, spreads, slippage and transaction costs.
Do not rely on an immediate exit or a liquid staking token selling at its redemption value to fund near-term expenses.
Taxes, Security and Operational Responsibility
Track reward amounts, dates and fair market values where required. Tax treatment varies by jurisdiction and staking arrangement. Automatic compounding does not necessarily postpone tax obligations.
Our 2027 tax reporting guide covers U.S. filing considerations for 2026 transactions.
Validator keys and withdrawal-account keys perform different roles. Compromised signing keys can enable malicious validator activity. Compromised withdrawal-account keys threaten funds controlled by that account.
Use verified deposit tooling, offline recovery backups and careful address checks. Phishing pages and fake support requests can defeat an otherwise sound setup.
A suitable hardware wallet can protect a compatible withdrawal account. It does not replace the online signing infrastructure required for validator duties.
Operators remain responsible for software updates, client vulnerabilities, storage health and recovery planning. Set useful alerts and a maintenance schedule rather than relying on constant dashboard checking.
Delegation reduces maintenance but adds provider security and continuity risks.
Is Running an Ethereum Node Worth It? Final Verdict
Running an Ethereum validator can produce positive staking income, but operating one yourself is not automatically more profitable than using a staking provider.
At the checked benchmark, the home setup generates positive net staking income. After depreciation, it still trails both provider examples.
| Situation | Recommended Direction |
|---|---|
| Has 32+ ETH, suitable hardware and technical experience | Consider solo validation after comparing full costs against provider charges |
| Has 32+ ETH but wants minimal maintenance | Compare noncustodial managed staking arrangements |
| Has less than 32 ETH and wants to operate infrastructure | Evaluate bonded operation, matching requirements and additional risks |
| Wants rewards without operating a validator | Compare pooled, liquid and exchange staking |
| Wants to support Ethereum without staking capital | Run a non-validating full node |
Solo operation supports Ethereum decentralization and offers direct control, but existing hardware, shared infrastructure or larger avoided fees are needed to improve its financial advantage.