

Liquid staking lets you stake a Proof-of-Stake cryptocurrency while receiving a transferable token that represents the staked position. Instead of waiting for the underlying asset to be unstaked before you can use that capital elsewhere, you can hold, transfer, trade, or potentially use the liquid staking token in DeFi.
Native staking primarily exposes you to the blockchain, validators, and the underlying asset. Liquid staking adds the protocol or issuer, the LST's market liquidity, and any DeFi protocols where you use it.
Editor's Note (Oct. 8, 2026): We fully updated this guide in October 2026 to reflect the liquid staking market in 2026. We added deeper coverage of LST mechanics, including rebasing vs. value-accruing tokens, redemption, secondary-market exits, and depeg risk. We also expanded the risk analysis to cover smart contracts, validators, liquidation, liquidity, concentration, and bridges, alongside a new comparison with native staking and restaking. Protocol examples, fees, market-share data, and U.S. regulatory guidance have also been refreshed.
What Is Liquid Staking? Quick Verdict
Liquid staking lets you stake a Proof-of-Stake cryptocurrency while receiving a transferable token representing your staked position. The underlying asset continues earning staking rewards, while the liquid staking token (LST) can be held, traded, or potentially used in DeFi. This improves liquidity and capital efficiency but introduces additional smart-contract, market, and protocol risks.
Liquid Staking Key Points
-
You receive a token representing your staked assets Protocols issue LSTs such as stETH, rETH, cbETH, mSOL, and JitoSOL. These represent positions linked to underlying staked ETH or SOL and accrued rewards.
-
Staking rewards appear through two main models Rebasing LSTs such as stETH increase wallet balances, while value-accruing tokens such as rETH and JitoSOL increase in value relative to the underlying asset.
-
Liquid does not mean instant redemption You can often sell an LST immediately on secondary markets, but redeeming it through the protocol may involve withdrawal queues, validator exits, or unbonding periods.
-
LSTs can trade below their redemption value Market liquidity, withdrawal delays, selling pressure, and protocol concerns can create discounts. These become especially dangerous when LSTs are used as collateral.
-
Using LSTs in DeFi adds another risk layer Lending, borrowing, liquidity provision, and leveraged strategies can increase capital efficiency but add smart-contract, oracle, liquidation, and potentially bridge risks.
-
Protocol security and exit liquidity outweigh headline APY Compare validator diversification, custody, governance, audits, fees, redemption rules, and secondary-market liquidity before choosing a liquid staking provider.
Disclaimer
Liquid staking involves cryptocurrency price risk, validator risk, smart-contract risk, and potential loss of funds. Staking rewards are variable and not guaranteed. This guide is for educational purposes only and is not financial, investment, tax, or legal advice.
Disclosure
Some links in this guide may be affiliate links. If you choose to use a service through these links, we may earn a commission at no additional cost to you.
What Is Liquid Staking?
Liquid staking lets users stake a Proof-of-Stake cryptocurrency while receiving a transferable token representing the staked position. The underlying cryptocurrency remains committed to staking, while the liquid staking token, or LST, can usually be held, transferred, traded, or used within DeFi.
"Liquid" refers to the tokenized staking position, not to the underlying assets becoming unstaked.
The basic process looks like this:
- You deposit or delegate a stakeable cryptocurrency.
- A liquid staking protocol allocates it to validators.
- You receive an LST representing the position.
- The underlying stake continues generating staking rewards.
- The LST makes the position transferable and usable in DeFi.
Ethereum provides the clearest examples. ETH deposited through Lido can produce stETH, Rocket Pool issues rETH, and Coinbase offers cbETH for eligible staked ETH users. On Solana, prominent LSTs include mSOL from Marinade Finance and JitoSOL from Jito.
When checked on Oct. 8, 2026, DefiLlama tracked 17.19 million ETH in Ethereum LSTs, worth roughly $44.1 billion. That figure covers DefiLlama's tracked ETH LST market rather than all ETH staked on Ethereum.
Liquid staking sits on top of Proof-of-Stake. Validators still perform the underlying consensus work, while the LST changes how the user's economic position is represented and transferred. For detailed study of Proof-of-Stake, go through our analysis on Proof-of-Work vs Proof-of-Stake.
How Does Liquid Staking Work?
Liquid staking separates the underlying staking position from the token users can move around.
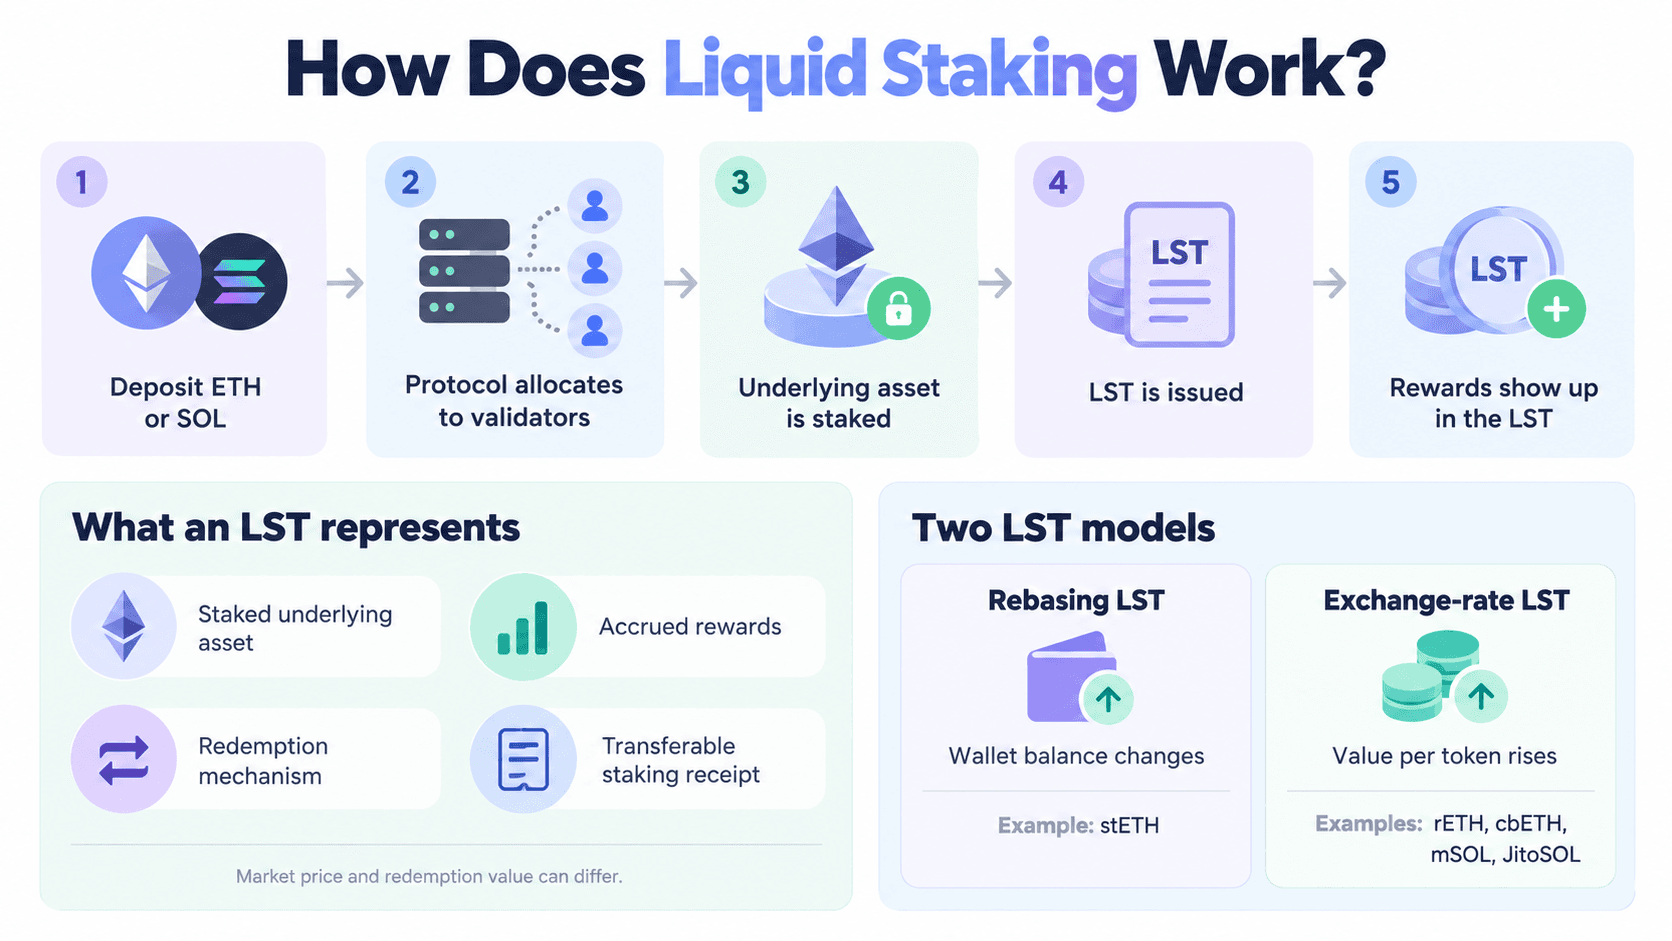
A typical lifecycle follows five steps:
- The user deposits or delegates a stakeable cryptocurrency such as ETH or SOL.
- The liquid staking protocol allocates the cryptocurrency to one or more validators.
- The underlying cryptocurrency participates in network staking.
- The protocol issues an LST representing the user's economic claim on the position.
- Staking rewards appear through either changes in the user's LST balance or an increase in the amount of underlying cryptocurrency represented by each LST.
On Ethereum, the underlying ETH participates in the consensus layer, historically called the Ethereum Beacon Chain. On Solana, liquid staking protocols generally allocate SOL across validators through stake pools or related infrastructure.
An LST is not a second copy of the cryptocurrency that was deposited. The holder has exchanged the unstaked asset for a tokenized claim or receipt-like representation linked to a staked position. Provider structure changes the risk profile. A decentralized smart contract protocol and a centralized issuer such as Coinbase do not create identical custody, governance, or counterparty exposure.
 Liquid Staking Turns Staked Assets Into Transferable Tokens While Preserving Staking Rewards and Redemption Rights
What Does a Liquid Staking Token Represent?
An LST generally represents a claim linked to staked assets and accrued rewards. Depending on its design, that can include:
- The underlying staked cryptocurrency
- Accrued staking rewards
- A mechanism for redeeming the token for the underlying asset
- A transferable staking receipt that can circulate independently of the validator position
An LST's redemption value and secondary-market price are also different concepts.
A protocol might calculate that one LST represents a particular amount of ETH or SOL, while secondary-market buyers and sellers determine its trading price. Supply, demand, liquidity, withdrawal conditions, and perceived risk can push market price above or below redemption value.
Rebasing vs Value-Accruing LSTs
LSTs primarily reflect staking rewards through two accounting models.
Rebasing LSTs are rebasing tokens that change the holder's wallet balance. With stETH, the stETH mechanics update the wallet balance daily as staking rewards accrue.
Value-accruing LSTs use an exchange rate that can rise while the number of tokens in the wallet stays unchanged.
Rocket Pool's rETH mechanics increase the token's value relative to ETH as staking rewards accrue. Marinade Finance's mSOL mechanics increase its value relative to SOL while the holder's token balance stays unchanged. JitoSOL uses a similar exchange-rate model, while cbETH's conversion rate changes as rewards accrue to the underlying staked ETH.
| Model | What Changes? | Example |
|---|---|---|
| Rebasing LST | Token balance | stETH |
| Exchange-rate LST | Value per token relative to underlying | rETH, cbETH |
The distinction affects how rewards appear, how DeFi integrations handle the token, and potentially how transactions are accounted for.
How Do Liquid Staking Rewards Work?
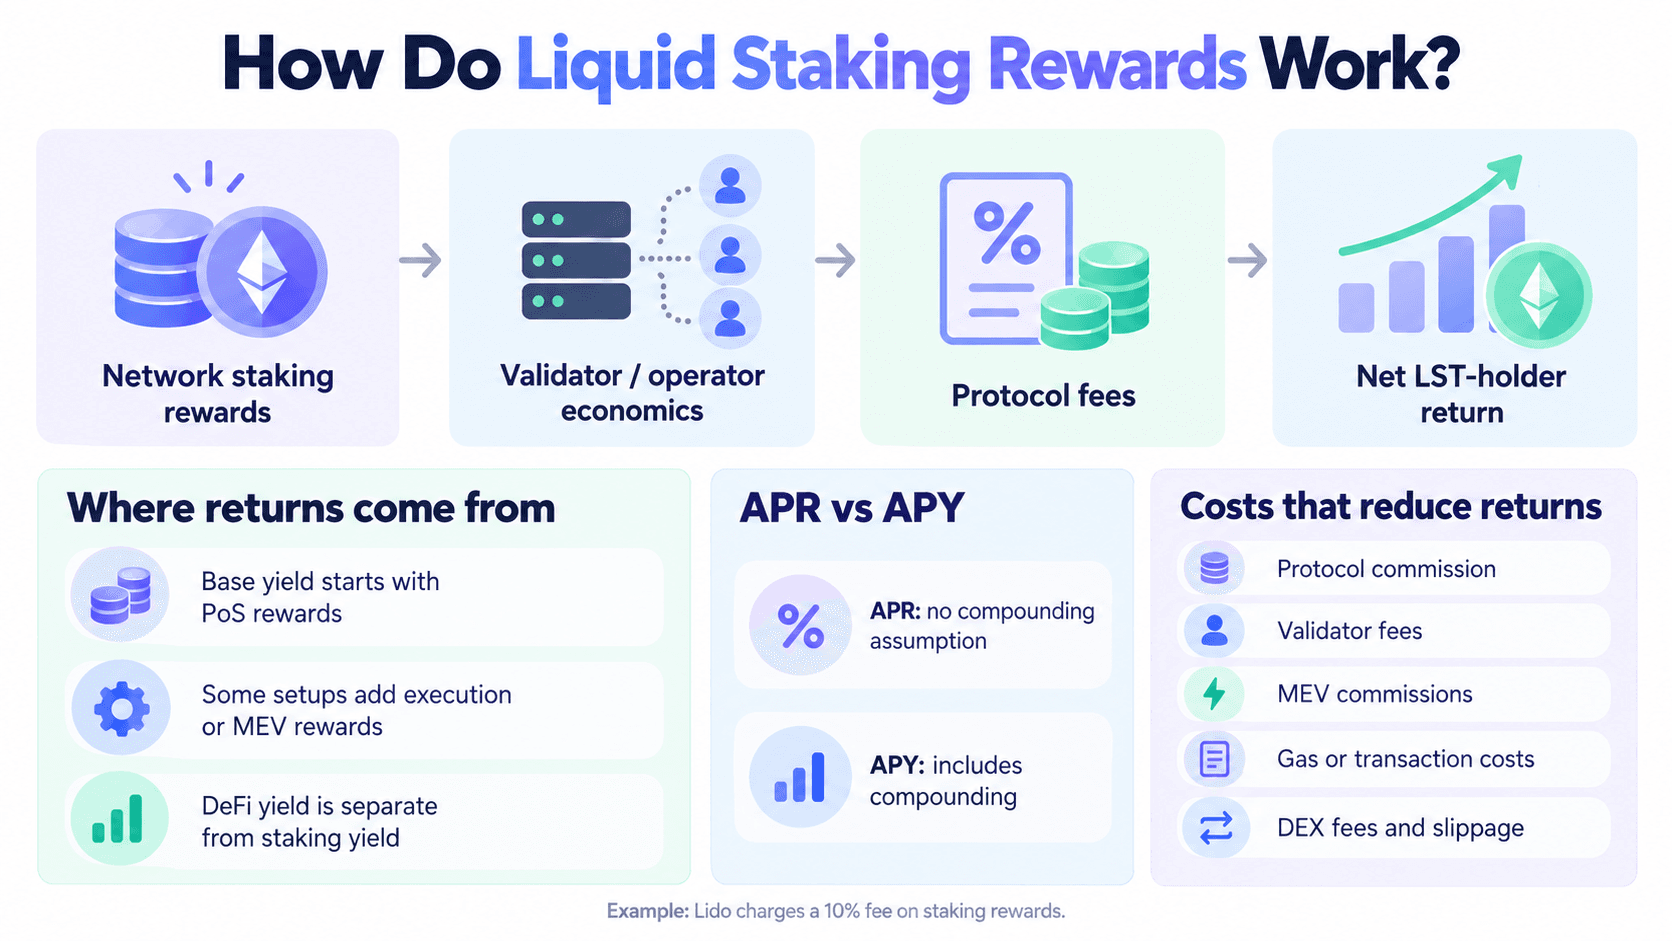
Liquid staking does not create yield from nowhere. The base return generally begins with rewards generated by the underlying Proof-of-Stake network.
The flow can be summarized as:
Network staking rewards -> validator/operator economics -> protocol fees -> net LST-holder return
Validators earn rewards for securing the blockchain. Depending on the network and protocol, operator and protocol fees can reduce the amount reaching LST holders.
Ethereum validator rewards can include consensus rewards and execution rewards. Some staking setups also capture MEV-related revenue. On Solana, JitoSOL rewards include both staking and MEV rewards in the token's appreciating exchange rate. Holders do not need to claim those rewards separately.
Holding an LST can provide exposure to the underlying network's staking rewards. Supplying that LST to a lending market, liquidity pool, leveraged strategy, or another DApp introduces a separate source of return and a separate risk layer. Staking yield and DeFi yield come from different sources and should be evaluated separately.
 Liquid Staking Rewards Come From Network Staking Yield, Minus Validator, Protocol, and Transaction-Related Costs
APR, APY and Protocol Fees
APR and APY describe returns differently.
- APR, or annual percentage rate, generally annualizes a return without assuming compounding.
- APY, or annual percentage yield, incorporates compounding assumptions.
Headline rates are not always directly comparable. One protocol may show APY with compounding while another reports APR. A value-accruing LST can also compound through its exchange rate without adding tokens to the wallet.
Protocol costs can reduce the amount reaching LST holders. Depending on the product, these may include:
- Protocol commission
- Validator or node-operator fees
- MEV-related commissions
- Transaction or gas fees when entering or exiting
- DEX fees and slippage when an LST is bought or sold rather than minted or redeemed
As of Oct. 8, 2026, Lido charges a 10% protocol fee on staking rewards. The fee is taken from rewards rather than the original ETH deposit, with the allocation between node operators and the Lido DAO varying by staking module.
ETH staking yield and SOL staking yield are variable, and validator performance, protocol fees, compounding assumptions, and MEV can change the realized return.
How Do You Exit a Liquid Staking Position?
Liquid staking can provide immediate market liquidity, but it does not necessarily make protocol unstaking instant. There are usually two exit routes: sell the LST to another market participant, or redeem it through the liquid staking protocol.
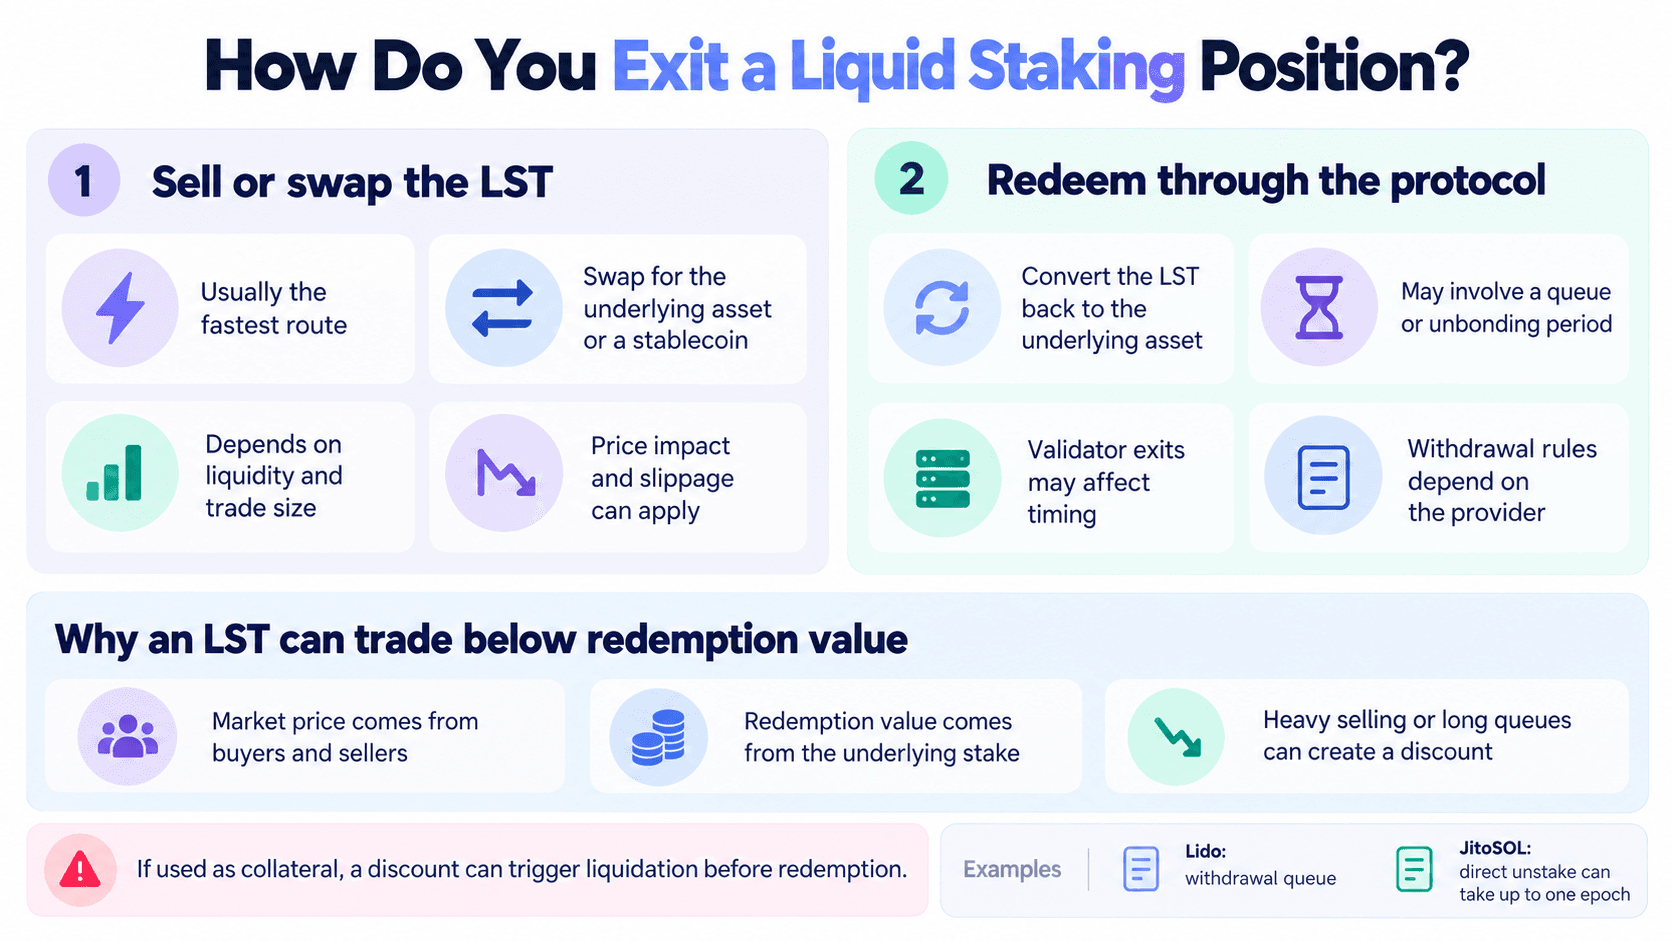 Lst Holders Can Exit by Selling on Secondary Markets or Redeeming Through the Underlying Staking Protocol
Sell or Swap the LST
The fastest route is generally to sell or swap the LST on a secondary market.
A holder might exchange stETH for ETH, JitoSOL or mSOL for SOL, or an LST for a stablecoin through a DEX or centralized exchange. The underlying stake does not have to exit its validator at that moment because another buyer takes ownership of the LST.
Execution depends on:
- DEX or CEX availability
- Available liquidity
- Trade size
- Slippage
- The current LST market price
- Any discount or premium relative to redemption value
Large trades can create more slippage. During heavy withdrawal demand, an immediate sale may also require accepting a discount instead of waiting for redemption.
Redeem Through the Liquid Staking Protocol
The second option is to redeem the LST through its issuer or protocol.
This converts the tokenized position back into the underlying cryptocurrency under rules set by the provider. The process can involve validator exits, an unbonding period, a withdrawal queue, or liquidity already held by the protocol.
Ethereum demonstrates why there is no universal withdrawal time. A validator that fully exits may face an exit queue whose duration changes with network demand. Holders of staking-pool tokens or LSTs instead follow the withdrawal process provided by their staking service.
Lido uses a withdrawal queue that processes requests on a First-In-First-Out basis. Users lock stETH in the WithdrawalQueue contract and receive an unstETH NFT representing the request. Available ETH in the Lido Buffer can fulfill withdrawals, while validators may need to exit if the buffer is insufficient. Queue size, validator exit conditions, and available ETH therefore affect timing.
Solana provides a useful contrast. As of Oct. 8, 2026, JitoSOL holders can use a market swap for immediate liquidity or direct unstaking. Jito's direct unstaking charges a 0.1% fee and can take up to one Solana epoch, or about two days.
Why Can an LST Trade Below Its Redemption Value?
Redemption value comes from the underlying staking position. Market price comes from buyers and sellers.
Suppose an LST represents 1 ETH worth of redeemable underlying assets, but many holders want ETH immediately. If secondary-market liquidity cannot absorb all those sales near redemption value, the LST can trade at a discount.
This is commonly described as an LST depeg, although LSTs are not necessarily designed as fixed-price stablecoins. stETH, for example, can trade at a secondary-market price that differs from ETH.
A discount can reflect liquidity conditions, withdrawal timing, or changing perceptions of protocol risk even when the underlying staked assets remain intact.
The discount becomes more dangerous when an LST is being used as collateral. Falling market value can trigger liquidation before a holder has time to redeem the LST for its underlying assets.
What Can You Do With Liquid Staking Tokens?
The practical appeal of liquid staking is that the staking position becomes transferable and composable. Users can retain staking exposure while gaining options that native staking may not provide.
Keep a Staked Position Transferable
An LST can generally be transferred between compatible wallets or sold without first completing the blockchain's native unstaking process.
That can be useful when a holder wants to exit quickly, transfer a position to another wallet, or change ownership while the underlying cryptocurrency remains staked.
Transferability is most useful when secondary-market liquidity is deep enough for the holder's position size.
Use LSTs in DeFi
LSTs can become building blocks inside DeFi.
Common uses include:
- Lending
- Borrowing
- Collateral
- Liquidity pools
- DEX trading
Lido's wrapped stETH, or wstETH, uses a non-rebasing structure: the wstETH balance stays fixed while its value per token rises as stETH rewards accrue. That design is easier for many smart contracts to integrate than a token whose wallet balance changes.
A user can then supply a supported LST as collateral to a lending protocol such as Aave, keeping exposure to staking rewards while borrowing another asset against it.
The staking position now sits underneath an additional DeFi layer with its own smart contracts, oracles, governance, liquidity, and liquidation rules. Composability expands both utility and dependencies.
Improve Capital Efficiency
Liquid staking can improve capital efficiency because the underlying asset continues participating in staking while the tokenized representation can potentially be used elsewhere.
A long-term holder might keep the LST in a wallet, while another user deploys it into lending, borrowing, liquidity provision, or other DeFi strategies while the underlying stake continues generating rewards. That added capital efficiency also creates more interconnected risk as each additional protocol introduces another dependency.
An LST sitting in a self-custody wallet has a shorter dependency chain than an LST supplied to another protocol. Borrowing against it adds liquidation exposure. Bridging it to another blockchain adds bridge or wrapped-asset risk.
What Are the Risks of Liquid Staking?
Liquid staking combines several risk layers. Some originate with the underlying cryptocurrency or validator, while others appear because a protocol has tokenized the staking position or because the LST is being used elsewhere.
| Risk Layer | What Can Go Wrong |
|---|---|
| Underlying asset | ETH, SOL, or another asset falls in price |
| Validator | Downtime, penalties, or slashing where applicable |
| Liquid staking protocol | Smart-contract exploit or operational failure |
| Governance/operator layer | Excessive control or validator concentration |
| LST market | Discount, thin liquidity, or slippage |
| DeFi integration | Oracle failure or protocol exploit |
| Borrowing/leverage | Liquidation |
| Bridge | Bridge or wrapped-asset failure |
Bridge risk deserves separate attention when an LST moves away from its native network. The resulting position may rely on bridge contracts, wrapped-token infrastructure, or additional issuers that are separate from the original liquid staking protocol.
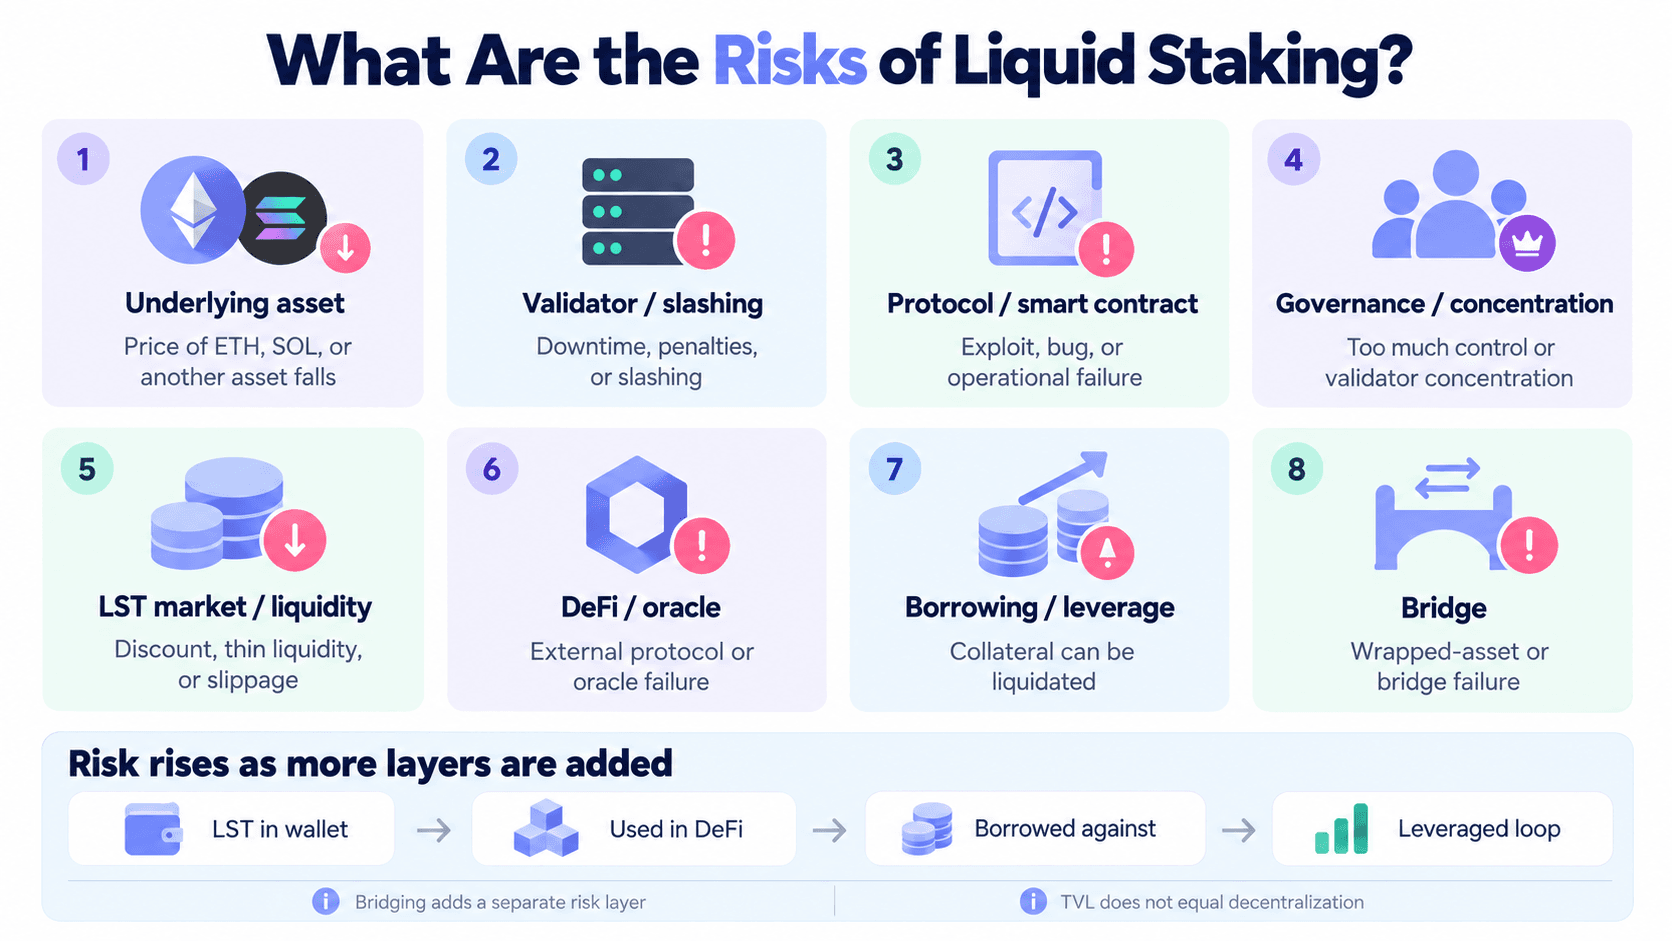 Liquid Staking Adds Smart Contract, Validator, Liquidity, Governance, Defi, Leverage, and Bridge Risks to Staking
Smart Contract and Protocol Risk
Smart contract risk begins with the contracts and infrastructure used to accept deposits, issue LSTs, account for rewards, process redemptions, and coordinate validators.
A vulnerability in a critical component can put funds at risk.
Upgradeability adds another consideration. Users should understand who can change protocol contracts, whether upgrades are subject to governance or timelocks, and which entities control emergency permissions.
Lido and Rocket Pool use protocol-based structures, while cbETH represents ETH staked through Coinbase. Coinbase's cbETH mechanics use a conversion rate that changes as rewards accrue, while the market price can deviate from the value of the underlying staked ETH. The centralized issuer model also introduces custody and counterparty exposure that differs from a decentralized staking protocol.
Security audits show that specialists examined specific code at a point in time. Upgrades and new components can introduce risks outside the reviewed scope.
Validator and Slashing Risk
Poor validator performance can reduce rewards through downtime or penalties. Some Proof-of-Stake networks also impose slashing for specified validator behavior.
The rules differ by blockchain, so slashing should not be treated as identical across Ethereum, Solana, and every other Proof-of-Stake network.
The effect on an LST holder depends on protocol design. Operator bonds may absorb some losses before any residual effect reaches the wider pool, so validator diversification and loss allocation belong in provider selection.
Lido operates several Ethereum staking modules. Its Community Staking Module provides permissionless entry for independent node operators and uses operator bonds as security collateral that can absorb specified penalties and losses.
Rocket Pool's Saturn 1 architecture uses megapools with a 4 ETH bond requirement per validator, illustrating how provider designs can differ materially.
Depeg and Liquidity Risk
An LST can trade below its theoretical redemption value.
Possible causes include:
- Heavy selling
- Thin DEX liquidity
- Long or uncertain withdrawal queues
- Concern about the staking protocol
- Broader market stress
- Forced liquidations involving the LST
A discount becomes more dangerous for leveraged users who cannot simply wait for protocol redemption.
When an LST is used as collateral, lending protocols can rely on oracle or market-derived valuations when assessing the position. A sufficiently large decline can reduce collateral health and trigger liquidation even if the holder expects the LST to recover toward redemption value later.
The risk is not theoretical. On March 10, 2026, an Aave wstETH CAPO risk-oracle configuration problem caused an approximately 2.85% downward deviation in the effective exchange rate and roughly 10,938 wstETH of E-Mode liquidation volume. The Aave post-mortem reported no protocol bad debt.
Market liquidity and protocol TVL should be evaluated separately.
DeFi and Liquidation Risk
Risk escalates as additional financial layers are added:
LST held in wallet < LST supplied to another protocol < LST borrowed against < leveraged staking loop
Holding an LST in a wallet primarily leaves the user exposed to the underlying asset, validator system, liquid staking protocol or issuer, and LST market.
Supplying it to another DApp adds that protocol's smart-contract and oracle risk.
Borrowing against the LST adds collateral and liquidation risk.
A leveraged staking loop goes further. A user might supply an LST as collateral, borrow ETH, convert the borrowed ETH into more LSTs, and repeat the process. Returns can be amplified while borrowing conditions remain favorable, but the buffer against depegs, interest-rate changes, or liquidation becomes smaller.
Multiple yield layers create multiple exposures. The additional return is not the original staking reward being earned twice.
Concentration and Decentralization Risk
Liquid staking can concentrate large amounts of stake within a relatively small number of protocols, governance systems, and validator allocation mechanisms.
As of Oct. 8, 2026, DefiLlama showed Lido at about 56.56% of tracked ETH LSTs, Binance Staked ETH at 21.53%, ether.fi Stake at 11.03%, and Rocket Pool at 3.01%. These figures describe DefiLlama's tracked Ethereum LST market rather than each provider's share of all ETH staked.
Market share is only one part of decentralization.
A large protocol can distribute stake across many operators, while a smaller provider can rely on fewer entities. Governance concentration, validator allocation, upgrade permissions, and operator diversity all affect the risk profile.
Lido's current architecture includes permissionless community staking alongside curated operator routes. Rocket Pool uses a decentralized node-operator network. Coinbase represents a centralized issuer model. Those structures should be evaluated independently from raw TVL.
TVL measures scale, while security and decentralization require separate analysis.
Tax and Regulatory Considerations
Tax treatment can vary by jurisdiction and by the structure of the LST.
Potential questions include whether:
- Depositing ETH or SOL and receiving an LST is treated as a disposal
- Rebasing rewards are treated differently from exchange-rate appreciation
- Staking rewards create taxable income when accrued or received
- Selling an LST creates a taxable event
- Using the LST in subsequent DeFi transactions creates additional reportable transactions
Treatment can differ across stETH, rETH, cbETH, mSOL, JitoSOL, and other products because their accounting and legal structures vary.
In the U.S., the SEC's March 2026 Interpretive Release states that covered protocol staking activities do not involve offers or sales of securities and that qualifying staking receipt tokens tied to non-security crypto assets are not securities under the circumstances described. It built on the Division of Corporation Finance's August 2025 liquid-staking staff statement.
The analysis remains fact-specific. The SEC's September 2026 staff FAQs further address staking receipt tokens, but the staff guidance has no legal force or effect and future legislation, rulemaking, or court decisions can change the treatment.
Users should check current tax and regulatory treatment in their own jurisdiction rather than assuming every LST transaction is treated alike.
Liquid Staking vs Native Staking vs Restaking
Native staking, liquid staking, and restaking all involve staked assets, but they serve different functions.
| Feature | Native Staking | Liquid Staking | Restaking |
|---|---|---|---|
| Primary goal | Secure base blockchain | Stake while tokenizing the position | Extend economic security to additional systems |
| Token received | Usually none | LST | Depends on implementation |
| Liquidity | Lower | Higher | Varies |
| Complexity | Lower | Medium | Higher |
| Extra smart-contract exposure | Limited or depends on method | Yes | Generally greater |
| Typical examples | ETH validator/delegation | stETH, rETH, JitoSOL | EigenLayer-style restaking |
Liquid Staking vs Native Staking
Both native staking and liquid staking remain exposed to the market price of the underlying asset.
If ETH falls sharply, staking rewards do not remove that ETH price exposure. The same applies to SOL and other Proof-of-Stake assets.
Native staking can provide a simpler risk model because there may be no separate LST, secondary market, or liquid staking contract between the staker and the network. The trade-off can be lower liquidity and less DeFi composability.
Liquid staking adds:
- Liquid staking protocol or issuer risk
- Smart-contract risk
- LST liquidity risk
- A market price that can diverge from redemption value
In return, the user receives a transferable representation of the stake.
Readers comparing staking assets rather than liquid staking protocols can use Coin Bureau's staking coin guide, which covers staking mechanics, withdrawal conditions, and major Proof-of-Stake networks.
Liquid Staking vs Restaking
Liquid staking tokenizes a staking position. Restaking reuses staked economic security to support additional systems, while liquid restaking tokenizes a restaked position through a liquid restaking token, or LRT. LST and LRT are not synonyms.
EigenLayer is a prominent Ethereum example. ETH or supported LSTs can be restaked to support external services, adding operator, governance, slashing, and smart-contract exposure. Coin Bureau's EigenLayer review covers those mechanics and risks in more detail.
How to Choose a Liquid Staking Protocol
Choosing a liquid staking protocol requires more than finding the highest displayed APY. The provider shapes stake allocation, rewards, the LST design, and the exit process.
Evaluate the following:
- Supported blockchain: Confirm that the protocol supports the asset you want to stake.
- LST design: Check whether rewards arrive through rebasing or a changing exchange rate.
- Validator decentralization: Understand how stake is distributed among operators and validators.
- Security audits: Check what was audited, when, and whether major components have changed since.
- Smart-contract design: Review upgradeability, permissions, withdrawal contracts, and other critical dependencies.
- Protocol governance: Identify who can change fees, contracts, validator policies, and other parameters.
- TVL: Use total value locked as an indication of scale, not proof of safety.
- LST market liquidity: Check whether secondary markets are deep enough for the position size you may eventually need to exit.
- Redemption mechanism: Understand exactly how the LST becomes the underlying cryptocurrency again.
- Withdrawal time: Check for validator exits, unbonding periods, queues, or other delays.
- Protocol fees: Compare how much of the underlying staking rewards reaches the holder.
- Net staking yield: Compare returns after protocol and validator economics rather than focusing only on gross network yield.
- DeFi integrations: Strong integrations can increase utility but also make it easier to stack additional risk.
- Custodial vs non-custodial design: Identify who controls the underlying assets and what counterparty exposure you are accepting.
A high headline yield is a poor trade for an unclear security model or exit route.
Current Liquid Staking Examples
Liquid staking spans decentralized protocols, permissionless validator models, centralized issuers, and Solana stake pools. Similar-looking tokens can represent different structures.
| Network | Protocol/Issuer | LST | Useful Distinction |
|---|---|---|---|
| Ethereum | Lido | stETH | Rebasing ETH LST |
| Ethereum | Rocket Pool | rETH | Value-accruing LST, decentralized node model |
| Ethereum | Coinbase | cbETH | Value-accruing LST from a centralized issuer |
| Solana | Marinade Finance | mSOL | Value-accruing SOL LST |
| Solana | Jito | JitoSOL | SOL LST incorporating staking and MEV rewards |
stETH uses a rebasing model, while rETH increases in value relative to ETH as staking rewards accumulate. cbETH also uses a changing conversion rate, but its centralized issuer and custody model creates a different risk profile.
On Solana, mSOL and JitoSOL use value-accruing designs. mSOL reflects staking rewards through its exchange rate, while JitoSOL combines SOL staking rewards with MEV-related rewards.
Security architecture, validator distribution, liquidity, fees, governance, redemption, custody, and intended use are more useful selection criteria than headline yield alone.
How to Start Liquid Staking
The transaction itself is simple. The due diligence should happen before the deposit.
- Choose the asset you want to stake. Start with the blockchain, such as Ethereum or Solana, rather than choosing an LST purely because its displayed yield is higher.
- Compare liquid staking protocols available on that network. Review security architecture, validator allocation, governance, custody, and track record.
- Check the LST's reward model, fees, liquidity, and redemption process. Know whether the token rebases or increases in value against the underlying asset.
- Use the protocol's official interface or another verified route. Avoid unsolicited links, fake DApps, and unfamiliar token contracts.
- Connect a compatible crypto wallet. MetaMask is a common Ethereum wallet, while Phantom and Solflare are widely used Solana wallet options. Coin Bureau's crypto wallets guide covers current self-custody choices, DApp access, and security trade-offs.
- Start with a small amount. Confirm the staking deposit, transaction fee, gas fee, and token received before committing a larger position.
- Verify the LST received. Check that the LST contract address or token mint matches the protocol's official information.
- Understand the exit route before using the LST elsewhere. Check both secondary-market liquidity and protocol redemption.
- Monitor protocol changes, validator performance, and LST liquidity. Governance changes, contract upgrades, fee adjustments, and changing market liquidity can alter the risk profile after the initial deposit.
Never identify an LST solely by its ticker. Anyone can create a token carrying a familiar name or symbol, so verify the contract address on Ethereum and other EVM networks, or the token mint on Solana, against the protocol's official information.
Closing Thoughts: Is Liquid Staking Worth It?
Liquid staking is most useful when the liquidity serves a purpose, allowing a long-term holder to preserve staking exposure through a transferable token while accepting smart-contract risk, liquidity risk, governance risk, and market-structure risk. The decision should start with what you intend to do with the LST and your risk tolerance.
Liquid staking may make sense if:
- You want staking exposure while retaining a transferable position.
- You expect to use the LST in DeFi.
- You understand the protocol and token's redemption model.
- The LST has strong secondary-market liquidity for your expected position size.
- You accept the additional smart-contract and market-structure risk.
Liquid staking may not make sense if:
- You only want the simplest possible staking exposure.
- You have no intention of using the LST.
- Minimizing smart-contract exposure is your priority.
- The token has weak secondary-market liquidity.
- You cannot explain how an additional DeFi strategy generates its return.
- You cannot tolerate temporary discounts between the LST and the underlying asset.
Liquid staking trades some simplicity for liquidity and composability. Whether that trade is worthwhile depends less on the headline yield and more on what you intend to do with the LST and which additional risks you are willing to accept.