A centralized exchange (CEX) is a cryptocurrency exchange operated by a company that usually takes custody of customer crypto and executes trades through its own systems. A decentralized exchange (DEX) uses blockchain-based infrastructure such as smart contracts, liquidity pools or onchain order books, allowing users to trade from a self-custody wallet without first depositing assets into a conventional exchange account.
That distinction still anchors the CEX vs DEX debate, but the market around it has changed. DEXs now span automated market makers, concentrated-liquidity pools, aggregators, order books and sophisticated perpetual platforms. Centralized exchanges remain the main bridge between fiat and crypto and still account for most trading activity, while onchain execution has taken meaningful market share. The practical choice comes down to custody, execution quality, total cost, liquidity, recovery, privacy and the risks a user is prepared to manage.
We will compare which model makes more sense for beginners, active traders, large orders, self-custody users and traders who move between centralized and onchain markets.
Editor's Note (September 8, 2026): We fully updated this guide in September 2026 to reflect the current CEX and DEX landscape. The refresh adds current market data and expands coverage of modern DEX models, including aggregators, onchain order books and perpetual platforms. We also strengthened the sections on trading costs, liquidity, large trades, Proof of Reserves, recovery, KYC, privacy, the Travel Rule and CEX-to-DEX workflows, while updating the security discussion to separate custody and counterparty risk from smart-contract, wallet, bridge and execution risks.
CEX vs DEX: Quick Verdict
CEXs are generally better for fiat purchases, cashing out, account recovery, deep liquidity in major markets and users who want simpler trading infrastructure. DEXs are generally better for self-custody, direct onchain access, DeFi and trading tokens that may never reach a major centralized exchange.
Neither model is universally safer or cheaper. A CEX concentrates custody and counterparty risk around an operator, while a DEX shifts more responsibility toward smart contracts, wallet security and transaction execution.
CEX vs DEX Key Points
-
CEXs simplify fiat access Centralized exchanges generally work well for buying crypto with fiat, cashing out to a bank, trading major pairs and accessing account recovery or customer support.
-
DEXs keep transaction control with the user Decentralized exchanges let users trade from self-custody wallets and access DeFi, onchain assets and permissionless markets without first depositing crypto into a conventional exchange account.
-
CEX and DEX risks are different CEX users face custody and counterparty risk, while DEX users face smart-contract, wallet, token-approval and transaction-execution risks.
-
Neither model is automatically cheaper CEX costs can include trading fees, spreads and withdrawal charges, while DEX costs can include swap fees, gas, price impact, slippage and MEV.
-
Using both can cover different jobs A CEX can handle fiat access and account-based trading, while a wallet and DEX can handle self-custody, onchain execution and DeFi access.
Disclaimer
This guide is for educational purposes only and is not financial advice. Crypto trading involves substantial risks, including market volatility, loss of funds, exchange counterparty risk, smart-contract vulnerabilities, wallet compromise and irreversible blockchain transactions.
Disclosure
Some links in this guide may be affiliate links. If you choose to use a service through these links, we may earn a commission at no additional cost to you.
Centralized vs Decentralized Exchanges At A Glance
Control separates the two models. A CEX inserts an exchange operator between the trader and the market, while a DEX generally lets the trader retain signing authority over assets while accessing blockchain-based liquidity.
| Comparison Factor | CEX | DEX |
|---|---|---|
| Asset custody | Exchange | User |
| Trade execution | Centralized matching system/order book | Smart contracts, AMMs, order books or routed liquidity |
| Settlement | Often internal until withdrawal | Onchain |
| Fiat support | Strong | Usually indirect |
| KYC | Common | Usually not required at protocol level |
| Liquidity | Usually stronger for major pairs | Varies considerably |
| Trading costs | Trading fee + spread + possible withdrawal cost | Swap fee + gas + price impact + possible MEV |
| Token access | Curated listings | Much broader |
| Account recovery | Usually available | Depends on wallet recovery model |
| Customer assistance | Usually available | Interface support may exist, but transactions cannot normally be reversed |
| Main risk | Custody and counterparty risk | Smart contract, wallet and execution risk |
| Best for | Fiat, beginners, frequent trading | Self-custody and onchain trading |
Platforms such as Binance, Coinbase and Kraken represent the conventional custodial exchange model. Uniswap is one of the clearest examples of wallet-based decentralized trading, although newer DEX architectures increasingly resemble professional exchange infrastructure.
In July 2026, the DEX-to-CEX spot-volume ratio reached a record 24%, meaning DEX volume was roughly one-quarter of CEX volume rather than 24% of combined spot trading. Meanwhile, CoinGecko found that DEXs accounted for 10.2% of perpetual trading volume in January 2026, up from 2.0% in January 2024. CEXs still process the majority of both markets, but DEXs have moved well beyond niche usage.
For users trying to separate the exchange decision from the custody decision, our crypto exchange vs wallet guide explains where exchange accounts and self-custody wallets fit.
How Centralized and Decentralized Exchanges Work
A CEX and DEX can produce the same visible outcome, such as swapping ETH for USDC, while moving and settling assets in very different ways. Following the transaction makes that difference much clearer.
How a Centralized Exchange Works
A centralized exchange takes the user's deposit and trade into its own account infrastructure before an external blockchain transaction becomes necessary.
The basic lifecycle is:
Deposit fiat/crypto → exchange credits account balance → order enters matching engine → trade settles on exchange ledger → user withdraws crypto if desired
When crypto is deposited into a custodial exchange, the customer normally stops controlling the private keys associated with those assets. The CEX manages custodial wallet infrastructure and records each customer's balance through an internal ledger.
Trading then happens inside the exchange. An order book contains bids from buyers and asks from sellers at different prices. The matching engine compares those orders and executes compatible trades, usually according to rules such as price and time priority.
Suppose a trader sells 1 ETH for USDC. The exchange does not need to create an Ethereum transaction transferring that exact ETH between two customer wallets. It can reduce one internal ETH balance, increase another and make the corresponding USDC adjustments in its own ledger.
Blockchain settlement normally reappears when assets enter or leave the exchange. A crypto withdrawal requires the CEX to create an onchain transaction from its custody infrastructure to an address supplied by the customer.
This architecture allows centralized venues to process large numbers of trades without putting every buy and sell directly onto a blockchain.
How a Decentralized Exchange Works
A decentralized exchange generally leaves transaction authorization with the user's wallet and uses smart contracts or other blockchain-based infrastructure to execute the trade.
The equivalent lifecycle is:
Connect wallet → request quote → approve/sign transaction → smart contract executes trade → blockchain settles transaction → assets remain under the user's wallet control
A user may first need to approve a token for use by a smart contract. The wallet then signs the swap or trading instruction. That signature authorizes a specific blockchain action without handing the DEX the user's private key. The transaction may also require a gas fee paid in the blockchain's native fee asset.
This is the operational basis of self-custody. Transaction authorization stays with the wallet rather than an exchange account administrator. The execution mechanism depends on the DEX. An AMM can execute against a liquidity pool. An order-book DEX can match bids and asks. An aggregator can route the same transaction through several pools or market makers.
DEX users therefore do not necessarily trade "directly with another user." The other side of the trade can effectively be a liquidity pool, an onchain order book, a professional market maker or a combination of several liquidity sources.
DEXs Are No Longer Just AMMs
DEX now describes a broad category of onchain trading systems rather than one execution model. Automated market makers (AMMs) remain an important branch. Liquidity providers deposit assets into pools, while mathematical rules determine how those pools price trades.
Concentrated-liquidity AMMs make that capital more targeted. Uniswap v3 introduced the ability for liquidity providers to choose specific price ranges instead of supplying liquidity across every possible price. Uniswap v4 retained concentrated liquidity while expanding pool customization through hooks. Uniswap's comparison of its protocol versions shows how the execution model has developed beyond the original AMM design.
Other DEXs use order books. Hyperliquid, for example, operates a fully onchain order book where orders are matched using price-time priority. The trading experience is consequently much closer to a professional centralized exchange than to an early token-swap interface.
DEX aggregators solve another problem: fragmented liquidity. Jupiter can search across multiple Solana execution sources rather than forcing the trader to select one pool. Its Meta-Aggregator lets different routing engines and RFQ liquidity compete, with a workflow built around getting an order, signing it and executing it.
Intent-based systems abstract the process further. Instead of specifying every step of execution, the trader states the desired outcome. Solvers or competing execution systems then determine how to achieve it.
Perpetual DEXs add another branch by bringing leverage, Funding Rates and derivatives into onchain markets. AMMs, concentrated-liquidity pools, order books, aggregators, RFQ systems, perpetual platforms and solver-based protocols can therefore all sit under the DEX umbrella in 2026.
CEX vs DEX Fees: Which Is Actually Cheaper?
Neither CEXs nor DEXs are automatically cheaper. Comparing only an advertised trading fee ignores spreads, network costs, price impact and other expenses that can change the final execution price substantially.
The Real Cost of Trading on a CEX
The useful CEX formula is:
Total CEX cost = trading fee + spread + slippage + deposit/withdrawal costs where applicable
Professional order-book interfaces commonly use maker and taker fees. A maker order is one that rests on the book and adds liquidity. A taker order executes immediately against liquidity already available. A limit order does not automatically receive a maker fee. If it crosses the order book and executes immediately, it can still take liquidity.
The bid-ask spread creates another cost. An immediate buyer typically pays the best available ask, while an immediate seller receives the highest available bid. Wider spreads increase the distance between those prices.
Slippage becomes relevant when the liquidity available near the market price cannot fill the entire order. A large market order can consume several price levels and end with a worse average execution price than the first price displayed.
Simple-buy interfaces complicate the picture further. Some platforms quote an all-in purchase price containing a spread and/or service fee, while their advanced trading interface uses explicit maker and taker pricing.
Crypto withdrawals can then add another fee. Fiat funding and withdrawal methods may carry their own charges. Our crypto trading guide goes deeper into order books, market orders, limit orders and spreads.
The Real Cost of Trading on a DEX
The equivalent DEX formula is:
Total DEX cost = swap fee + gas + price impact + slippage + possible adverse MEV + bridge/approval costs where applicable
These are cost categories rather than a strict accounting equation. Price impact may already be reflected in a quoted execution price, so it should not always be added again when calculating realized slippage.
Swap fees generally compensate liquidity providers, the protocol or both. The exact structure varies by venue and pool. Gas is separate. On Ethereum, gas measures the computational work required to execute an operation. The network calculates transaction cost from the gas consumed and the price paid per unit of gas, with base and priority fees forming the current fee structure.
Gas does not usually scale in direct proportion to the dollar value of a trade. A $2 network cost represents 2% of a $100 trade but only 0.02% of a $10,000 trade. Network costs can therefore weigh much more heavily on smaller transactions.
Layer 2 networks and lower-cost chains change that calculation considerably. Solana, for example, has a very different network-fee environment from Ethereum mainnet.
Price impact is the change in execution price caused by the trade itself consuming available liquidity. Slippage is the difference between the quoted or expected result and the final execution result as market conditions or available liquidity change.
MEV introduces another possible execution cost. Some forms of transaction ordering can work directly against traders. Ethereum's documentation notes that users caught in sandwich trading can face increased slippage and worse execution.
Cross-chain transactions can add bridge costs, while interacting with a token or protocol for the first time may require a separate approval transaction. Cheap networks, deeper pools and better aggregation mean DEX execution can be much more competitive than older CEX-versus-DEX comparisons suggest.
When Is a CEX or DEX Cheaper?
Trade size + trading pair + blockchain + liquidity + execution method determine the cheaper venue.
| Trade Scenario | CEX Cost Profile | DEX Cost Profile | What To Compare |
|---|---|---|---|
| $100 trade | Often competitive because internal trading avoids an onchain fee for each trade | Can be extremely cheap on low-cost chains, while fixed network costs can weigh heavily elsewhere | Gas, spread, simple-buy markup, trading fee |
| $10,000 trade | Deep CEX books can provide strong execution on major pairs | Aggregation and deep liquidity pools can be highly competitive | Effective spread, price impact, routing, gas |
| $100,000 trade | Major CEX books and OTC/RFQ liquidity can limit price impact | Deep pools, aggregators and RFQ systems can compete on some pairs | Executable price, depth, MEV, routing and fees |
The useful comparison is the amount received after execution rather than the fee percentage advertised before the trade.
Are DEXs Safer Than Centralized Exchanges?
DEXs remove centralized custody risk, but they introduce different risks rather than eliminating risk. The useful security question is what can cause a loss and whether the user has any recovery path afterward.
| Failure Mode | CEX Exposure | DEX Exposure |
|---|---|---|
| Exchange insolvency | High | Usually absent at protocol level |
| Exchange wallet hack | Relevant | Usually absent as a pooled exchange-custody risk |
| Account takeover | Relevant | Replaced largely by wallet compromise |
| Smart contract exploit | Limited for basic custodial trading | Major risk |
| Malicious token approval | Usually limited | Major risk |
| Phishing | Account credentials | Wallet signing and approvals |
| Withdrawal freeze | Possible | Onchain settlement usually has no customer-support reversal |
| MEV/sandwiching | Usually hidden from the user's exchange execution | Relevant on some public onchain trades |
| Lost recovery credentials | Exchange may provide recovery | Can result in permanent loss |
| Scam tokens | More filtered through listings | More common in permissionless markets |
For users comparing individual custodial platforms rather than CEXs as a category, our safest crypto exchanges guide looks at custody, account protection, reserve transparency, regulation and withdrawal resilience.
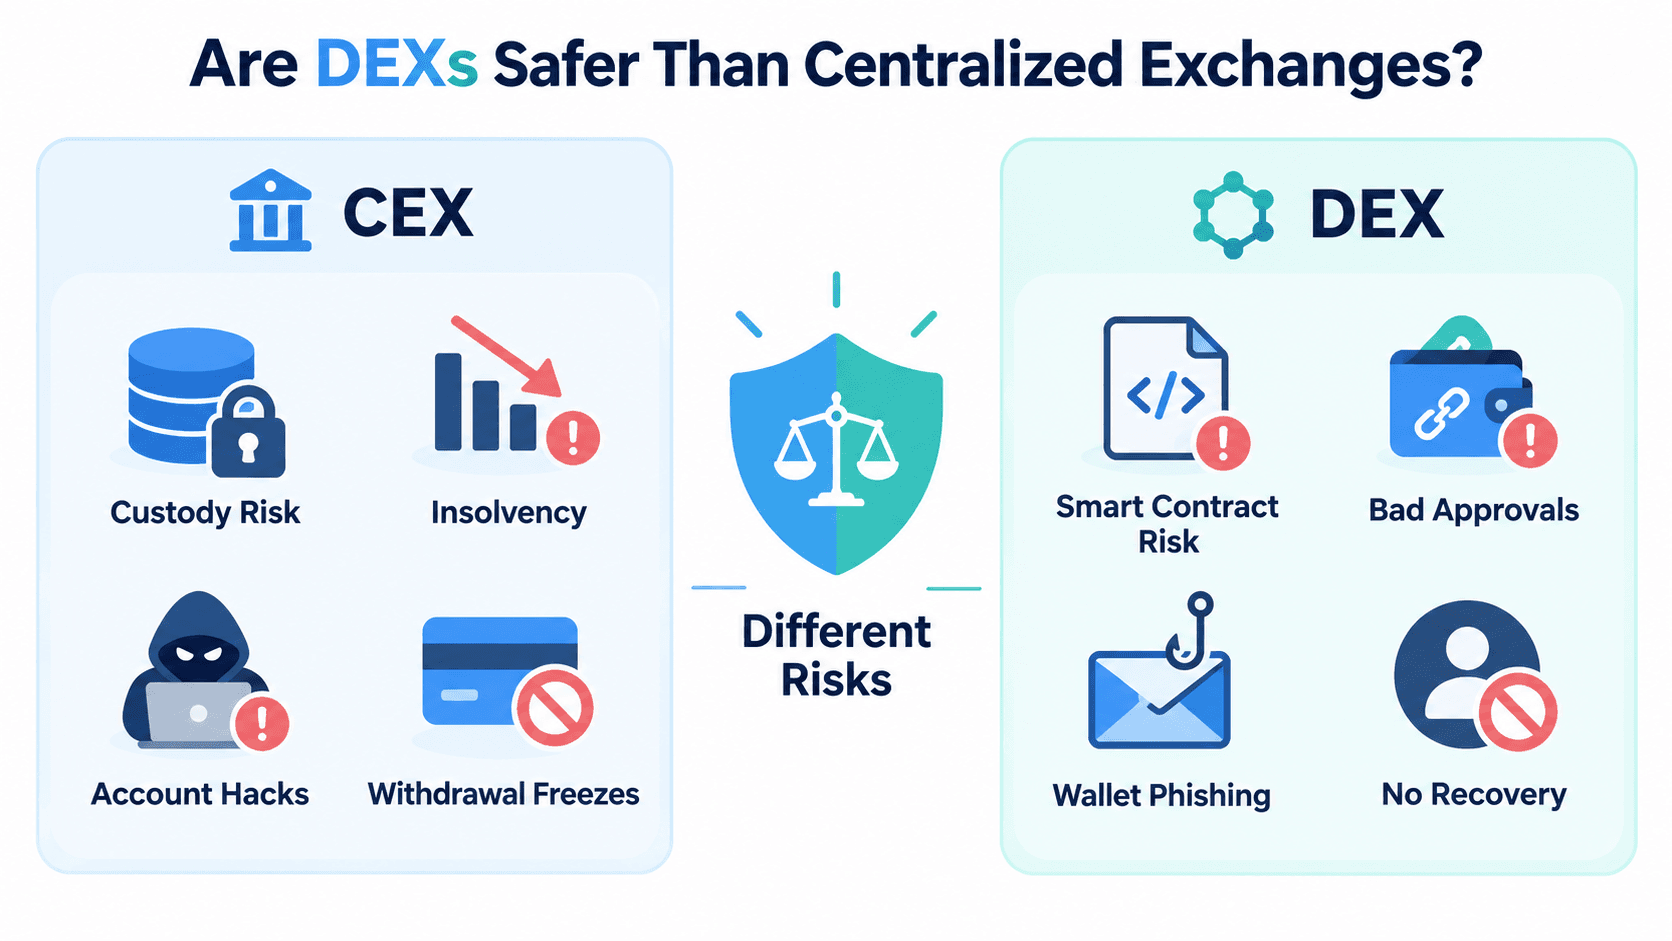 Different Exchange Models Create Different Security Failure Points
Centralized Exchange Risks
The defining CEX risk is counterparty exposure. Customers depend on the operator to safeguard assets, keep accurate records and honor withdrawals.
The major failure modes are:
- Exchange hacks: Attackers may compromise hot wallets, signing systems, internal infrastructure or employee access. The concentration of customer assets can make a large exchange a valuable target.
- Account takeover: Stolen credentials, compromised email accounts or weak authentication can give an attacker control over an individual exchange account. Two-factor authentication can reduce this risk but cannot protect against a failure of the exchange itself.
- Insolvency: An account balance is an internal claim. If an exchange lacks enough liquid assets to satisfy customer obligations, the numbers shown in customer accounts may exceed what can actually be withdrawn.
- Misuse of customer assets: Lending, commingling or otherwise deploying customer funds can create losses or liquidity gaps if the operator's controls fail.
- Withdrawal freezes: Security incidents, liquidity problems, blockchain maintenance or regulatory action can temporarily block access to funds.
- Operational outages: A platform can become unavailable during volatile markets, preventing traders from managing positions when execution is most time-sensitive.
- Regulatory and account restrictions: Compliance reviews, sanctions rules or jurisdictional restrictions can limit withdrawals, trading or access to particular products.
These risks feed into counterparty risk because the customer must rely on an organization continuing to function as promised.
DEX Risks
DEX users remove much of the conventional exchange-custody exposure, but the attack surface moves toward code, wallets and individual transaction authorization.
The major failure modes are:
- Smart contract exploits: Bugs in protocol code can allow assets held by affected contracts or liquidity pools to be drained or manipulated.
- Malicious token approvals: An unsafe approval can give a contract authority to transfer tokens from the user's wallet. The transaction may look routine while granting much broader permissions than intended.
- Wallet phishing: Fake interfaces, malicious links and impersonated support accounts can trick users into revealing recovery information or signing harmful transactions.
- Scam and honeypot tokens: Permissionless markets can contain fake assets, impersonation tokens or contracts designed to make buying easy and selling difficult.
- Oracle attacks: Protocols that depend on price feeds can fail when those inputs are manipulated or behave unexpectedly.
- MEV and sandwich attacks: Transaction ordering can produce worse fills for users whose trades are visible before execution.
- Compromised front ends: The underlying protocol contracts can remain intact while a website or interface used to access them is compromised.
- Bridge exploits: Cross-chain trading can introduce another layer of smart contracts, validators, relayers or signers that can fail independently of the DEX.
- Wrong transaction signing: A valid signature can authorize a malicious or unintended action. Blockchain settlement does not know that the user misunderstood what was being signed.
DEXs remove the pooled customer custody found at centralized exchanges, but smart-contract, wallet, interface and transaction risks remain.
Proof of Reserves Does Not Equal Proof of Solvency
Proof of Reserves can improve exchange transparency, but it does not automatically establish that an exchange is solvent.
A PoR process can demonstrate that an exchange controls specified crypto assets at a particular point in time. Merkle trees can also let customers verify that their balances were included in the liability dataset without publicly exposing every account.
Kraken provides a practical example. Its June 30, 2026 Proof of Reserves snapshot showed reserve ratios above 100% for the assets included on its public verification page.
The limitation is scope. Reserves represent one side of the financial picture. Solvency also depends on liabilities, so Proof of Reserves without sufficiently complete proof of liabilities cannot establish the company's full financial position.
A PoR report therefore does not automatically answer several other questions:
- Does the exercise capture all customer liabilities?
- Does the company have material corporate liabilities outside that dataset?
- Are assets pledged or subject to competing claims?
- What happens between snapshots?
- Are customer assets legally segregated from company assets?
- Has the wider financial position been independently audited?
Proof of Reserves is useful evidence. A complete judgment needs liabilities, custody arrangements, financial controls, withdrawal history and, where available, broader audit or regulatory information.
Recovery Is Also Part of the Security Trade-Off
Recovery changes the meaning of security because greater control can also mean fewer ways to reverse an ordinary mistake.
| Problem | CEX | DEX/Self-Custody |
|---|---|---|
| Forgotten password | Usually recoverable | Wallet password recovery depends on the wallet's recovery model |
| Stolen login | Exchange may freeze account or investigate | Attacker with signing access may move assets immediately |
| Account lock | Support escalation usually exists | No central account administrator |
| Lost recovery phrase | Usually irrelevant to exchange login | Can cause permanent loss if no alternative recovery method exists |
| Malicious transaction | Some internal transfers may be stoppable | Confirmed onchain transactions are generally irreversible |
| Lost signing device | Account can normally be accessed another way | Recovery depends on wallet design and backups |
A self-custody user gains direct control over transaction authorization but assumes responsibility for the recovery phrase, also called a seed phrase, as well as private keys and signing access. A hardware wallet can isolate private keys from an internet-connected device, although it cannot rescue a user who knowingly approves a malicious transaction.
Users still learning recovery and transaction verification can start with our beginner crypto wallet guide before moving substantial balances into self-custody.
CEX vs DEX for Trading: Liquidity, Execution and Token Access
For active traders, the stronger venue is the one that offers the best executable market for the specific order. Liquidity, depth, routing and product design usually say more than the CEX or DEX label alone.
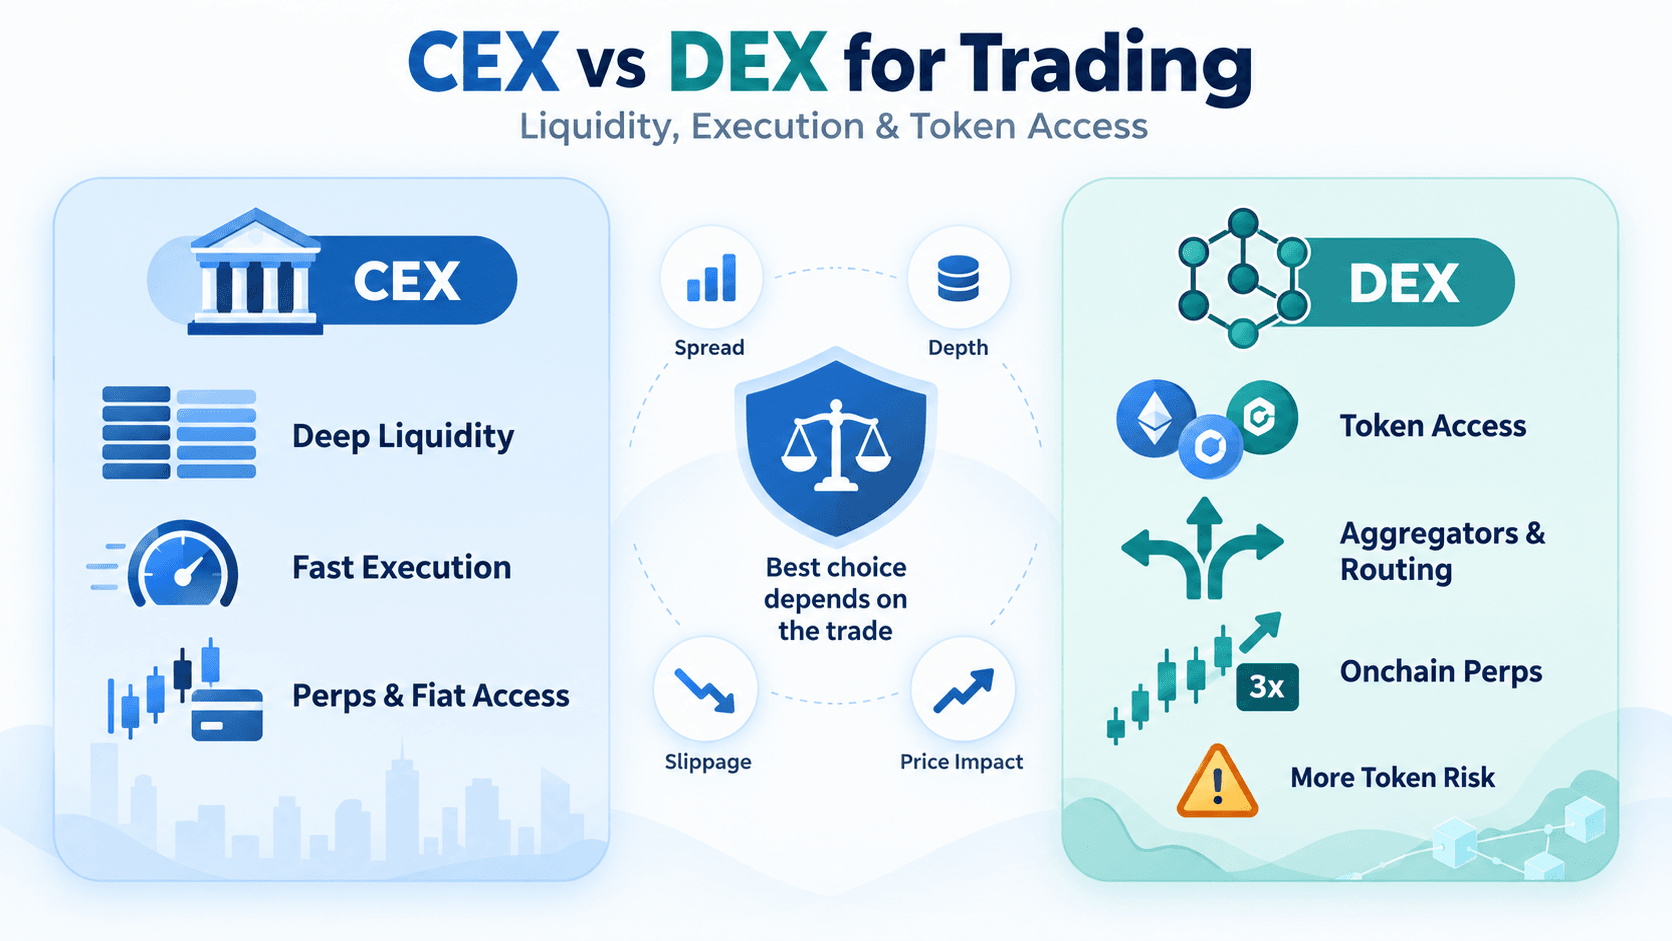 Liquidity And Execution Shape The Better Trading Venue
Liquidity and Trade Execution
Major centralized exchanges generally provide deep liquidity for major trading pairs, while DEX liquidity varies considerably by network, asset and venue. A CEX order book displays bids and asks across different price levels. Market depth shows how much can actually be bought or sold close to the current market price.
A tight spread can still hide a shallow book. If liquidity drops sharply after the first few price levels, a large market order may receive a poor average fill.
AMM liquidity works differently. The assets available in a pool and its pricing mechanism determine how much a transaction moves the price. Deeper liquidity around the current market price generally means lower price impact for a given order.
Order-book DEXs bring the mechanics closer to centralized venues. Aggregators add another layer by searching across multiple pools, routers or market makers instead of relying on one source of liquidity.
The practical comparison is therefore wider than "CEX uses an order book and DEX uses an AMM." Traders should compare market depth, spread, price impact, slippage, execution certainty and the final amount received.
Large Trades
Large traders should compare executable price rather than headline fees.
A low trading fee offers little comfort if a large market order moves through several price levels and creates much larger slippage. Conversely, a venue with a higher explicit fee may deliver a better total result if the available liquidity is considerably deeper.
For a large order, compare:
- Market depth: How much liquidity exists close to the current price?
- Price impact: How far does the order itself move the market?
- Order splitting: Can one order be divided across several liquidity sources?
- RFQ routing: Can professional market makers compete to quote the trade?
- Spread: What is the gap between immediately executable buy and sell prices?
- Execution fees: What trading, protocol or routing charges remain?
- MEV exposure: Can transaction ordering worsen the onchain execution?
DEX aggregators and RFQ systems have made this comparison more competitive. An order can sometimes be divided across pools or quoted by market makers instead of being pushed through one AMM.
Our DEX platforms for advanced traders guide compares aggregators, RFQ execution, MEV protection and other tools built for more demanding trades. For a six-figure order, the central question is how much of the destination asset the trader receives after execution.
Perpetual Trading Is Narrowing the CEX-DEX Divide
Perpetual futures historically gave centralized exchanges a major product advantage. Perpetual DEXs have narrowed that gap considerably.
Perpetual contracts have no fixed expiration date. Funding Rates help keep contract prices close to their underlying markets, while leverage lets a trader control a larger position with less posted collateral.
Modern perpetual DEXs can now provide order-book-style interfaces, leverage and sophisticated derivatives while keeping execution and settlement closely tied to blockchain infrastructure. Hyperliquid's order book, for example, uses the same price-time-priority logic familiar from centralized exchanges, while its perpetual markets use recurring Funding Rates.
The market data reflects the shift. Perpetual DEX volume increased from $81.74 billion in January 2024 to $739.48 billion in January 2026, increasing DEX market share from 2.0% to 10.2%.
CEXs still control the larger derivatives market and retain substantial advantages around fiat funding, traditional account infrastructure and customer support.
But derivatives are no longer an automatic CEX-only category. Traders comparing perpetual markets in 2026 have reason to evaluate individual DEXs on liquidity, leverage, execution, Funding Rates and platform risk.
DEXs Offer Broader Token Access, With More Token Risk
Permissionless DEXs can expose traders to tokens long before those assets appear on major centralized exchanges.
The reason is structural. A centralized exchange decides which assets enter its markets. A permissionless DEX can allow liquidity to be created for compatible tokens without waiting for a conventional listing process. Depending on the network, those markets can include ERC-20 tokens on Ethereum-compatible chains, Solana tokens and other blockchain-native assets.
The difference is enormous. CoinGecko counted 13.69 million token listings on Uniswap between January 2025 and January 2026, while even the most aggressive major CEXs listed only a fraction of the 24.04 million tokens created during the period.
Broader access also removes much of the screening associated with a centralized listing process.
That creates several risks:
- A token using a familiar ticker may have a completely different contract address.
- Scam tokens can imitate legitimate projects.
- Honeypot contracts can make purchasing possible while preventing or penalizing sales.
- Thin liquidity can make an apparent position difficult to exit.
- Newly created tokens may have little history, documentation or established market-making support.
DEX traders should therefore verify the token contract address, blockchain, liquidity and contract behavior rather than relying on the name or ticker alone.
CEX vs DEX Privacy, KYC and Regulation
CEXs commonly collect identity information because they operate account-based businesses subject to financial regulation. Permissionless DEX protocols can often be accessed through a wallet alone, but that makes the activity pseudonymous rather than invisible.
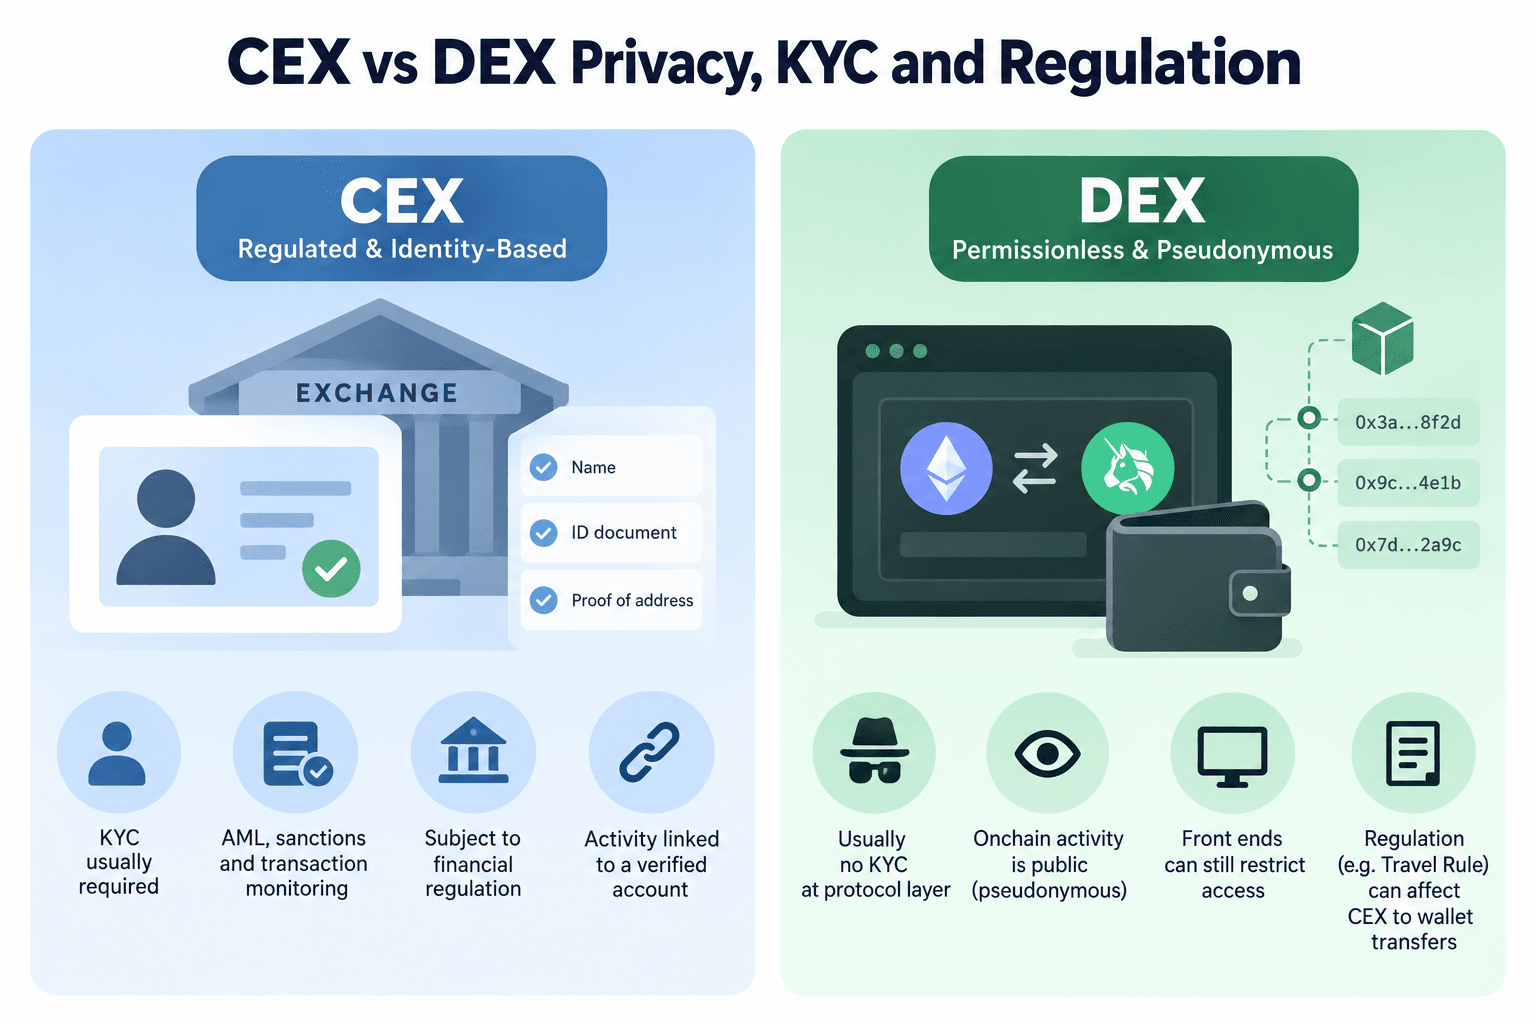 Privacy Changes Across Accounts, Wallets And Regulatory Layers
CEXs Commonly Require Identity Verification
Centralized exchanges commonly require account registration and Know Your Customer (KYC) checks before customers receive full access to trading, deposits or withdrawals. The exact requirements vary by exchange and jurisdiction. Verification can include a legal name, address, date of birth, government-issued identification, proof of address or additional checks.
Binance requires new users to complete its Verified identity level to access services including crypto deposits and trading. Coinbase likewise requires identity verification at account creation and periodically afterward.
KYC sits inside a wider compliance framework. Centralized exchanges may also perform anti-money laundering (AML) screening, sanctions checks, transaction monitoring and jurisdiction-based product restrictions.
The privacy trade-off is straightforward: a CEX can connect activity to a verified customer account far more directly than a permissionless protocol normally can.
DEX Trading Is Usually Pseudonymous, Not Anonymous
A permissionless DEX may let a trader connect a wallet and transact without providing a name, passport or conventional account profile. The blockchain transaction itself is normally public.
Public blockchains can record wallet addresses, token transfers, smart-contract interactions and transaction values. Anyone can inspect that history.
A wallet address may initially have no obvious real-world identity attached to it, making the activity pseudonymous. Blockchain analytics can still cluster addresses and transaction patterns. Transfers between that wallet and an identified exchange account or public address can provide additional links.
Lack of account registration therefore does not make blockchain activity invisible.
No KYC at the protocol layer does not mean anonymous trading.
A Permissionless Protocol Can Still Have a Restricted Front End
A decentralized protocol and the interface used to access it can operate under different rules.
It helps to separate four layers:
- Protocol: The smart contracts and rules that execute transactions.
- Governance: The mechanism or parties capable of changing parameters, upgrades or selected components.
- Front end: The website or app through which most users interact with the protocol.
- Supporting infrastructure: APIs, RPC providers, indexers, routers, relayers and other services surrounding the protocol.
These layers do not need to have the same degree of decentralization.
A smart contract can remain deployed on a public blockchain while a particular interface uses geofencing, wallet screening or token restrictions to limit access. Uniswap Labs' current terms apply to its products and interfaces and contain eligibility and sanctions restrictions. Its interface policies can also restrict individual token contracts or addresses.
The protocol and the commercial interface therefore need to be evaluated separately.
This also changes how permissionless access should be understood. A protocol may remain technically callable while a particular website, API or supporting service becomes unavailable to certain users.
"Decentralized" is consequently better treated as an architectural spectrum than a single yes-or-no property.
The Travel Rule Can Affect CEX-to-Wallet Transfers
The Travel Rule can add compliance checks when crypto moves from a regulated centralized exchange to an external wallet in some jurisdictions.
FATF's Travel Rule applies to covered virtual asset service providers (VASPs) and requires specified information about originators and beneficiaries to accompany qualifying transfers. Implementation has expanded quickly: FATF reported on July 16, 2026 that 83% of surveyed jurisdictions had passed Travel Rule legislation, compared with 73% in 2025.
The customer experience depends on the exchange and jurisdiction, but a CEX may request information such as:
- Whether the destination is a self-custody wallet or another service
- Whether the customer controls the receiving wallet
- Who the beneficiary is
- Which exchange, wallet provider or service is receiving the funds
These checks happen around the regulated intermediary. They do not turn a self-custody wallet into an exchange account.
The distinction is useful because "DEX equals no regulation" is too broad. A permissionless DEX protocol may not request identity information while the centralized fiat on-ramp or off-ramp surrounding it still does.
Which Is Better, a CEX or DEX?
Neither exchange model is best for every user. The better choice depends on what you are trying to do.
| If You Want To... | Usually Better Fit |
|---|---|
| Buy crypto directly with fiat | CEX |
| Cash crypto out to a bank | CEX |
| Trade major pairs frequently | CEX |
| Get account recovery and support | CEX |
| Keep custody while trading | DEX |
| Trade newly issued onchain tokens | DEX |
| Access DeFi directly | DEX |
| Trade onchain perpetuals | Perpetual DEX |
| Reduce reliance on one exchange | Use both |
| Move between fiat and onchain markets | Use both |
The job should come before the exchange label. Someone buying ETH from a bank account has different requirements from a trader swapping a newly issued token or running a leveraged perpetual position.
When a Centralized Exchange Makes More Sense
A centralized exchange usually makes more sense when fiat access, account recovery and straightforward market access are priorities.
Typical users include:
- Beginners making their first crypto purchase
- Users who need fiat deposits or withdrawals
- Frequent spot traders focused on liquid mainstream pairs
- Users who value account recovery and customer support
- Traders concentrating on established assets
- Users who are not comfortable managing private keys, recovery phrases and blockchain networks
A CEX reduces some operational complexity while adding reliance on the operator. Custody practices, withdrawal reliability, account security, regulation and financial transparency still deserve scrutiny.
Our guide to the basics of crypto trading gives beginners a clearer starting workflow before they move into more complex exchange or wallet setups.
When a Decentralized Exchange Makes More Sense
A decentralized exchange usually makes more sense when maintaining self-custody and accessing onchain markets are the priorities.
Typical users include:
- Self-custody users who want to retain signing authority
- Traders already comfortable operating from crypto wallets
- DeFi users moving between onchain applications
- Traders seeking assets absent from major centralized exchanges
- Users who understand gas, token approvals, slippage and smart-contract risk
- Traders using specialist products such as aggregators or perpetual DEXs
DEX access reduces reliance on a conventional exchange account while increasing the number of decisions the user must make correctly.
Someone unable to verify networks, token contracts, wallet addresses and transaction requests should learn those processes before moving substantial value onchain.
Can You Use Both a CEX and DEX?
Using both is often the most practical arrangement because CEXs, wallets and DEXs solve different parts of the crypto workflow. A user does not need to make one venue the permanent home for every transaction.
A Typical CEX-to-DEX Workflow
A common flow is:
Bank → CEX → buy crypto → withdraw to self-custody wallet → connect to DEX/aggregator → trade onchain → return to CEX when fiat off-ramp is needed
- Fund the CEX with fiat.
Choose an available bank or payment rail and check funding costs before depositing. - Buy the required crypto.
Consider what asset and blockchain will be needed after withdrawal. Stablecoins such as USDC and USDT exist on multiple networks, so matching the ticker alone is not enough. - Choose the withdrawal network.
The network selected at the exchange must match the network supported by the receiving wallet for that asset. Check the withdrawal fee before confirming. - Verify the wallet address.
Copy the destination address directly from the wallet and confirm the network. A small test transaction can be sensible before a much larger transfer. - Keep the required gas token.
Onchain transactions need the network's native fee asset. Ethereum transactions require ETH, while Solana transactions use SOL. - Connect the wallet to the DEX or aggregator.
Verify the interface before connecting and review token approvals and transaction requests before signing. - Inspect the trade quote.
Check the route, price impact, slippage tolerance, minimum received and estimated network cost rather than looking only at the swap fee. - Return to a CEX when fiat is required.
Send a supported asset back through an accepted blockchain network, complete any compliance information requested and use the exchange's fiat off-ramp.
Network selection and address verification can be more consequential than small differences in trading fees. Our crypto exchange vs wallet guide covers the transfer and custody side of that workflow in more detail.
When Using Both Reduces Trade-Offs
Using both works best when each layer has a defined job.
- CEX: Fiat deposits and withdrawals, liquid mainstream markets and account-based trading.
- Wallet: Custody and transaction authorization.
- DEX: Onchain execution, broader token access and DeFi.
Consider someone who receives income in dollars but regularly uses DeFi. A CEX can handle the fiat on-ramp. Part of the resulting crypto can move to a self-custody wallet for onchain activity, while the amount needed for exchange trading stays in the CEX account.
An active trader may divide the setup differently. Major BTC or ETH pairs could be traded through a deep centralized order book while a separate wallet handles newly issued tokens or onchain perpetuals.
More components also create more operational work. Each additional wallet, blockchain network, approval and transfer creates another opportunity for a mistake.
Some users are better served by one carefully chosen CEX. Others have a clear reason to separate fiat access, custody and onchain execution. CEXs and DEXs are tools for different jobs rather than rival systems that require permanent allegiance.
Centralized vs Decentralized Exchanges: Final Verdict
CEXs are generally the better starting point for fiat access, straightforward account management, deep liquidity in mainstream markets and users who value customer support and recovery. Their central weakness is counterparty risk: funds held with a custodial exchange depend on the operator's security, financial controls and ability to honor withdrawals.
DEXs generally suit users prioritizing self-custody, permissionless onchain markets and direct access to DeFi. Their safety depends heavily on smart contracts, wallet security, transaction signing and user behavior. Wider token access also brings greater scam and liquidity risk.
Neither model is inherently cheaper. Trading fees are only one part of execution; spread, gas, slippage, liquidity, price impact and routing can determine the actual winner.
Many experienced users therefore combine both depending on the transaction.
For specific platforms, compare our best crypto exchanges guide, best decentralized exchanges guide and best crypto wallets guide.